

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
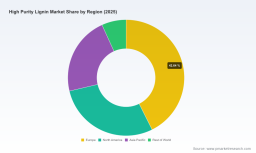
PW Consulting: Worldwide High‑Purity Lignin Market Poised for 7.21% CAGR Through 2032 as Europe Emerges as Leading Region

Worldwide High Purity Lignin Market — Strategic Briefing for 2026 Decision‑makers
Executive trailer
PW Consulting today publishes an advanced industry briefing to accompany our forthcoming Worldwide High Purity Lignin Market report. This briefing is designed as a strategic “preview”: it surfaces the decisive trends, competitive dynamics, operational levers and near‑term actions that senior executives, corporate development teams and investment committees must consider as they set priorities for 2026. The full report contains the granular datasets, supplier scorecards and transaction pipeline intelligence necessary to execute on these opportunities; the summary below signals where value will accrue and why immediate alignment to new playbooks matters.
Worldwide High Purity Lignin Market
Macro view: market scale and trajectory
High purity lignin has moved from niche specialty to a commercially investible industrial platform. Our market accounting shows the sector more than doubled in measured revenue through the early 2020s, rising from a lower‑tens position in 2020 to a mid‑double‑digit figure by the 2025 base year. The market enters the 2026–2032 forecast window with a structurally positive outlook — a compound annual growth rate (CAGR) of roughly 7.2% across the forecast period. Under that trajectory, demand and monetizable revenue are expected to converge with new scaling of downstream applications such as carbon materials, resins and bio‑polymers, supported by strengthened policy incentives and industrial adoption curves.
Worldwide High Purity Lignin Market
Why 2026 is an inflection year
-
Commercial readiness and scale: Late‑stage pilot projects are transitioning into early commercial shipments; a number of vendors reported first large‑bag deliveries and demo‑plant launches in 2024–2025. These shifts compress lead times for procurement and qualification cycles, opening windows for offtake agreements in 2026.
Worldwide High Purity Lignin Market -
Policy momentum: Stringent carbon and circular‑economy regulations in key markets, paired with green public procurement, materially improve the business case for lignin substitution in multiple value chains. Expect procurement teams and product stewards to prioritize low‑embodied‑carbon raw materials in 2026 RFPs.
-
Feedstock economics and capacity dynamics: Global kraft pulping and lignin extraction capabilities have reached substantive scale, creating a more predictable feedstock base. That predictability reduces commercial risk but raises the bar for differentiation at the product and application level.
What the full report delivers (practical content)
PW Consulting’s full deliverable is intentionally hands‑on. It is designed not just to inform, but to enable execution across procurement, R&D and M&A. Key practical components include:
-
Granular market-sizing and scenario models (base, adoption, stress) that let clients run bespoke revenue and margin sensitivities.
-
Supplier benchmarking and scorecards covering technology platform, purity specifications, certification, capacity outlook, and commercial terms.
-
Application ROI playbooks for resins, carbon fiber precursors, bioplastics and specialty chemistries, with cost parity thresholds and substitution roadmaps.
-
Regulatory and funding maps showing where public incentives, procurement policy and procurement tenders favor lignin‑based solutions.
-
Technology maturity and commercialization roadmaps with recommended partnership structures (pilot → co‑development → local sourcing) for accelerating product qualification.
-
M&A and JV target shortlists aligned to three buyer archetypes: feedstock owners, downstream formulators and strategic end‑users seeking backward integration.
-
Operational checklists for scaling: quality control protocols, sampling regimes, logistics options (from bulk big‑bag distribution to integrated pipeline solutions) and embodied‑carbon accounting templates.
Competitive landscape: who matters and why
The market is moderately concentrated: the top three suppliers capture a meaningful share of current commercial volumes, while the top five increase that presence substantially. This concentration profile creates both constraints and opportunities for buyers and investors.
From a strategic standpoint, several company profiles merit particular attention:
-
Borregaard (Norway): A legacy incumbent with deep application engineering expertise and a long history of lignin‑based product commercialization. Borregaard’s strength is in formulation support and tailored biopolymer solutions across dispersants, binders and industrial substitutes — a natural partner for formulators seeking rapid product qualification.
-
Stora Enso (Finland): A leader in kraft lignin commercialization with branded portfolios and demonstrated pathway to battery‑grade carbons through partnerships. Their platform is attractive to strategic buyers targeting advanced materials applications, especially where vertical integration with pulp operations is a value lever.
-
UPM Biochemicals (Finland): Emphasizes consistent quality and formulation support, positioning itself as a reliable supplier for resins and adhesives. For industrial customers, UPM represents a lower technical risk option when precision in feedstock behaviour is required.
-
Mercer International, Domtar, West Fraser, Metsä Group and Nippon Paper Industries: These pulp‑operator adjacent players leverage integration into existing mill flows and certifiable forestry supply chains. They are the most credible sources of scale—critical where customers require long‑term security of supply.
-
Pure Lignin, Lignin Industries and other technology‑led SMEs: These players are pioneering high‑purity native fractions and thermoplastic conversion technologies. They are important innovation partners and potential bolt‑on targets for larger integrators or specialty material manufacturers.
Recent industry moves that change the playbook
-
Early commercial shipments (2025): The first large‑scale shipments from pilot phase producers signal that qualification cycles can now be compressed from years to quarters. Corporates should revisit supplier onboarding timelines and consider staged offtake models.
-
Demo‑plant product launches: Demo‑scale outputs for specific uses (for example concrete admixtures) mean that construction and infrastructure procurement teams can pilot lignin‑based chemistries in real projects—opening procurement windows for 2026 tenders.
-
Cross‑industry partnerships: Collaborations that adapt lignin for battery anodes and sodium‑ion chemistries show the material’s versatility beyond traditional resin or binder markets. R&D teams should explore co‑development agreements to de‑risk technical transfer.
Strategic implications and prioritized actions for 2026
Based on our analysis, executives should organize a focused set of cross‑functional initiatives in 2026 to capture first‑mover advantage while reducing commercialization risk:
-
Accelerate supplier qualification with staged offtake and co‑development clauses: Use pilot purchases with defined scale‑up triggers to secure pricing and priority allocation without locking capital prematurely.
-
Deploy application‑level pilots tied to procurement levers: Work with suppliers to instrument pilots where total cost of ownership and carbon accounting can be demonstrated in real projects; prioritize areas where substitution delivers both cost and regulatory compliance benefits.
-
Reassess capex vs contract supply economics: For companies with access to feedstock (pulp mills, forestry operations), evaluate backward integration. For formulators, weigh multi‑supplier contracts to manage supply continuity.
-
Map M&A and JV targets by capability: Identify technology innovators to secure IP footholds and pulp‑integrated players to shore up volumes. The full report provides an expedited target shortlist aligned to buyer strategy archetypes.
-
Institutionalize embodied‑carbon accounting protocols: As disclosure rules tighten, early adoption of consistent carbon metrics will speed market access and reduce commercial friction in green procurement.
Risk matrix and mitigation
Adoption risks are tangible but manageable. Key risk vectors include feedstock price volatility, specification drift across mills, regulatory uncertainty, and competition from alternative bio‑polymers. Effective mitigations include diversified supplier panels, specification harmonization programs, indexed pricing in offtake contracts, and staged technical milestones in co‑development agreements.
How PW Consulting helps clients act in 2026
PW Consulting couples primary supplier diligence with rigorous scenario modeling and executable playbooks. Clients benefit from:
-
Executable procurement templates and negotiation playbooks that incorporate quality spec clauses, escalation pathways and ramp schedules;
-
Tailored application ROI models that translate lab metrics into P&L impacts and payback periods;
-
A prioritized M&A/JV target map with valuation heuristics and integration checklists;
-
Regulatory and funding opportunity trackers that connect project profiles to available grants and green tenders.
Final note — why this is a must‑read for 2026 planners
The high purity lignin sector is moving from technical promise to commercial substance. The market’s compound growth and evolving supplier ecosystem create a narrow window in 2026 for strategic commitments that shape long‑term cost structures and product roadmaps. Firms that align procurement cycles, R&D partnerships and capital allocation to the realities outlined in this briefing will secure advantaged access to both feedstock and market share as the sector expands.
Learn more
This preview outlines strategic priorities and the operational playbooks required for near‑term action. PW Consulting’s full Worldwide High Purity Lignin Market report contains the underlying datasets, segmentation analytics, supplier scorecards and M&A shortlists that support immediate execution. To access full intelligence and client‑only advisory services for 2026 implementation, please consult PW Consulting’s report page or contact our Industrial Bioeconomy practice team.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com