

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive FPC Market Poised for Rapid Expansion — 16.0% CAGR Forecast Through 2032

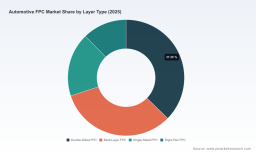
Worldwide Automotive Flexible Printed Circuit (FPC) Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest flagship study on the Worldwide Automotive FPC Market provides the strategic line-of-sight that automotive OEMs, Tier‑1s, semiconductor suppliers and private investors need as they shape 2026 roadmaps. The market has evolved from an emerging systems enabler into a foundational component for electrification, ADAS/autonomy and increasingly complex in-cabin experiences. Our analysis shows that the total market expanded from approximately USD 1.05 billion in 2020 to USD 2.61 billion in 2025, and is projected to exceed USD 3.28 billion in 2026. Over the 2026–2032 forecast window the market is modeled to grow at a compound annual growth rate (CAGR) of roughly 16%, reaching an estimated USD 7.37 billion by 2032.
Worldwide Automotive FPC Market
Why this report matters for 2026 strategic choices
-
Timing capex and capacity: With double‑digit growth and upward cost pressure on key raw materials, 2026 is a pivotal year to decide whether to scale in‑house FPC capabilities, secure long‑term supply contracts, or outsource to qualified partners.
Worldwide Automotive FPC Market -
Product architecture trade‑offs: FPCs are no longer limited to simple interconnects; design choices (rigid‑flex, multilayer vs. double‑sided layouts) materially affect system reliability, EMC behaviour, and manufacturability. Our scenario modeling quantifies the break‑even windows for such trade‑offs under near‑term material cost shocks.
Worldwide Automotive FPC Market -
Compliance, safety and cybersecurity: As functional safety standards and vehicle cybersecurity rules tighten, procurement and quality teams must bake compliance into supplier selection. The report maps ASIL implications and regulatory touchpoints to supplier capabilities so product, compliance and sourcing groups can speak the same language in 2026 negotiations.
-
M&A and partnership prioritization: With a moderately concentrated vendor landscape, selective acquisitions or strategic alliances can accelerate capability capture. Our competitive heat‑maps indicate which technology gaps are most commonly targeted by recent M&A and co‑development activity.
Market dynamics shaping 2026 playbooks
The FPC market sits at the intersection of three structural forces — electrification, sensing/compute proliferation, and in‑cabin digitalization. Each of these creates distinct technical demands (high‑current battery monitoring, high‑speed data lines for sensors, and fine‑pitch designs for displays) that push FPC complexity upward.
Meanwhile, cost dynamics and regulation are exerting outsized influence:
-
Raw material volatility: Global copper foil disruptions and a near‑term 15% YoY rise in copper foil prices have compressed margins for FPC manufacturers. Polyimide film supply tightness and feedstock price swings have added another layer of cost pressure, particularly for high‑temperature and high‑reliability FPC variants.
-
Labor and skills: Quality‑intensive FPC assembly requires skilled operators and advanced process controls. Our field interviews and market cost models show an increased production cost baseline in Asia‑Pacific driven by a skilled labor shortage, prompting multiple suppliers to automate selective production lines in 2025–26.
-
Regulatory lift: ISO 26262 evolutions and EU cybersecurity regulations are raising the bar for component qualification. For safety‑critical applications such as airbag controllers and certain battery management functions, the need for ASIL‑aligned design and documentation is non‑negotiable — and it changes supplier evaluation criteria.
Competitive landscape — what we found
The FPC supplier ecosystem remains clustered around established electronics materials and manufacturing houses, with a top‑three concentration that together command a meaningful share of the market and a top‑five that extends industry control. Our market concentration metrics identify a CR3 of about 42.5% and a CR5 of about 58.8%, a structure that favors established incumbents yet leaves space for focused challengers with specialized technology or cost advantages.
-
Nitto Denko Corporation (Japan) — A leader in automotive FPCs, recognized for high‑reliability solutions for instrument panels, airbags and sensors. Nitto’s October 2025 launch of an AEC‑Q100 compliant FPC series for EV battery monitoring underscores the company’s emphasis on validated, safety‑oriented product families.
-
Sumitomo Electric Industries, Ltd. (Japan) — Strong in high‑density FPCs used across ECUs, infotainment and ADAS. Public supplier nominations in mid‑2025 reflect deep OEM relationships and entrenched design wins for next‑generation ADAS platforms.
-
Nippon Mektron, Ltd. (Japan) — Well‑regarded for multilayer FPCs in cameras, LiDAR and battery management. A joint development agreement with a European automaker announced in early 2025 signals a trend toward regionally co‑developed supplier models for autonomy sensor stacks.
-
Flexium Interconnect, Inc. (Taiwan) — Focused on automotive displays and lighting. Its product portfolio aligns with the growing in‑vehicle display and cockpit requirements for thin, flexible interconnects.
-
Interflex Co., Ltd. (South Korea) — Supplies FPCs for touch panels, sensors and power distribution; proximity to major OEMs in Korea supports rapid integration cycles.
-
Zhen Ding Technology Holding Limited (Taiwan) — Moving into EV battery pack segments and high‑speed data transmission applications; completed validation for solid‑state battery integrations in late 2024.
-
Multi‑Fineline Electronix, Inc. (MFLEX) (USA) — Specialty supplier offering custom FPCs for wearables integration and ADAS-related modules; attractive for North American design teams seeking local support.
-
Fujikura Ltd. (Japan) — Focused on harness replacement and high‑frequency transmission; its strengths sit at the junction of traditional wire harness know‑how and modern printed interconnect requirements.
Recent supplier developments — supplier nominations, product launches and cross‑border co‑development agreements — show two clear industry dynamics: (1) OEMs prefer partners who can simultaneously deliver design support and validated reliability for safety‑critical uses; and (2) suppliers are investing in application‑specific FPC series that meet automotive test standards to accelerate qualification cycles.
Report contents — what you’ll find inside (select highlights)
Our report is structured to be immediately actionable for leadership teams and procurement cells preparing 2026 budgets and sourcing strategies. Key elements include:
-
Market sizing & forecast: An independent base (2025) and detailed 2026–2032 forecasts, including sensitivity scenarios that account for raw‑material and regulatory shocks.
-
Technology taxonomy and roadmaps: Comparative analysis of single‑sided, double‑sided, multi‑layer and rigid‑flex FPCs, and guidance on where each technology yields competitive advantage by application area.
-
Supplier scorecards: Third‑party validated assessments covering quality systems, automotive certifications, manufacturing footprint, innovation pipeline and price competitiveness.
-
Cost‑to‑serve models: Granular factory and logistics modeling that isolates the drivers of unit cost under different procurement modes (make, buy, JV), useful for ROI and capex prioritization.
-
Regulatory & compliance playbook: Practical checklists and timelines for achieving ASIL and cybersecurity readiness in the supplier audit process.
-
Supply chain stress tests: Simulated disruption scenarios (copper, polyimide, labour) and recommended mitigation measures including strategic inventories, dual sourcing and nearshoring thresholds.
-
M&A and partnership decision framework: Criteria and scorecards designed to evaluate target fit given technological, geographic and regulatory considerations.
Actionable recommendations for 2026
-
Lock strategic raw‑material links: Negotiate indexed/volume contracts for copper foil and polyimide film, and layer contingent pricing clauses to protect margins against feedstock volatility.
-
Pursue co‑development with tiered qualification milestones: Shorten time‑to‑production by sharing compliance testing schedules and integrating supplier test results early in vehicle programs.
-
Prioritize modular architectures: Where feasible, standardize on modular FPC subassemblies to reduce qualification cycles and enable supplier interchangeability.
-
Build redundancy into critical nodes: For battery management and safety‑critical sensor lines, deploy dual suppliers or geographic diversification to hedge concentrated capacity risks.
-
Invest in verification and cyber‑hardening: Augment supplier audits with cybersecurity checklists tied to EU regulation expectations and ISO functional safety artefacts.
-
Consider targeted equity plays: If rapid capability capture is required, pursue minority stakes in specialist FPC houses that offer unique materials expertise or proprietary process IP.
How executives should use this study
Use the report as the strategic basis for 2026 procurement negotiations, product architecture reviews, and investment memos. The materials include executive one‑pagers for board briefings, a supplier short‑list engine, and negotiation playbooks that align sourcing levers to forecasted market scenarios. Importantly, while we present comprehensive market sizing and supplier intelligence, detailed segment tables and confidential supplier scoring matrices are reserved for report subscribers — enabling you to base decisions on validated primary data and robust scenario analysis.
Conclusion — the 2026 inflection
The FPC market for automotive is entering a phase where technical differentiation, regulatory readiness and supply resilience will determine winners and losers. With a strong historical expansion to USD 2.61 billion in 2025 and aggressive projected growth into 2032, 2026 should be treated as a decision year: strengthen supplier relationships now, align architectures to safety and cyber standards, and build procurement protections against raw‑material and labour volatility. PW Consulting’s Worldwide Automotive FPC Market report equips decision‑makers with the quantitative forecasts, supplier insights and tactical playbooks to make those choices with confidence.
For executives seeking the full dataset, supplier scorecards and scenario workbooks, please visit the PW Consulting report page to access the complete Worldwide Automotive FPC Market study and our advisory services for tailored implementation plans.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com