

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Chinese Domestic Databases Market to Grow at 18.5% CAGR, Reaching USD 12,468 Million by 2032
By pmarketresearch, 2026-07-15
PW Consulting: Strategic Brief — Worldwide Chinese Domestic Databases Market Report (Base Year 2025) and What It Means for 2026 Enterprise Strategy
PW Consulting today publishes its latest strategic intelligence on the Worldwide Chinese Domestic Databases Market, a forward-looking study built to inform executive decisions in 2026 and beyond. Anchored on a robust base year of 2025 and a historical series from 2020–2025, our model projects this market at approximately USD 3.8 billion in 2025 and growing at a compounded annual growth rate (CAGR) of 18.5% across the 2026–2032 forecast window. By 2032 the market is expected to exceed USD 12 billion under our base forecast — a scale and trajectory that elevate database strategy from a technical procurement issue to a board-level strategic agenda.
Worldwide Chinese Domestic Databases Market
Why this report matters for 2026 decisions
-
Regulatory momentum is reshaping procurement and architectural priorities. Significant amendments to China’s Cybersecurity Law, effective January 1, 2026, coupled with ongoing enforcement of the Data Security Law and the Personal Information Protection Law, place data sovereignty, localization and rigorous cross-border controls at the center of database selection and deployment strategies.
Worldwide Chinese Domestic Databases Market -
The xinchuang (IT application innovation) initiative continues to drive mandatory replacement of certain foreign database systems within government, state-owned enterprises and critical industry verticals. This policy dynamic is a primary market driver for domestic database adoption and demonstrably alters procurement risk profiles and vendor evaluation criteria for 2026.
Worldwide Chinese Domestic Databases Market -
Infrastructure and economic levers — including national-scale data center deployments exceeding 4.2 million standard rack units and targeted local subsidies for data centers adopting domestic chips — lower some barriers to migration but also create new operational design choices between centralized and regionally distributed deployments.
What the report delivers: practical tools, not just charts
Designed as a decision-support instrument for CIOs, CDOs, procurement leads and industry strategists, the report blends rigorous market modeling with hands-on, executable artifacts. Highlights include:
-
Scenario-based market forecasts and sensitivity models that map how combinations of regulatory change, cloud adoption, and macroeconomic shock affect market size and vendor positioning through 2032.
-
Vendor scorecards and comparative capability matrices across technical dimensions (distributed consistency models, hybrid transaction/analytics capability, AI and vector-search readiness, observability and O&M tooling), security/compliance posture, and go-to-market reach.
-
Proven migration playbooks and templated procurement artifacts including TCO frameworks, contract clauses to address data sovereignty and cross-border transfer risk, and SLA/penalty constructs tailored for regulated enterprises.
-
Operational blueprints for hybrid architectures and phased cloud-native adoption, including benchmarked performance-validation procedures and rollback strategies for mission-critical core systems.
-
Case studies and implementation retrospectives from large government and financial deployments that highlight failure modes, remediation techniques and measurable business outcomes.
Competitive landscape — strengths, trajectories and what they imply for buyers
The domestic database ecosystem is maturing rapidly, with a mix of hyperscalers, specialized vendors and open-source-driven entrants now shaping procurement choices. Market concentration metrics indicate a market in the middle stages of consolidation, with the top three players commanding a near-majority share and the top five a substantially larger combined footprint. For enterprise buyers, this concentration means fewer but stronger options — and the need to evaluate scale-related resilience and lock-in risk as much as technical capability.
Key vendor dynamics captured in the report include:
-
Alibaba Cloud (OceanBase, PolarDB) — A dual approach of fully self-developed distributed databases (OceanBase) and cloud-native variants (PolarDB). OceanBase’s adoption in high-stakes financial systems and PolarDB’s benchmark performance achievements make Alibaba Cloud a natural consideration for enterprises prioritizing scale and performance. Recent releases through late 2025 and early 2026, including enhanced O&M tooling and open-source AI-native initiatives, point to a strategic push into AI-augmented database capabilities.
-
Huawei Cloud (GaussDB) — Positioned for high-end telecommunications, finance and government workloads with deep integration for large-scale core systems. Huawei’s trajectory reflects an emphasis on resilience, specialized optimizations and compliance-aligned offerings.
-
Tencent Cloud (TDSQL) — Strong domestic cloud-native portfolio focused on enterprise, gaming and transactional workloads. Tencent’s strengths include a broad cloud ecosystem and vertically integrated services for high-throughput applications.
-
PingCAP (TiDB) — An open-source NewSQL leader with wide enterprise adoption and clear strengths in hybrid transactional and analytical processing. TiDB’s ecosystem orientation is attractive for teams prioritizing flexibility and community-driven innovation.
-
Specialized and domestic-focused vendors such as SequoiaDB, Wuhan Dameng, KingbaseES, GBase and others provide focused value propositions for regulated industries and localization mandates, including financial-grade security features and compliance certifications.
Recent product and ecosystem moves — for example, OceanBase’s open-sourcing of an AI-native hybrid search capability and PolarDB’s benchmark and regional expansion achievements — underscore two converging technical trends: (1) integration of AI and vector search capabilities into core database engines, and (2) increasing parity between cloud-native and on-prem capabilities in performance and observability. Buyers must therefore validate vendor roadmaps for AI-first capabilities alongside compliance and operational maturity.
Strategic implications and recommended 2026 actions
Enterprises face a compressed decision horizon in 2026 where technology, regulation and vendor strategy intersect. PW Consulting recommends a six-step decision framework to convert risk into opportunity:
-
Data classification and risk triage: Initiate an accelerated 90-day program to classify data by regulatory sensitivity and business criticality. Use classification outcomes to map workloads to target architectures (on-prem, hybrid, cloud-native) with explicit compliance control gates.
-
Pilot to industrialize: Select two representative pilot workloads (one core transactional, one analytics/AI) and run vendor-neutral PoCs using the report’s benchmark and observability playbooks. Prioritize reproducible test harnesses and performance-to-cost measures rather than vendor marketing claims.
-
Procurement with compliance-first clauses: Embed supply-chain and localization clauses, audit rights, and data export controls into procurement templates. Leverage the report’s contract language examples to reduce negotiation cycles and downstream legal risk.
-
Hybrid operations and O&M modernization: Invest in unified observability and automated operations tooling early. Our analysis shows that O&M maturity materially reduces downtime and total cost of ownership for distributed and cloud-native deployments.
-
Diversify vendor risk while aligning on standards: Avoid single-vendor monocultures for the highest-risk datasets. Favor architectures and vendors that support clear migration paths, open ecosystems or standardized replication mechanisms to maintain optionality.
-
Upskill and establish an AI-readiness roadmap: With leading vendors integrating vector and text search capabilities into databases, embed an AI-readiness assessment into your 2026 planning cycle to capture new product capabilities without sacrificing governance.
How to use this report in your 2026 planning cycle
Our report is structured for action. Use the executive summary and scenario dashboards to brief boards and steering committees. Operational teams will find immediate value in the TCO models, migration playbooks and vendor scorecards — tools designed to reduce analysis paralysis and accelerate procurement timelines. Finally, the regulatory risk matrix and checklist are purpose-built for compliance and legal teams facing new regulatory milestones in 2026.
We intentionally keep this brief at the macro level in order to protect the tactical datasets, vendor scoring rubrics and granular segmentation models that are included in the report package. Those datasets — including the detailed region-by-application splits, price-point matrices, and full vendor scorecards — are available through the report portal for subscribers and licensed purchasers.
Final note — translating insight into advantage
Database strategy in 2026 will be defined as much by regulatory posture and procurement design as by raw technical capability. The market’s rapid growth, driven by domestic policy, national-scale infrastructure and vendor innovation, presents a window for enterprises to rearchitect data platforms with sovereignty, cost efficiency and AI-capability in mind. PW Consulting’s Worldwide Chinese Domestic Databases Market report gives leaders the frameworks, benchmarks and actionable artifacts necessary to make those choices with confidence.
For boards and senior IT leaders preparing strategic decisions this year, the question is no longer whether to act — it is how quickly and with what safeguards. Our report is designed to shorten the path from strategy to delivery while preserving the optionality and compliance certainty today’s regulatory environment demands.
To access the full dataset, interactive models and vendor scorecards that underpin our analysis, please visit the PW Consulting report portal and request the Worldwide Chinese Domestic Databases Market report package.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reveals Worldwide Rotary & RF Rotary Joints Market to Hit USD 985.28 Million in 2025, Forecasted to Grow at a 5.1% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Rotary and RF Rotary Joints Market — Strategic Outlook for 2026: PW Consulting Report Highlights
PW Consulting’s new market brief on Worldwide Rotary and RF Rotary Joints synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering the strategic intelligence that executives and investors need to act in 2026. The global market is estimated at USD 985.3 Million in 2025, rising from approximately USD 785.4 Million in 2020, and is projected to reach roughly USD 1,395.7 Million by 2032 — an implied compound annual growth rate (CAGR) of 5.1% across the 2026–2032 forecast window. This briefing highlights the decision-grade implications of that trajectory while deliberately preserving the full granularity of segment and regional splits for subscribers of the full report.
Worldwide Rotary and RF Rotary Joints Market
Why this report matters for 2026 decision-makers
-
Actionable market sizing and pacing. The 5.1% mid-term CAGR signals steady, profitable expansion rather than hypergrowth — a profile that favors disciplined capital allocation over speculative scale-up. Executives weighing capacity investments, product launches, or M&A need this pacing to prioritize near-term spend versus multi-year platform builds.
Worldwide Rotary and RF Rotary Joints Market -
Signal-to-noise separation. Our analysis consolidates raw market trends, supplier moves, materials dynamics, and regulatory drivers into an operational roadmap. We convert broad macro indicators (market size, concentration indices, and growth drivers) into practical choices for R&D, manufacturing, commercial and corporate development teams.
Worldwide Rotary and RF Rotary Joints Market -
Trailer principle: we present definitive strategic insight here while preserving the report’s proprietary segment-level forecasts, regional breakdowns and supplier scorecards to motivate full report access — the place to obtain the detailed allocation and opportunity maps required for execution.
Market dynamics shaping 2026 strategies
-
Technology convergence and premiumization. Demand is migrating toward compact, high-frequency, multi-channel RF rotary joints, and hybrid solutions combining electrical, optical and fluid transfer capabilities. Drivers include expanded satellite communications, phased-array radar deployment, and growth in medical imaging. These forces raise the technical bar and create revenue upside for suppliers that can deliver high-channel-density, low-loss, environmentally qualified products.
-
Service and aftermarket economics. As installed bases grow, lifecycle service, spares, and retrofit opportunities are material contributors to margin. Field diagnostics and predictive maintenance add a recurring-revenue dimension to historically product-centric business models.
-
Materials and manufacturing cost signals. Primary structural alloys matter: steel cost cycles are moderating heading into 2026, while aluminum averaged near USD 2,945/t in early-2026 conditions. These inputs influence design choices (lightweight vs. heavy-duty), yield expectations, and hedging policies for manufacturers targeting aerospace and defense segments where weight and reliability tradeoffs are paramount.
-
Standards and certification pressure. Suppliers targeting space, defense and critical aviation markets maintain AS9100 and ISO 9001 certifications as a baseline. Certification is not a checkbox; it’s a market-access cost that affects quoting, lead-times, and partnership eligibility.
-
Digital enablement. RF rotary joints are increasingly embedded with IoT-based condition monitoring sensors to enable predictive maintenance, reduce unscheduled downtime, and create service bundling opportunities. Firms that integrate robust sensing, telemetry and analytics into product roadmaps will secure higher lifetime value per unit.
Competitive landscape: what leaders are doing
The market is neither hyper-consolidated nor atomized: the top three vendors collectively account for a meaningful minority share, and the top five remain substantially below a dominant concentration threshold. That structure creates room for both scale plays and focused specialists. Illustrative strategic postures among leading firms include:
-
Deublin Company (United States): continuing to leverage breadth and scale in industrial rotary unions, Deublin’s trade show presence and portfolio expansions reflect a push into automation and semiconductor segments. Their recent acquisition activity reinforces a buy-and-integrate approach to expand capability sets.
-
Moog Inc. (United States): advances like integrated slip ring/rotary union combinations for collaborative robots showcase a product-led play to capture emergent automation applications. Lightweight hybrid devices for cobots and aerospace remain a strategic focus.
-
Spinner GmbH (Germany) and other RF specialists: firms concentrating on high-performance RF and hybrid rotary joints are competing on electrical performance, environmental robustness and integration into complex radar and satcom systems.
-
Diamond Antenna and Microwave Corporation (United States): with AS9100/ISO 9001 capability updates, the company exemplifies a quality-first strategy to win defense, space and radar contracts where certification and repair capability are competitive differentiators.
-
Regional and emerging suppliers (China, Europe): manufacturers with integrated slip ring and fiber-optic competencies are targeting automation and robotics markets with cost-competitive solutions. Their playbooks emphasize modular design and short lead-times.
Recent vendor moves illustrate these themes: participation at major automation trade shows, product launches for hybrid slip ring/rotary union devices, strategic acquisitions to broaden solution stacks, and certification renewals that sustain access to regulated end markets. These signals indicate a competitive environment where technology integration and service capability are as important as volume manufacturing.
Operational playbook — prioritized actions for 2026
-
Product and technology: prioritize development of multi-channel, low-loss RF rotary joints and modular hybrid platforms that combine electrical, fluid and optical transfer pathways. Invest in embedded sensor suites for condition-based monitoring and design common mechanical interfaces to reduce variant proliferation.
-
Manufacturing and supply chain: implement material-cost hedging strategies, and qualify dual sources for critical alloys and seals. Lean producibility work and additive manufacturing for complex housings can reduce lead-times and improve customization economics.
-
Quality and market access: secure AS9100/ISO 9001 (and related defense approvals where relevant) as a strategic gate. Certification timelines should be budgeted into project plans for 2026 bids.
-
Commercial models: expand service and retrofit offerings with predictive maintenance contracts. Use telemetry-enabled uptime guarantees and performance-based pricing in high-value verticals such as defense and medical imaging.
-
M&A and partnerships: pursue bolt-on acquisitions for RF expertise, fiber-optic competence, or condition-monitoring software. Strategic partnerships with radar and satcom integrators can accelerate specification wins.
M&A and investment thesis for corporate development teams
With the market showing steady mid-single-digit growth and a moderate concentration profile, the opportunity set for M&A is clear: consolidate horizontally to capture scale benefits in procurement and aftermarket service, or acquire focused specialists that enable entry into premium RF, fiber-optic, or hybrid niches. Buyers should prioritize targets with certified manufacturing processes, strong repair/service franchises, and demonstrable integration of sensors and telemetry.
Deal diligence should include scenario testing around raw material price paths (steel/aluminum) and sensitivity runs on service-margin upside from predictive-maintenance offerings. Integration playbooks must address cross-selling into installed bases and the migration of customers from CAPEX purchases to OPEX-aligned service contracts.
What the full PW Consulting report delivers (and where to go next)
-
Comprehensive market model and downloadable spreadsheets covering historical (2020–2025) and forecast (2026–2032) trajectories at total-market level and across product, application and regional dimensions.
-
Supplier scorecards and a competitive map highlighting capability, certification status, technology differentiators and strategic priorities for the principal vendors.
-
Practical go-to-market playbooks tailored to OEMs, component manufacturers and service providers, including pricing strategies, aftermarket monetization templates, and certification roadmaps.
-
M&A target shortlist and integration checklists calibrated to different buyer types (strategic acquirers vs. financial sponsors).
-
Sensitivity analyses for material-price scenarios, demand shocks across satellite/defense cycles, and adoption curves for IoT-enabled predictive maintenance.
To preserve the utility of this briefing as a strategic preview, we have intentionally omitted the detailed segment and regional allocations from this press summary. Subscribers to the full Worldwide Rotary and RF Rotary Joints Market report receive the granular breakdowns, unit-volume tables, and channel-level forecasts necessary to build investment cases, set 2026 budgets and construct procurement strategies.
Conclusion — where to focus in 2026
Executives planning for 2026 should treat the rotary and RF rotary joints space as a steady-growth, technology-driven market where competitive advantage will accrue to firms that combine certified manufacturing, system-level integration (RF, fluid, optical), and embedded diagnostics that convert one-time sales into recurring revenue. Raw material and certification dynamics impose execution discipline; meanwhile, selective M&A and product-platform strategies create pathways to outpace peers despite a measured industry concentration. PW Consulting’s full report provides the detailed maps required to prioritize investments and execute with confidence.
Contact PW Consulting or visit our report page to obtain the full dataset and supplier playbooks that translate market-level growth into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Rotary and RF Rotary Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Acute Ischemic Stroke Market to Grow at a 7.82% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Acute Ischemic Stroke Market: Strategic Imperatives for 2026 — PW Consulting Preview
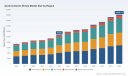
PW Consulting’s latest market research — Worldwide Acute Ischemic Stroke Market (base year 2025, forecast 2026–2032) — delivers the strategic intelligence senior executives, product leaders, and investors need to make high‑impact decisions in 2026. The global market reached an estimated USD 10,750 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.82% through the 2026–2032 forecast window, reaching roughly USD 18,210 Million by 2032. This preview highlights why that growth trajectory matters, what is driving it, and how market participants can convert macro momentum into durable competitive advantage — while preserving the detailed breakouts and proprietary models that are available only in the full report.
Worldwide Acute Ischemic Stroke Market
Why 2026 Is a Pivotal Year
-
Guideline and reimbursement inflection points are aligning with a wave of product approvals and platform launches. The American Heart Association/American Stroke Association’s expanded thrombectomy eligibility (2024) and recent payer updates materially change addressable patient populations and revenue mix.
Worldwide Acute Ischemic Stroke Market -
Regulatory acceleration — including multiple Breakthrough Device designations awarded to new thrombectomy systems in 2025 — shortens time‑to‑market for differentiated technologies and raises the bar for clinical evidence requirements.
Worldwide Acute Ischemic Stroke Market -
Supply chain and trade policy shifts have introduced new cost and sourcing dynamics that will influence 2026 procurement strategies and margin management for OEMs and health systems alike.
What the Report Delivers — Practical, Transaction‑Ready Intelligence
The full PW Consulting report is structured to be operationally useful from day one. It combines market sizing and forecasts with scenario modeling, competitive benchmarking, regulatory and reimbursement pathways, and actionable commercial playbooks. Key deliverables include:
-
Comprehensive market-sizing and trend narratives (historical 2020–2025 and detailed forecasts 2026–2032) with sensitivity analyses across adoption, pricing, and reimbursement scenarios.
-
Technical and clinical segmentation that maps device and drug categories to procedural mix and end‑user channels — enabling prioritization of product investments and go‑to‑market sequencing.
-
Regulatory and reimbursement roadmaps that identify optimal evidence strategies for accelerated approvals and NTAP‑type pathways in major markets.
-
Commercial playbooks: value‑based contracting templates, hospital procurement engagement scripts, and clinical staffing/center of excellence partnership models optimized for 2026 realities.
-
M&A and partnering targets identified through a proprietary scoring model for technology fit, commercial footprint, and regulatory readiness.
-
Regional operational guidance — including logistics, localization, and pricing tactics — tailored to mitigate tariff and sourcing risks while preserving time‑to‑market.
Market Structure and Competitive Dynamics (What You Can Rely On)
The AIS market is characterized by a concentrated competitive set at the top, with a small number of global medtech leaders and a vibrant field of specialized innovators. Measured concentration indicates that leading firms capture a material majority of market value, yet there remains fertile space for niche entrants and faster, evidence‑driven challengers. PW Consulting’s competitive framework evaluates market share, product breadth, technology platforms, clinical evidence, and contracting sophistication — enabling executives to identify where to defend, where to partner, and where to disrupt.
Company‑Level Strategic Readouts
-
Stryker Corporation — A leader on stent‑retriever platforms, Stryker’s portfolio strategy emphasizes integrated systems and iterative device improvements. Recent product introductions expand their neurovascular footprint into adjacent prevention and flow‑diversion indications, supporting cross‑sell opportunities in bundled hospital contracts.
-
Medtronic plc — Medtronic continues to leverage robust long‑term clinical datasets to support its Solitaire family and aspiration platforms. Strong trial results and platform integration reinforce payor conversations and premium positioning with high‑volume centers.
-
Johnson & Johnson (Cerenovus) — With next‑generation revascularization devices and regulatory wins, J&J is positioned to press on device differentiation while pursuing streamlined hospital adoption through training and outcomes partnerships.
-
Penumbra, Inc. — Penumbra’s focus on aspiration systems and high‑speed performance enhancements has earned regulatory clearances that strengthen their competitive story for time‑sensitive procedures and networked stroke systems.
-
Balt USA LLC — A specialized player with differentiated stent retriever offerings, Balt’s regional agility and focused clinical collaborations make it a preferred supplier in select centers of excellence.
-
Terumo Corporation — Terumo’s supply of catheters and guidewires supports their strategy of being the essential component supplier to broader neurovascular platforms, a role that becomes strategically valuable under supply‑chain stress.
-
MicroVention, Inc. — The expansion of its integrated aspiration systems in Europe evidences a strategy that pairs regulatory wins with European commercialization to build a global bridgehead.
-
Rapid Medical — Rapid’s active access platforms represent the type of disruptive niche technology that can alter procedural workflows and create new clinical standards if matched with persuasive outcome data.
Recent Developments That Will Shape 2026 Strategy
-
New product launches and regulatory clearances through 2025 have altered the competitive playing field, shortening windows of exclusivity for existing platforms and raising expectations for next‑generation system performance.
-
Payers are responding to outcomes‑focused evidence: targeted reimbursement updates and NTAP‑type mechanisms have created immediate opportunities for devices that can demonstrate clear, short‑term cost offsets on length of stay and functional outcomes.
-
Trade policy and tariff shifts are elevating the importance of supply‑chain resilience and local content strategies in supplier selection and contract negotiations.
Strategic Imperatives — What Leaders Must Do in 2026
PW Consulting recommends five priority moves for companies and investors seeking to convert market growth into durable returns:
-
Invest in targeted evidence programs. With eligibility windows expanding and payers demanding value, prioritized investments in pragmatic trials and registry partnerships will speed coverage decisions and justify premium pricing.
-
Operationalize reimbursement strategies. Proactively pursue supplemental payment pathways and NTAP‑style mechanisms where available; align commercial teams to capture hospital-level savings that support device adoption.
-
Hedge supply risk through sourcing diversification. Reassess BOM composition and consider nearshoring or dual‑sourcing key components to mitigate tariff exposure and expedite deliveries to high‑volume centers.
-
Adopt a systems play. The next phase of competition is less about single instruments and more about integrated workflows — from access to aspiration to imaging. Partnerships, platform licensing, and modular integration will win long‑term tenders.
-
Pursue focused M&A to fill capability gaps. Small, clinical‑stage tuck‑ins that accelerate time‑to‑market or close gaps in access technology offer superior risk‑adjusted returns versus ground‑up development.
Commercial Tactics — A 90‑Day Implementation Checklist for 2026
-
Map adoption pathways at top 20 stroke centers and align clinical champions to generate single‑site outcome data.
-
Run payer pilots that quantify short‑term cost offsets from reduced LOS and fewer downstream procedures — convert pilots into regional contracting wins.
-
Audit suppliers for tariff exposure and implement contingency plans for components subject to trade actions.
-
Calibrate pricing and bundling strategies to reflect expanded patient eligibility windows and center‑level procedural economics.
-
Prepare regulatory and reimbursement dossiers for targeted accelerated pathways and Breakthrough designation opportunities.
Where PW Consulting Adds Unique Value
Our analysis synthesizes clinical, regulatory, commercial, and financial factors into an executable plan. We combine proprietary forecasting models (base year 2025; forecast 2026–2032) with deal‑ready diligence checklists and hospital procurement playbooks. The report quantifies the macro opportunity and indexes strategic levers by their expected impact on revenue, margin, and time‑to‑adoption — but it intentionally reserves the detailed sub‑segment breakouts and our proprietary scenario matrices for the full report to ensure customers derive maximum commercial advantage.
Next Steps — How to Use This Intelligence
For executive teams planning 2026 budgets, the evidence presented here points to a clear allocation strategy: accelerate evidence generation, lock in reimbursement pathways, stabilize supply chains, and prioritize platform interlocks. Investors should use the competitive readouts and concentration analysis to identify consolidation targets and assess which technology architectures are most likely to scale. Health systems should pilot value‑based procurement approaches that reward devices demonstrating measurable improvements in throughput and outcomes.
PW Consulting’s Worldwide Acute Ischemic Stroke Market report delivers the full datasets, regional forecasts, scenario analyses, and tactical playbooks required to implement these recommendations. To access the proprietary segment detail, methodology, and the complete set of commercial tools, request the full report on our website or contact your PW Consulting account lead for a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Precision Resistors Market to Grow at a 6.45% CAGR Through 2032, Led by Automotive and Industrial Demand
By pmarketresearch, 2026-07-15
Worldwide Precision Resistors Market — Strategic Outlook for 2026: PW Consulting Report Preview
As precision resistors continue to underpin the performance, safety and efficiency of next‑generation electronics, senior executives must make supply, product and investment decisions with granular market intelligence. PW Consulting’s new Worldwide Precision Resistors Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes longitudinal market sizing, supplier benchmarking and scenario planning to support those decisions. The market expanded steadily through the first half of the decade and, under a base-case trajectory, compounds at roughly 6.45% annually — a pace that translates into meaningful scale and strategic inflection points for suppliers, OEMs and investors over 2026–2032.
Worldwide Precision Resistors Market
What this preview delivers — and what it intentionally withholds
-
Deliver: a strategic distillation of the report’s operationally useful findings — market growth drivers, risk vectors to prioritize in 2026, competitor positioning and actionable playbooks for procurement, R&D and M&A.
Worldwide Precision Resistors Market -
Withhold: granular segment tabulations and proprietary tables that reveal detailed regional, type and application shares. This preview follows a “trailer” approach: we demonstrate analytic depth and practical value while directing decision‑makers to the full report for the precise segment-level figures that are essential for transaction work and detailed budgeting.
Worldwide Precision Resistors Market
Market trajectory and strategic implications
PW Consulting’s topline sizing traces the market’s steady recovery and expansion across 2020–2025, driven by embedded electronics growth, electrification in transportation and accelerated demand for high‑reliability components in medical and industrial instrumentation. The analysis projects continued expansion throughout the forecast window to 2032 under a mid‑case growth rate of approximately 6.45% CAGR, reflecting a market that is large enough to support multiple business models — from niche high‑precision specialists to scale-driven commodity players — but also dynamic enough for technology- and regulation‑led disruption.
For 2026 corporate planning, this implies three practical realities:
-
Capacity and capability decisions are time-sensitive. Capital allocations to thin‑film and foil production equipment will take quarters to translate into qualified supply for automotive or aerospace OEMs.
-
Regulatory and materials shocks can reprice products quickly. Margin preservation in 2026 will hinge on procurement strategy and design‑in flexibility.
-
Market share gains are available to firms that combine product differentiation (tighter tolerances, lower TCR, AEC‑Q200 qualification) with operational resilience (dual sourcing, long lead‑time management).
Report contents — practical modules for decision use
The full PW Consulting report is structured to move executives from situational awareness to executable choices. Key modules include:
-
Top‑down and bottom‑up market sizing with scenario overlays: base, accelerated adoption and downside demand shock cases, enabling sensitivity analyses against revenue and EBITDA forecasts.
-
End‑use demand mapping: growth levers across automotive & e‑mobility, industrial instrumentation, telecom, medical and defense — including build‑out timelines and qualification cycles that affect design‑win timing.
-
Supplier and product matrix: independent benchmarking of manufacturing processes (thin film, metal foil, wirewound, thick film), technology roadmaps and qualification statuses to inform sourcing and vertical integration choices.
-
Procurement playbooks: hedging strategies for key alloys, optimized safety‑stock models under extended lead times and recommended contracting terms for 2026 negotiations.
-
Regulatory and trade impact assessment: practical compliance checklists (including RoHS 3 implications), export control scenarios and tariff sensitivity analyses for routing and nearshoring decisions.
-
M&A and partnership blueprints: target screening criteria, valuation sensitivities and post‑deal integration checklists focused on precision resistor capabilities.
-
Financial models and dashboards: downloadable worksheets that allow CFOs and corporate development teams to test capex plans and revenue accretion under multiple market pathways.
Near‑term dynamics executives must prioritize (2024–2026)
The industry environment entering 2026 is characterized by several interlocking pressures that have direct operational consequences:
-
Raw material volatility: alloy inputs used in precision foils experienced notable price moves in 2025. Procurement teams should assume elevated price volatility and evaluate multi‑tier hedging combined with strategic inventory where cost of stock is lower than the cost of lost programs.
-
Regulatory tightening: recent material restrictions require halogen‑free and other RoHS‑3 compliant materials for EU supply lines. Product roadmaps and bill‑of‑materials (BOM) reviews must be accelerated to avoid qualification delays.
-
Trade and export constraints: export control regimes introduced in late‑2024 and tariff measures create non‑trivial destination risk for certain high‑precision components. Short‑term mitigations include localized qualification and third‑country routing for at‑risk customers.
-
Lengthening lead times: precision thin‑film lead times extended materially in late 2025, increasing the value of forward‑booking and long‑term contracts for OEMs that depend on stable supplies.
Competitive landscape — concentrated but open to strategic disruption
The market exhibits moderate concentration: the top three firms account for roughly 38.5% of the market while the top five reach about 52.1%. This structure favors established players with scale advantages in process control and quality systems, while also leaving room for focused specialists to capture premium niches.
From our competitor analysis:
-
Vishay Intertechnology (Malvern, PA): a leading multi‑technology supplier with deep capabilities in thin‑film and foil processes. Recent product introductions reinforce their push into automotive and industrial precision markets.
-
TE Connectivity (Schaffhausen): leverages wirewound and thin‑film strengths to serve high‑stability industrial and military segments; product refreshes emphasize long‑term reliability.
-
Yageo Corporation (New Taipei City): strong in chip resistor form factors and cost‑competitive positioning for telecom and consumer electronics; recent compact array releases target space‑constrained designs.
-
KOA Speer, Susumu, Isabellenhütte and others: each occupies differentiated niches — automotive‑grade current sense, ultra‑low‑TCR foil resistors, and high‑power wirewound solutions — making them attractive targets for customers seeking specialized performance.
-
New product activity is meaningful: manufacturers have announced new thin‑film and high‑stability lines and achieved automotive qualifications in the past 18 months, underscoring the pace of incremental product innovation.
Strategic implications: incumbents should protect core accounts via qualification depth and service guarantees, while challengers can win through vertical specialization, faster qualification cycles and collaboration with Tier‑1 OEMs to lock design wins.
Actionable recommendations for 2026 planning
-
Supply chain: implement a dual‑axis strategy combining strategic long‑term supply agreements for critical alloys with tactical secondary sourcing for commoditized SKUs. Reassess safety stock policies given lead‑time extensions.
-
Product & engineering: prioritize RoHS‑3 compliant BOM redesigns and ramp AEC‑Q200 qualifications for target automotive programs. Embed testability for low‑TCR performance into design cycles to shorten system‑level qualification time.
-
Commercial: segment customers by qualification complexity and lifetime value. Offer integrated qualification services (co‑engineering, accelerated reliability testing) to shorten buy‑in timelines.
-
M&A & partnerships: consider bolt‑on acquisitions to acquire specific process know‑how (e.g., foil slitting, precision laser trimming) rather than broad horizontal consolidation, unless scale is required to serve high‑volume automotive customers.
-
Risk & compliance: establish a cross‑functional export‑controls playbook and revalidate routing options for at‑risk destinations. Use contractual clauses to pass through certain tariff and compliance costs where possible.
How PW Consulting supports 2026 execution
Our practice combines industry expertise with executable tools. Clients that commission the full report and follow‑on advisory support receive:
-
Custom workshops to translate market scenarios into 2026 capex and procurement plans.
-
Supplier due diligence templates and financial models for acquisition screening.
-
Operational playbooks for BOM substitution, qualification timelines and supplier audits.
-
Access to the report’s interactive dashboards and downloadable financial worksheets for board‑level presentations.
Note: the full report contains detailed, proprietary segment breakdowns by region, type and application, along with supplier market shares and pricing matrices that are intentionally not reproduced here. Those tables and the accompanying datasets are essential for transaction‑level diligence, SKU‑level margin work and procurement contracting and can be accessed through PW Consulting’s report portal.
Conclusion — positioning for advantage in 2026
Precision resistors are a classic “enabler” market: relatively small line items at the component level but decisive for product function and system reliability. As the marketplace heads into 2026, companies that combine disciplined capacity planning, compliance‑first engineering and targeted commercial strategies will capture outsized returns. PW Consulting’s Worldwide Precision Resistors Market report provides the roadmap and the modeling tools to convert market forecasts into confident decisions — from sourcing and product development to M&A and pricing. For teams preparing 2026 budgets, the report offers the empirical foundation to allocate capital and manage risk with precision.
To obtain the full dataset, supplier matrices and executable spreadsheets that underpin these conclusions, please refer to the official report page (full access with purchase). PW Consulting stands ready to brief leadership teams on tailored implications and to execute the diagnostic and implementation work streams necessary to translate strategy into results.
For detailed analysis of this topic, please visit the official page: Worldwide Precision Resistors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lemon Juice Concentrates Market Set to Squeeze Growth at a 5.45% CAGR, New Report Reveals
By pmarketresearch, 2026-07-15
Worldwide Lemon Juice Concentrates Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on Worldwide Lemon Juice Concentrates delivers a pragmatic, strategy‑grade lens for procurement, R&D, commercial and corporate development teams preparing plans for 2026. Drawing on a quantitative backbone and on‑the‑ground primary research, the report translates market movements into decision triggers: where to hedge, when to accelerate product bets, and how to allocate capital in a market that is consolidating and repricing simultaneously.
Worldwide Lemon Juice Concentrates Market
Why this study matters for 2026
The lemon juice concentrates market has demonstrated steady expansion through the 2020–2025 window, rising from approximately USD 660 million in 2020 to roughly USD 854 million in 2025. Our baseline projection compounds at a mid‑single‑digit rate (CAGR 5.45%) through the 2026–2032 forecast horizon, with the global market crossing the billion‑dollar threshold during the period. That trajectory is not uniform: it is driven by converging supply‑side constraints, shifting end‑use demand patterns, and regulatory adjustments that alter trade economics and sourcing choices.
Worldwide Lemon Juice Concentrates Market
What the report contains — practical, executable outputs
- Market sizing and 2020–2032 forecasts with scenario variants (base, supply‑shock, and accelerated‑demand) and an integrated sensitivity model for raw‑material and finished‑product pricing.
- Supply‑chain heat maps and a supplier risk index that rank production hubs by weather exposure, harvesting cadence, and logistics friction.
- Commercial playbooks for procurement and category managers: contract templates, price‑hedging frameworks, and recommended sourcing tenures tied to price volatility regimes.
- R&D and innovation briefs outlining viable product adjacencies (e.g., high‑performance emulsions for beverage differentiation) along with go‑to‑market timing and margin mechanics.
- Competitive landscape dossiers on leading processors and ingredient platforms, consolidated into an actionable M&A and partnership tracker.
- Regulatory and food‑safety monitoring checklist, including recent amendments and notifications that materially affect market access and labelling.
- An executive dashboard (Excel model) enabling users to plug in company‑level volumes to simulate revenue and margin outcomes across forecast scenarios.
Market dynamics: three forces shaping 2026 decisions
- Supply tightness and input cost repricing. Southern European and South American crops experienced disruption in the most recent campaigns; industrial quotes and supplier reports point to a step‑up in raw material pricing and tighter availability. Buyers should assume a higher base cost of sourcing in 2026 and plan contracts accordingly.
- Regulatory rebaselining. Trade and antidumping frameworks remain active levers. Notably, recent amendments have preserved reference pricing mechanisms for certain bilateral trade channels, and reciprocal tariff regimes tied to domestic seasons continue to influence commercial windows for imports. These policy variables alter landed cost math for strategic sourcing.
- Product innovation and formulation demand. Beverage formulators and food processors are increasing demand for differentiated citrus ingredients — from emulsified lemon systems to organic, cold‑pressed concentrates — creating premium niches even as industrial demand for standard concentrates remains the backbone of volume.
Competitive landscape — who matters and what they are doing
The market exhibits moderate concentration: the top three players control roughly one‑third of global capacity, while the top five approach half of industry production. This structure creates a balance where scale is important for industrial supply contracts, but mid‑size specialist players can capture value through product differentiation and service‑level flexibility.
Worldwide Lemon Juice Concentrates Market
- Lemonconcentrate SLU (Murcia, Spain). A European specialist focusing on both clear and cloudy concentrates and citrus blends. Recent moves include expanding emulsion product lines aimed at high‑performance beverage applications and active international trade‑show engagement to deepen Middle Eastern partnerships. These actions position the company as a partner of choice for beverage manufacturers seeking application‑ready lemon systems.
- Nielsen Citrus Products Company, Inc. (USA). A North American supplier with deep experience across concentrates, purees and reconstituted products for culinary, bakery and savory applications. Their portfolio and channel relationships make them an attractive cellar‑mate for food manufacturers seeking integrated citrus solutions.
- Citromax SACI (Argentina). The market leader in organic lemon processing, commanding a unique position in certified organic supply chains. For companies prioritizing organic sourcing, Citromax’s scale and certification are differentiators.
- Agrumaria Corleone (Italy), BAOR (Spain), Horti Green Foods (India/Thailand). These regional champions combine product breadth with geography‑specific advantages: Mediterranean sourcing, sustainability narratives, and aseptic processing capabilities for long‑haul export markets.
- Large integrated processors (e.g., Döhler, Citrosuco, Tree Top, SunOpta). These groups supply lemon concentrates as part of broader fruit‑based ingredient suites, offering bundled solutions to global food and beverage customers and acting as consolidation vehicles for buyers seeking multi‑ingredient partners.
Recent developments you cannot ignore
- Product portfolio expansions focused on emulsions and application‑ready lemon systems are accelerating — a clear signal that ingredient innovation is moving from lab to commercial rollout.
- Trade‑show activity and market development in the Middle East and Asia indicate suppliers are reallocating commercial effort to faster‑growing end‑markets and new distribution partnerships.
- Price trajectories in 2025 and early 2026 were upwards across key sourcing regions, with market reports noting significant increases in bulk lemon pricing compared with prior cycles — a dynamic that has recalibrated procurement thresholds and pass‑through strategies.
- Regulatory notices and antidumping agreements continue to influence US import parity and seasonal tariff parity arrangements; food‑safety alerts relating to undeclared preservatives remain relevant for compliance teams.
Strategic implications and recommended actions for 2026
- Procurement: diversify tenor and sourcing mix. Lock in a hybrid of short‑term and multi‑season contracts. Where possible, combine cost‑plus and index‑linked clauses to share volatility with suppliers while maintaining optionality for formulation changes.
- Inventory & logistics: build conditional buffers. Given weather and harvest uncertainty, maintain contingent inventory plans for critical SKUs and secure flexible logistics capacity that allows rapid redeployment between sourcing origins.
- Commercial: monetize product differentiation. Invest in co‑development with high‑performing suppliers for emulsions and organic lines; premiums exist for application‑ready lemon systems that reduce customer reformulation costs.
- Regulatory & compliance: continuous monitoring. Assign ownership for trade‑policy trackers and RASFF/food‑safety alerts to ensure early detection of import and labelling risks; review contract clauses for tariff pass‑through and force‑majeure triggers.
- Portfolio strategy: evaluate bolt‑on M&A. With market concentration moderate, well‑timed acquisitions of regional specialists can secure capability (e.g., aseptic processing, organic certification) and accelerate entry into premium niches.
Operational KPIs to adopt immediately
- Supplier fill‑rate and on‑time delivery variance by quarter
- Raw‑material price delta vs. benchmarked historic average
- Percentage of sales tied to application‑ready versus commodity concentrate
- Average contract tenure by supplier and percent of volumes under multi‑year agreements
- Regulatory incident lead‑time (days) from notification to containment
Why PW Consulting’s analysis is different
Our study pairs a rigorous top‑down market projection (base year 2025) with granular, actionable modules built for corporate users rather than academics. The workbench includes playbooks and an interactive model that sinks quickly into commercial planning cycles, allowing teams to test pricing, sourcing and M&A decisions against three stress scenarios. We surface supplier strategies and certifications, quantify concentration dynamics, and map regulatory levers — all calibrated to inform 2026 planning and capital allocation.
How to use this intelligence
Use the report as a decision‑support tool: stress‑test procurement policies, align R&D pipelines with available ingredient windows, and prioritize commercial pilots around high‑margin, differentiated lemon systems. For C‑suite leaders, the primary use is to convert market visibility into capital allocation: inventory cushions, strategic partnerships, or targeted acquisitions to secure capabilities that matter in the next contraction or acceleration cycle.
For full segmentation details, supplier dossiers, the scenario financial model, and the regulatory tracker — including the appendices that we intentionally omit here to preserve the proprietary value of the research — please consult the report landing page on PW Consulting’s website or contact our industry practice for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Lemon Juice Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Atmospheric Water Generator Market to Soar from USD 3,461.5 Million in 2025 to USD 10,482.33 Million by 2032 at a 17.15% CAGR
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief — Worldwide Atmospheric Water Generator Market (Preview)
As water stress intensifies across climates and industries, atmospheric water generation (AWG) is moving from niche proof-of-concept toward mainstream infrastructure and commercial deployment. PW Consulting’s forthcoming market study — built on a 2025 base year and a 2026–2032 forecast horizon — synthesizes proprietary primary research, manufacturer disclosures, installation case studies and PW’s scenario-driven financial modelling to give executives the forward-looking intelligence they need in 2026. The global AWG market reached an estimated USD 3,461.5 Million in 2025 and is projected to expand at a compound annual growth rate of 17.15% over the forecast period, driving material upside through 2032 under multiple adoption scenarios.
Worldwide Atmospheric Water Generator Market
Why this report matters for 2026 decision-makers
- Investment prioritization: Rapid revenue growth combined with a market structure that shows meaningful concentration among top suppliers (CR3 ≈ 36.4%, CR5 ≈ 51.25%) creates a differentiated opportunity set for late-stage investors, strategic acquirers and private equity. The report translates macro growth into actionable screening criteria for targets and partnerships.
- Procurement and capex planning: For utilities, municipalities and industrial water users, AWG now sits alongside desalination and local treatment as a viable decentralized option. We map payback sensitivities across climate, scale, and energy mix to support 2026 capital allocation decisions and pilot sizing.
- Product & R&D roadmaps: Technology choices — from thermodynamic condensation to desiccant-based systems and solar-hybrid hydropanels — have material implications for uptime, lifecycle cost and certification. The study benchmarks existing architectures and highlights where incremental R&D can create a durable competitive edge.
- Regulatory & policy engagement: Early adopters are already shaping policy: recent national subsidy programs and procurement incentives (notably a policy initiative announced in India in January 2025) materially alter deployment economics. Our policy scenario work helps vendors and governments quantify subsidy leverage and compliance pathways to potable water standards.
- Go-to-market and partnership design: Successful rollouts increasingly depend on local manufacturing, energy integration partners, and after-sales service networks. The report surfaces commercial models proven in early deployments and flags partnership archetypes that accelerate scale.
What PW Consulting’s report delivers
- Transparent market sizing & scenario analysis: A consistent historical series (2020–2025) and forward projections (2026–2032) with a clear statement of assumptions. Our scenarios quantify upside/potential downside under variations in energy cost, humidity trends, and regulatory support.
- Technology performance library: Side-by-side comparisons of condensation-based systems, desiccant solutions and solar-driven hydropanels across metrics that matter to buyers — liters per day per kW, lifecycle operating expense, footprint, and maintenance cadence.
- Unit-economics playbooks: Templates and calculators to model TCO at residential, commercial and industrial scales, allowing procurement teams to stress-test bids and compare AWG to alternatives such as trucked water, boreholes, and small-scale desalination.
- Supply chain & manufacturing mapping: End-to-end upstream and aftermarket supplier maps, including critical components (compressors, evaporator coils, filtration modules), typical lead times and risk nodes for 2026–2028 sourcing strategies.
- Commercial due diligence assets: Company profiles, capability matrices, product roadmaps, and a structured M&A checklist designed for investors evaluating targets in 2026.
- Deployment playbooks and case studies: Practical guides for pilots, site surveys, permitting, certification processes for potable use, and community engagement — drawn from installations and partnerships in education, defense, and municipal pilots.
Competitive landscape — what leaders and challengers reveal about the next wave
The AWG vendor landscape blends established specialists, HVAC-derived industrial players, solar-hybrid innovators and regional OEMs. Competitive positions are shaped by proprietary platforms, channel reach, certifications and strategic partnerships rather than by unit price alone.
Worldwide Atmospheric Water Generator Market
- Watergen Ltd. (Israel): A market reference for packaged systems across residential, commercial, military and vehicle-integrated applications. Watergen’s patented GENius technology and history of strategic partnerships (including vehicle integration initiatives) make it a prime example of how IP and channel alliances drive premium positioning.
- GENAQ Technologies S.L. (Spain): Industrial- and commercial-focused systems leveraging HVAC-derived engineering; positions itself on operational robustness for off-grid and certified outputs — a model attractive to utilities and large industrial buyers.
- Akvo, EcoloBlue, Drinkable Air, Atlantis Solar, Dew Point Manufacturing and others: A diverse group of suppliers offering solutions from low-cost residential units to large-capacity industrial plants. Distinguishing factors include energy integration (solar), filtration/mineralization modules, and local service networks.
- Solar-hydropanel specialists (e.g., SOURCE Global / formerly Zero Mass Water): These firms illustrate a strategic wedge: combining renewable energy and passive moisture harvesting to address off-grid potable needs. Their product-market fit is particularly strong for decentralized rural deployments and built-environment integrations.
- Regional players and OEMs from India, China, South Africa and Canada: Local manufacturers (notably suppliers whose strategies emphasize climatic optimization and cost-effective condensation) are critical for scaling deployments in high-need markets and for meeting local procurement and manufacturing content requirements.
Recent vendor moves and field activity underscore the market’s maturation: scalable product launches in 2024–2025 (consumer and industrial introductions), Aeronero’s Series 2.0 announcement with scalable capacities and IoT monitoring, university installations used for resilience testing in early 2026, and increasing public-private partnerships. These developments foreshadow a shift from pilots to commercial systems in targeted verticals.
Worldwide Atmospheric Water Generator Market
Strategic scenarios and recommended actions for 2026
- For investors: Prioritize targets with differentiated IP, proven field reliability and embedded service revenues. Given the moderate top-end concentration, bolt-on acquisitions of regional manufacturers and service networks can accelerate market penetration.
- For AWG vendors: Invest in certification pathways and performance guarantees that reduce buyer risk; bundle energy services (solar + storage) where grid constraints exist; and develop scalable subscription and O&M models to lock in recurring revenue.
- For industrial and municipal buyers: Start with staged pilots that instrument performance against local climatic variability and energy tariffs. Use our TCO templates to compare AWG against alternative water supply options under conservative humidity assumptions.
- For policy-makers and development agencies: Target incentive design to de-risk initial installations and catalyze local manufacturing capacity. Subsidies and tax incentives — as piloted in certain markets — materially change the ROI calculus and accelerate adoption.
- For energy & infrastructure partners: Position AWG as part of integrated water-energy solutions. Bundling AWG with renewable power procurement and demand-response contracts improves economics and resiliency.
Methodology & what we intentionally withhold (the “trailer” approach)
PW Consulting’s analysis combines primary interviews with manufacturers, buyers and installers, volumetric installation data, and PW’s unit-cost models to produce a consistent historical series (2020–2025) and scenario-based forecasts (2026–2032). To preserve the utility of this executive preview and drive informed commercial engagement, we are intentionally selective in this summary: detailed regional revenue splits, application-level percentages and granular pricing tables — the elements most actionable for procurement and M&A— are reserved for the full report and interactive dashboards available from PW Consulting.
Our published macro outputs include market size by year, growth rates and concentration metrics, while the full study provides the disaggregated tables, vendor scorecards, component-level BOMs and downloadable financial models that transaction teams and product leaders use to execute in 2026.
Closing — the strategic clock is ticking
AWG is transitioning from experimental deployments to commercially material projects. With a strong projected growth trajectory through 2032, the competitive landscape will reward organizations that move decisively in 2026: those that validate their assumptions with field pilots, lock in energy partnerships, secure certifications and structure recurring revenue will capture disproportionate value. PW Consulting’s full Worldwide Atmospheric Water Generator Market report is designed to be an execution tool — not just a market primer — and contains the actionable datasets, playbooks and vendor diligence assets recommended for any organization preparing to make capital or strategic commitments in 2026. Visit PW Consulting’s research page to access the full report, interactive models, and tailored advisory engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Atmospheric Water Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Insulinoma Market to Expand at a 5.75% CAGR Through 2032, Unveiling New Growth Opportunities
By pmarketresearch, 2026-07-15
Worldwide Insulinoma Market — 2026 Strategic Preview
PW Consulting’s new market study, Worldwide Insulinoma Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers a compact but rigorous strategic playbook for companies planning to make material decisions in 2026. At the macro level, the market has expanded from roughly USD 126 million in 2020 to about USD 167 million in 2025, and our model projects continued growth through the forecast window with a steady compound annual growth rate (CAGR) of 5.75% (2026–2032) to reach an estimated market size north of USD 240 million by 2032. Those topline dynamics are the backdrop for a highly focused competitive set, a small and clinically complex patient population, and an evolving regulatory posture that together determine near-term commercial opportunity and clinical development strategy.
Worldwide Insulinoma Market
Why this report matters for 2026 decisions
-
Precision of timing: Several pivotal clinical programs and regulatory alignments now converge on a 2026 inflection point. Companies need a tight timeline-driven plan that aligns R&D, regulatory engagement, and commercial preparation in the same fiscal year.
Worldwide Insulinoma Market -
Small-population economics: Insulinoma and tumor-mediated hyperinsulinism sit within rare-disease economics. Successful value capture depends on integrating clinical differentiation with reimbursement strategy and selective commercial footprint planning.
Worldwide Insulinoma Market -
Concentration with room to move: Market concentration metrics indicate a mid-level aggregated share among the top competitors—enough scale for incumbents to defend position, yet clear openings exist for breakthrough therapies and partnerships that demonstrate meaningful clinical benefit.
Market dynamics and clinical context
The insulinoma therapeutic landscape remains anchored by surgical resection for localized disease, with medical therapies reserved for inoperable or malignant presentations. First-line medical management typically includes agents such as diazoxide, with somatostatin analogs and a range of off-label approaches used when hypoglycemia proves refractory. Epidemiology remains constrained—incidence is low, and a minority of cases behave aggressively or metastasize—creating both a challenge and an opportunity for sponsors pursuing novel modalities.
Recent regulatory and clinical developments have crystallized the pathway for anti-insulin targeted therapies. A notable example is the advancement of ersodetug, an anti-insulin monoclonal antibody developed by Rezolute, Inc., which is being evaluated in tumor-mediated hyperinsulinism including malignant insulinoma. Rezolute announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial design and expects topline data in H2 2026, with a parallel congenital hyperinsulinism program providing potential confirmatory evidence. These events underline a larger trend: regulators are willing to accept innovative, small-cohort designs accompanied by strong confirmatory linkage across related indications when unmet need and plausible mechanism of action are present.
What PW Consulting’s report provides (practical, action-focused)
-
Proprietary market model and scenario engine — granular, auditable forecasts with best/base/worst-case scenarios, sensitivity levers (pricing, uptake, addressable population), and interactive outputs to test commercial assumptions under multiple timelines.
-
Clinical-pathway maps and patient flow analysis — step-by-step depiction of diagnostic delays, referral patterns, surgical candidacy criteria, and the subset of patients likely to require chronic medical management.
-
Regulatory and trial design playbook — benchmarks and decision trees for accelerated pathways, single-arm pivotal strategies, surrogate endpoints, confirmatory evidence planning, and engagement templates for regulators and HTA bodies.
-
Commercial readiness checklist — go-to-market sequencing, field-force sizing guidance, center-of-excellence targeting, and distribution models tuned to low-volume, high-value therapies.
-
Reimbursement and value dossier framework — payer segmentation, expected evidence thresholds for coverage, pricing scenario planning, and contracting templates suitable for orphan and ultra-orphan assets.
-
Competitive intelligence dossiers — profiles of active companies, pipeline positioning, patent landscapes, and M&A/partnership heatmaps to help prioritize outreach and licensing opportunities.
-
Manufacturing and supply-chain risk matrix — demand-scaling scenarios, COGS sensitivities, and mitigation strategies for gene/biologic modalities common among next-generation insulinoma candidates.
Competitive landscape: actionable takeaways
The report aggregates competitor positioning into pragmatic categories—incumbent procedural leaders, mid-size specialty developers, and early-stage biologic innovators. While we do not publish every sub-segment table in this announcement, the study’s concentration metrics indicate that the top three firms hold a substantial, but not overwhelming, portion of market share, and the top five capture a clear majority. This concentration profile implies two strategic routes:
-
For established players: defend with clinical differentiation, broaden indications where feasible, and optimize center-level partnerships to maintain utilization of surgical and adjunctive procedures.
-
For new entrants/biotechs: pursue regulatory strategies that leverage small-cohort pivotal designs, validate value through clear downstream economic models, and seek strategic alliances for commercialization or distribution.
Rezolute’s recent regulatory alignment illustrates the profile of a development program that can materially shift the competitive map. For sponsors evaluating investment or partnership with similar candidates, our report models recruitment timelines, expected evidentiary gates for regulatory and HTA acceptance, and commercial scenarios tied to different labeling outcomes.
How 2026 corporate decisions should be informed by this study
-
R&D portfolio prioritization: Use the report’s go/no-go thresholds to allocate late-stage capital toward programs with demonstrable clinical differentiation, realistic trial recruitment plans, and clear regulatory pathways.
-
Regulatory engagement: Prioritize early and frequent dialogues with regulators to validate single-arm or hybrid trial designs, define acceptable confirmatory strategies across related indications, and reduce approval and launch risk.
-
Commercial sizing and sequencing: Prepare lean, high-impact launch plans that focus on centers of excellence and high-volume referral hubs; defer broad generalist field builds until payer coverage is secure.
-
Partnership and M&A strategy: Target bolt-on acquisitions that provide clinical trial acceleration, complementary modalities (e.g., diagnostics), or established specialty-clinic networks to compress time-to-revenue.
-
Payer strategy: Build a reimbursement dossier early—real-world evidence, economic modeling for avoided hospitalizations, and contracting approaches for rare-disease premiums are essential to secure access.
Practical tools and deliverables in the full report
Decision-makers will find immediately actionable materials: downloadable forecast workbooks, clinical trial recruitment heatmaps, payer dossier templates, a prioritized partner shortlist, and a six-quarter tactical launch plan. Our scenario engine allows executives to simulate the impact of alternative assumptions—e.g., faster-than-expected adoption versus delayed reimbursement—on net present value and break-even timelines.
Case study — resolving small-cohort regulatory risk
Rezolute’s pathway shows a pragmatic route to market in this therapeutic area: a streamlined Phase 3 single-arm trial aligned with the FDA, small patient cohorts sized to the condition’s rarity, and the strategic use of cross-indication confirmatory evidence. For companies facing similar junctures, the report lays out a template that aligns trial design, biomarker strategy, and commercial readiness so that regulatory risk and launch timing are jointly optimized rather than managed in isolation.
What the preview omits (and why you should read the full report)
In line with our “prequel” approach, this announcement intentionally omits granular regional and treatment-type split tables, detailed pricing scenarios tied to specific jurisdictions, and the full city-by-city center-of-excellence map. These are core assets within the full study because they are most valuable when tailored to an organization’s commercial, clinical, and regulatory strategy. Access to the full report unlocks the precise tables, interactive dashboards, and the downloadable financial model you will need to convert insight into action.
Final recommendation
For executives allocating capital or shaping clinical development strategies in 2026, a focused, evidence-driven approach is essential. The insulinoma market is expanding steadily, driven by better diagnostics, emergent targeted biologics, and regulatory flexibility for rare-disease programs. But success will hinge on linking clinical differentiation with pragmatic commercialization and payer strategies. PW Consulting’s Worldwide Insulinoma Market study is designed to be the single vetted source that helps you align those elements into a coherent 12–24 month execution plan.
To obtain the complete dataset, segmented forecasts, and the interactive scenario model, please consult the full report on our website. The detailed tables and tools are the executional instruments that will convert the strategic direction outlined here into measurable results.
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Glycopeptide Antibiotics Market to Expand at a 4.6% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Glycopeptide Antibiotics Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide glycopeptide antibiotics market presents a forward-looking framework tailored for executive teams preparing their 2026 strategic plans. Anchored to a 2025 base year and built on a 2026–2032 forecast horizon with an expected compound annual growth rate (CAGR) of 4.6%, the report synthesizes macro trends, regulatory inflection points, supply‑chain stressors, and competitive positioning into a pragmatic playbook for pharma, generics manufacturers, API suppliers, and hospital procurement leaders.
Worldwide Glycopeptide Antibiotics Market
Why this analysis matters in 2026
-
Market momentum: The glycopeptide category has demonstrated steady recovery and expansion after pandemic-era volatility. Our baseline modeling — reflecting a 2025 market base and a 4.6% forecast CAGR — informs near-term portfolio prioritization and capital allocation decisions.
Worldwide Glycopeptide Antibiotics Market -
Regulatory and clinical drivers: Recent regulatory updates to antimicrobial susceptibility testing and evolving clinical guidance are reshaping relative value among glycopeptide agents and their competitors. These changes alter comparative effectiveness perceptions that payers and hospital formularies will use in 2026.
Worldwide Glycopeptide Antibiotics Market -
Supply‑chain fragility and input inflation: API and finished-dosage manufacturing economics have shifted materially — industry data indicate meaningful cost inflation for antibiotic APIs between 2022–2025. For 2026, companies must reconcile margin targets against higher input costs and concentrated sourcing footprints.
-
Commercial and reimbursement inflection: Reimbursement pathways for newer lipoglycopeptides and innovations in outpatient administration are creating profitable routings outside traditional inpatient channels, changing commercial models for the category.
Teaser of key findings
-
Growth trajectory: The category is on a moderate, stable growth path driven by persistent demand for effective MRSA and other Gram‑positive therapies, investment in novel formulations, and incremental label and reimbursement wins.
-
Consolidation posture: Market concentration is non-trivial — the top firms hold a material share of market sales — creating distinct advantages for scale players but leaving tactical openings for focused entrants with differentiated formulations or supply certainty.
-
Formulation-led differentiation: Novel ready‑to‑use and lipoglycopeptide formulations (offering longer dosing intervals and outpatient administration) are changing care site economics and procurement decisions.
-
Supply risk premium: Heavy geographic concentration of antibiotic API production creates a supply‑risk premium that is already reflected in procurement lead times and pricing negotiations.
Competitive landscape — what executives need to weigh
Our proprietary competitive analysis profiles the leading brand, generic, and API suppliers shaping category dynamics. The field comprises global innovators with branded lipoglycopeptides, multinational generics and injectables suppliers, and specialist API manufacturers. PW Consulting’s assessment highlights capability clusters rather than raw share tables to inform strategic choices:
-
Pfizer Inc. — As the owner of a marketed lipoglycopeptide indicated for acute bacterial skin and skin structure infections, Pfizer’s value proposition centers on differentiated dosing profiles and a branded clinical narrative that supports outpatient use. Their commercial muscle and payer engagement remain critical benchmarks for premium positioning.
-
Hikma Pharmaceuticals — A notable recent development is Hikma’s market entry with a ready‑to‑infuse vancomycin formulation approved in 2025. That approval alters hospital pharmacy workflows by simplifying IV preparation, reducing administration risk, and potentially shortening time-to-dose — attributes hospitals value highly in procurement decisions.
-
ANI Pharmaceuticals — With oral vancomycin assets focused on C. difficile, ANI occupies a specialized niche that intersects inpatient/outpatient transitions and stewardship considerations. Capsule formulations remain strategically important for outpatient management of C. difficile‑associated disease.
-
Fresenius Kabi — As a major supplier of generics and injectable formulations to hospitals, Fresenius operates at the intersection of scale manufacturing and hospital channel penetration. Their Kabi division’s injectable capabilities provide resilience where supply continuity is a hospital procurement priority.
-
Xellia, Aurobindo, Zhejiang Hisun, Viatris/Mylan — These firms represent the API and generic supply backbone. Their roles in providing vancomycin APIs and finished dosage forms create levers for cost, lead‑time, and quality. Securing partnerships or dual‑sourcing agreements with these suppliers is often a pragmatic mitigation against upstream shocks.
Strategic implication: companies without vertical integration or validated alternate sources may find themselves negotiating from a position of weakness in 2026. Conversely, manufacturers that can couple differentiated clinical assets with supply reliability will win formulary and contract concessions.
Industry context and dynamics shaping 2026 decisions
-
Regulatory updates: Advances in antimicrobial susceptibility testing and revised breakpoints for certain agents have downstream implications for formulary placement and clinical decision support tools. Companies must maintain active regulatory surveillance and update labels, dossiers, and hospital education programs accordingly.
-
API economics: A multi‑year rise in API production costs has changed unit economics; pricing strategies must be revisited and manufacturing footprints reassessed to protect margin while ensuring availability.
-
Geopolitical sourcing concentration: High import reliance from a limited set of geographies has prompted purchasers to request supplier mapping and continuity plans — an increasingly standard RFP requirement for 2026 contracting cycles.
-
Reimbursement mechanics: Specific reimbursement pathways for lipoglycopeptides in outpatient and hospital‑outpatient settings enhance their commercial case, but they also increase payer scrutiny of cost‑effectiveness and real‑world outcomes.
Actionable playbook for 2026
-
De‑risk supply: Implement dual‑sourcing mandates for critical APIs, secure long‑lead raw materials via forward contracts, and invest in near‑term inventory buffers tied to scenario triggers in the report.
-
Prioritize formulation advantages: Accelerate development or acquisition of ready‑to‑use and long‑acting formulations that reduce hospitalization days or enable outpatient infusion — these attributes command premium access and foster payor support.
-
Revisit pricing & contracting: Build tiered contracting that reflects supply reliability, outcome-based KPIs, and shared savings for reducing inpatient days or readmissions tied to specific glycopeptide therapies.
-
Engage payers earlier: Assemble pragmatic value dossiers that demonstrate real‑world effectiveness, stewardship outcomes, and site‑of‑care economics, especially for lipoglycopeptides positioned for outpatient administration.
-
Explore vertical plays: For mid‑sized manufacturers, selective upstream investment in API capacity or partnership agreements with established API houses provides negotiating leverage and margin protection.
-
Targeted M&A and alliances: Identify bolt‑on targets that fill portfolio gaps (e.g., outpatient formulations, sterile injectables, or API capacity) and accelerate time‑to‑market compared with greenfield projects.
-
Operationalize stewardship: Work with hospital systems to co‑design stewardship pathways that position glycopeptides appropriately, reducing inappropriate use while preserving access where clinically indicated.
Scenario planning — thresholds that should trigger action
PW Consulting’s report includes scenario models rooted in the 4.6% CAGR baseline, plus an upside pathway driven by rapid outpatient adoption of lipoglycopeptides and a downside path influenced by extended API disruptions or accelerated generic erosion. For 2026, recommended trigger events include sustained API lead‑time extension beyond a contractual threshold, material payer denials for outpatient coding, or a competitor achieving broad formulary replacement via a novel formulation — each of which should prompt tactical pivots identified in the playbook.
What’s in the full report (select contents)
-
Detailed market forecasts through 2032 with sensitivity bands and scenario narratives.
-
Comprehensive competitive profiles, manufacturing maps, and supply‑chain exposure matrices.
-
Regulatory and reimbursement matrix aligned to likely 2026 decision points.
-
Go‑to‑market playbooks for branded and generic strategies, including hospital contracting templates and payer engagement scripts.
-
Primary interview insights and proprietary supplier scoring methodologies.
-
Data annex with historical series and modeling assumptions (note: the report intentionally withholds highly granular regional and application split figures in this executive summary to protect proprietary analysis — full segmentation detail is available in the subscriber package).
PW Consulting’s Worldwide Glycopeptide Antibiotics Market report combines quantitative forecasting, on‑the‑ground supplier intelligence, and executable strategic guidance to support capital allocation, M&A screening, and commercial planning for 2026. For teams facing margin compression, supply uncertainty, or a need to pivot commercial models, this study provides a concise, decision‑grade foundation.
To access the full dataset, segmentation tables, and tailored advisory options, visit PW Consulting’s market research portal and request the complete study and executive briefing tailored to your organization’s role in the glycopeptide value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Glycopeptide Antibiotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com