

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reveals Worldwide Rotary & RF Rotary Joints Market to Hit USD 985.28 Million in 2025, Forecasted to Grow at a 5.1% CAGR Through 2032

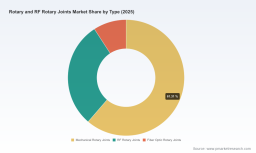
Worldwide Rotary and RF Rotary Joints Market — Strategic Outlook for 2026: PW Consulting Report Highlights
PW Consulting’s new market brief on Worldwide Rotary and RF Rotary Joints synthesizes five years of historical performance and a forward-looking forecast to 2032, delivering the strategic intelligence that executives and investors need to act in 2026. The global market is estimated at USD 985.3 Million in 2025, rising from approximately USD 785.4 Million in 2020, and is projected to reach roughly USD 1,395.7 Million by 2032 — an implied compound annual growth rate (CAGR) of 5.1% across the 2026–2032 forecast window. This briefing highlights the decision-grade implications of that trajectory while deliberately preserving the full granularity of segment and regional splits for subscribers of the full report.
Worldwide Rotary and RF Rotary Joints Market
Why this report matters for 2026 decision-makers
-
Actionable market sizing and pacing. The 5.1% mid-term CAGR signals steady, profitable expansion rather than hypergrowth — a profile that favors disciplined capital allocation over speculative scale-up. Executives weighing capacity investments, product launches, or M&A need this pacing to prioritize near-term spend versus multi-year platform builds.
Worldwide Rotary and RF Rotary Joints Market -
Signal-to-noise separation. Our analysis consolidates raw market trends, supplier moves, materials dynamics, and regulatory drivers into an operational roadmap. We convert broad macro indicators (market size, concentration indices, and growth drivers) into practical choices for R&D, manufacturing, commercial and corporate development teams.
Worldwide Rotary and RF Rotary Joints Market -
Trailer principle: we present definitive strategic insight here while preserving the report’s proprietary segment-level forecasts, regional breakdowns and supplier scorecards to motivate full report access — the place to obtain the detailed allocation and opportunity maps required for execution.
Market dynamics shaping 2026 strategies
-
Technology convergence and premiumization. Demand is migrating toward compact, high-frequency, multi-channel RF rotary joints, and hybrid solutions combining electrical, optical and fluid transfer capabilities. Drivers include expanded satellite communications, phased-array radar deployment, and growth in medical imaging. These forces raise the technical bar and create revenue upside for suppliers that can deliver high-channel-density, low-loss, environmentally qualified products.
-
Service and aftermarket economics. As installed bases grow, lifecycle service, spares, and retrofit opportunities are material contributors to margin. Field diagnostics and predictive maintenance add a recurring-revenue dimension to historically product-centric business models.
-
Materials and manufacturing cost signals. Primary structural alloys matter: steel cost cycles are moderating heading into 2026, while aluminum averaged near USD 2,945/t in early-2026 conditions. These inputs influence design choices (lightweight vs. heavy-duty), yield expectations, and hedging policies for manufacturers targeting aerospace and defense segments where weight and reliability tradeoffs are paramount.
-
Standards and certification pressure. Suppliers targeting space, defense and critical aviation markets maintain AS9100 and ISO 9001 certifications as a baseline. Certification is not a checkbox; it’s a market-access cost that affects quoting, lead-times, and partnership eligibility.
-
Digital enablement. RF rotary joints are increasingly embedded with IoT-based condition monitoring sensors to enable predictive maintenance, reduce unscheduled downtime, and create service bundling opportunities. Firms that integrate robust sensing, telemetry and analytics into product roadmaps will secure higher lifetime value per unit.
Competitive landscape: what leaders are doing
The market is neither hyper-consolidated nor atomized: the top three vendors collectively account for a meaningful minority share, and the top five remain substantially below a dominant concentration threshold. That structure creates room for both scale plays and focused specialists. Illustrative strategic postures among leading firms include:
-
Deublin Company (United States): continuing to leverage breadth and scale in industrial rotary unions, Deublin’s trade show presence and portfolio expansions reflect a push into automation and semiconductor segments. Their recent acquisition activity reinforces a buy-and-integrate approach to expand capability sets.
-
Moog Inc. (United States): advances like integrated slip ring/rotary union combinations for collaborative robots showcase a product-led play to capture emergent automation applications. Lightweight hybrid devices for cobots and aerospace remain a strategic focus.
-
Spinner GmbH (Germany) and other RF specialists: firms concentrating on high-performance RF and hybrid rotary joints are competing on electrical performance, environmental robustness and integration into complex radar and satcom systems.
-
Diamond Antenna and Microwave Corporation (United States): with AS9100/ISO 9001 capability updates, the company exemplifies a quality-first strategy to win defense, space and radar contracts where certification and repair capability are competitive differentiators.
-
Regional and emerging suppliers (China, Europe): manufacturers with integrated slip ring and fiber-optic competencies are targeting automation and robotics markets with cost-competitive solutions. Their playbooks emphasize modular design and short lead-times.
Recent vendor moves illustrate these themes: participation at major automation trade shows, product launches for hybrid slip ring/rotary union devices, strategic acquisitions to broaden solution stacks, and certification renewals that sustain access to regulated end markets. These signals indicate a competitive environment where technology integration and service capability are as important as volume manufacturing.
Operational playbook — prioritized actions for 2026
-
Product and technology: prioritize development of multi-channel, low-loss RF rotary joints and modular hybrid platforms that combine electrical, fluid and optical transfer pathways. Invest in embedded sensor suites for condition-based monitoring and design common mechanical interfaces to reduce variant proliferation.
-
Manufacturing and supply chain: implement material-cost hedging strategies, and qualify dual sources for critical alloys and seals. Lean producibility work and additive manufacturing for complex housings can reduce lead-times and improve customization economics.
-
Quality and market access: secure AS9100/ISO 9001 (and related defense approvals where relevant) as a strategic gate. Certification timelines should be budgeted into project plans for 2026 bids.
-
Commercial models: expand service and retrofit offerings with predictive maintenance contracts. Use telemetry-enabled uptime guarantees and performance-based pricing in high-value verticals such as defense and medical imaging.
-
M&A and partnerships: pursue bolt-on acquisitions for RF expertise, fiber-optic competence, or condition-monitoring software. Strategic partnerships with radar and satcom integrators can accelerate specification wins.
M&A and investment thesis for corporate development teams
With the market showing steady mid-single-digit growth and a moderate concentration profile, the opportunity set for M&A is clear: consolidate horizontally to capture scale benefits in procurement and aftermarket service, or acquire focused specialists that enable entry into premium RF, fiber-optic, or hybrid niches. Buyers should prioritize targets with certified manufacturing processes, strong repair/service franchises, and demonstrable integration of sensors and telemetry.
Deal diligence should include scenario testing around raw material price paths (steel/aluminum) and sensitivity runs on service-margin upside from predictive-maintenance offerings. Integration playbooks must address cross-selling into installed bases and the migration of customers from CAPEX purchases to OPEX-aligned service contracts.
What the full PW Consulting report delivers (and where to go next)
-
Comprehensive market model and downloadable spreadsheets covering historical (2020–2025) and forecast (2026–2032) trajectories at total-market level and across product, application and regional dimensions.
-
Supplier scorecards and a competitive map highlighting capability, certification status, technology differentiators and strategic priorities for the principal vendors.
-
Practical go-to-market playbooks tailored to OEMs, component manufacturers and service providers, including pricing strategies, aftermarket monetization templates, and certification roadmaps.
-
M&A target shortlist and integration checklists calibrated to different buyer types (strategic acquirers vs. financial sponsors).
-
Sensitivity analyses for material-price scenarios, demand shocks across satellite/defense cycles, and adoption curves for IoT-enabled predictive maintenance.
To preserve the utility of this briefing as a strategic preview, we have intentionally omitted the detailed segment and regional allocations from this press summary. Subscribers to the full Worldwide Rotary and RF Rotary Joints Market report receive the granular breakdowns, unit-volume tables, and channel-level forecasts necessary to build investment cases, set 2026 budgets and construct procurement strategies.
Conclusion — where to focus in 2026
Executives planning for 2026 should treat the rotary and RF rotary joints space as a steady-growth, technology-driven market where competitive advantage will accrue to firms that combine certified manufacturing, system-level integration (RF, fluid, optical), and embedded diagnostics that convert one-time sales into recurring revenue. Raw material and certification dynamics impose execution discipline; meanwhile, selective M&A and product-platform strategies create pathways to outpace peers despite a measured industry concentration. PW Consulting’s full report provides the detailed maps required to prioritize investments and execute with confidence.
Contact PW Consulting or visit our report page to obtain the full dataset and supplier playbooks that translate market-level growth into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Rotary and RF Rotary Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com