

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Acute Ischemic Stroke Market to Grow at a 7.82% CAGR Through 2032

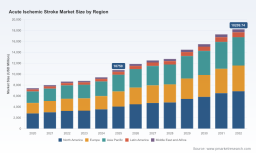
Worldwide Acute Ischemic Stroke Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market research — Worldwide Acute Ischemic Stroke Market (base year 2025, forecast 2026–2032) — delivers the strategic intelligence senior executives, product leaders, and investors need to make high‑impact decisions in 2026. The global market reached an estimated USD 10,750 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.82% through the 2026–2032 forecast window, reaching roughly USD 18,210 Million by 2032. This preview highlights why that growth trajectory matters, what is driving it, and how market participants can convert macro momentum into durable competitive advantage — while preserving the detailed breakouts and proprietary models that are available only in the full report.
Worldwide Acute Ischemic Stroke Market
Why 2026 Is a Pivotal Year
-
Guideline and reimbursement inflection points are aligning with a wave of product approvals and platform launches. The American Heart Association/American Stroke Association’s expanded thrombectomy eligibility (2024) and recent payer updates materially change addressable patient populations and revenue mix.
Worldwide Acute Ischemic Stroke Market -
Regulatory acceleration — including multiple Breakthrough Device designations awarded to new thrombectomy systems in 2025 — shortens time‑to‑market for differentiated technologies and raises the bar for clinical evidence requirements.
Worldwide Acute Ischemic Stroke Market -
Supply chain and trade policy shifts have introduced new cost and sourcing dynamics that will influence 2026 procurement strategies and margin management for OEMs and health systems alike.
What the Report Delivers — Practical, Transaction‑Ready Intelligence
The full PW Consulting report is structured to be operationally useful from day one. It combines market sizing and forecasts with scenario modeling, competitive benchmarking, regulatory and reimbursement pathways, and actionable commercial playbooks. Key deliverables include:
-
Comprehensive market-sizing and trend narratives (historical 2020–2025 and detailed forecasts 2026–2032) with sensitivity analyses across adoption, pricing, and reimbursement scenarios.
-
Technical and clinical segmentation that maps device and drug categories to procedural mix and end‑user channels — enabling prioritization of product investments and go‑to‑market sequencing.
-
Regulatory and reimbursement roadmaps that identify optimal evidence strategies for accelerated approvals and NTAP‑type pathways in major markets.
-
Commercial playbooks: value‑based contracting templates, hospital procurement engagement scripts, and clinical staffing/center of excellence partnership models optimized for 2026 realities.
-
M&A and partnering targets identified through a proprietary scoring model for technology fit, commercial footprint, and regulatory readiness.
-
Regional operational guidance — including logistics, localization, and pricing tactics — tailored to mitigate tariff and sourcing risks while preserving time‑to‑market.
Market Structure and Competitive Dynamics (What You Can Rely On)
The AIS market is characterized by a concentrated competitive set at the top, with a small number of global medtech leaders and a vibrant field of specialized innovators. Measured concentration indicates that leading firms capture a material majority of market value, yet there remains fertile space for niche entrants and faster, evidence‑driven challengers. PW Consulting’s competitive framework evaluates market share, product breadth, technology platforms, clinical evidence, and contracting sophistication — enabling executives to identify where to defend, where to partner, and where to disrupt.
Company‑Level Strategic Readouts
-
Stryker Corporation — A leader on stent‑retriever platforms, Stryker’s portfolio strategy emphasizes integrated systems and iterative device improvements. Recent product introductions expand their neurovascular footprint into adjacent prevention and flow‑diversion indications, supporting cross‑sell opportunities in bundled hospital contracts.
-
Medtronic plc — Medtronic continues to leverage robust long‑term clinical datasets to support its Solitaire family and aspiration platforms. Strong trial results and platform integration reinforce payor conversations and premium positioning with high‑volume centers.
-
Johnson & Johnson (Cerenovus) — With next‑generation revascularization devices and regulatory wins, J&J is positioned to press on device differentiation while pursuing streamlined hospital adoption through training and outcomes partnerships.
-
Penumbra, Inc. — Penumbra’s focus on aspiration systems and high‑speed performance enhancements has earned regulatory clearances that strengthen their competitive story for time‑sensitive procedures and networked stroke systems.
-
Balt USA LLC — A specialized player with differentiated stent retriever offerings, Balt’s regional agility and focused clinical collaborations make it a preferred supplier in select centers of excellence.
-
Terumo Corporation — Terumo’s supply of catheters and guidewires supports their strategy of being the essential component supplier to broader neurovascular platforms, a role that becomes strategically valuable under supply‑chain stress.
-
MicroVention, Inc. — The expansion of its integrated aspiration systems in Europe evidences a strategy that pairs regulatory wins with European commercialization to build a global bridgehead.
-
Rapid Medical — Rapid’s active access platforms represent the type of disruptive niche technology that can alter procedural workflows and create new clinical standards if matched with persuasive outcome data.
Recent Developments That Will Shape 2026 Strategy
-
New product launches and regulatory clearances through 2025 have altered the competitive playing field, shortening windows of exclusivity for existing platforms and raising expectations for next‑generation system performance.
-
Payers are responding to outcomes‑focused evidence: targeted reimbursement updates and NTAP‑type mechanisms have created immediate opportunities for devices that can demonstrate clear, short‑term cost offsets on length of stay and functional outcomes.
-
Trade policy and tariff shifts are elevating the importance of supply‑chain resilience and local content strategies in supplier selection and contract negotiations.
Strategic Imperatives — What Leaders Must Do in 2026
PW Consulting recommends five priority moves for companies and investors seeking to convert market growth into durable returns:
-
Invest in targeted evidence programs. With eligibility windows expanding and payers demanding value, prioritized investments in pragmatic trials and registry partnerships will speed coverage decisions and justify premium pricing.
-
Operationalize reimbursement strategies. Proactively pursue supplemental payment pathways and NTAP‑style mechanisms where available; align commercial teams to capture hospital-level savings that support device adoption.
-
Hedge supply risk through sourcing diversification. Reassess BOM composition and consider nearshoring or dual‑sourcing key components to mitigate tariff exposure and expedite deliveries to high‑volume centers.
-
Adopt a systems play. The next phase of competition is less about single instruments and more about integrated workflows — from access to aspiration to imaging. Partnerships, platform licensing, and modular integration will win long‑term tenders.
-
Pursue focused M&A to fill capability gaps. Small, clinical‑stage tuck‑ins that accelerate time‑to‑market or close gaps in access technology offer superior risk‑adjusted returns versus ground‑up development.
Commercial Tactics — A 90‑Day Implementation Checklist for 2026
-
Map adoption pathways at top 20 stroke centers and align clinical champions to generate single‑site outcome data.
-
Run payer pilots that quantify short‑term cost offsets from reduced LOS and fewer downstream procedures — convert pilots into regional contracting wins.
-
Audit suppliers for tariff exposure and implement contingency plans for components subject to trade actions.
-
Calibrate pricing and bundling strategies to reflect expanded patient eligibility windows and center‑level procedural economics.
-
Prepare regulatory and reimbursement dossiers for targeted accelerated pathways and Breakthrough designation opportunities.
Where PW Consulting Adds Unique Value
Our analysis synthesizes clinical, regulatory, commercial, and financial factors into an executable plan. We combine proprietary forecasting models (base year 2025; forecast 2026–2032) with deal‑ready diligence checklists and hospital procurement playbooks. The report quantifies the macro opportunity and indexes strategic levers by their expected impact on revenue, margin, and time‑to‑adoption — but it intentionally reserves the detailed sub‑segment breakouts and our proprietary scenario matrices for the full report to ensure customers derive maximum commercial advantage.
Next Steps — How to Use This Intelligence
For executive teams planning 2026 budgets, the evidence presented here points to a clear allocation strategy: accelerate evidence generation, lock in reimbursement pathways, stabilize supply chains, and prioritize platform interlocks. Investors should use the competitive readouts and concentration analysis to identify consolidation targets and assess which technology architectures are most likely to scale. Health systems should pilot value‑based procurement approaches that reward devices demonstrating measurable improvements in throughput and outcomes.
PW Consulting’s Worldwide Acute Ischemic Stroke Market report delivers the full datasets, regional forecasts, scenario analyses, and tactical playbooks required to implement these recommendations. To access the proprietary segment detail, methodology, and the complete set of commercial tools, request the full report on our website or contact your PW Consulting account lead for a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com