

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Glycopeptide Antibiotics Market to Expand at a 4.6% CAGR Through 2032

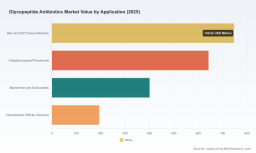
Worldwide Glycopeptide Antibiotics Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide glycopeptide antibiotics market presents a forward-looking framework tailored for executive teams preparing their 2026 strategic plans. Anchored to a 2025 base year and built on a 2026–2032 forecast horizon with an expected compound annual growth rate (CAGR) of 4.6%, the report synthesizes macro trends, regulatory inflection points, supply‑chain stressors, and competitive positioning into a pragmatic playbook for pharma, generics manufacturers, API suppliers, and hospital procurement leaders.
Worldwide Glycopeptide Antibiotics Market
Why this analysis matters in 2026
-
Market momentum: The glycopeptide category has demonstrated steady recovery and expansion after pandemic-era volatility. Our baseline modeling — reflecting a 2025 market base and a 4.6% forecast CAGR — informs near-term portfolio prioritization and capital allocation decisions.
Worldwide Glycopeptide Antibiotics Market -
Regulatory and clinical drivers: Recent regulatory updates to antimicrobial susceptibility testing and evolving clinical guidance are reshaping relative value among glycopeptide agents and their competitors. These changes alter comparative effectiveness perceptions that payers and hospital formularies will use in 2026.
Worldwide Glycopeptide Antibiotics Market -
Supply‑chain fragility and input inflation: API and finished-dosage manufacturing economics have shifted materially — industry data indicate meaningful cost inflation for antibiotic APIs between 2022–2025. For 2026, companies must reconcile margin targets against higher input costs and concentrated sourcing footprints.
-
Commercial and reimbursement inflection: Reimbursement pathways for newer lipoglycopeptides and innovations in outpatient administration are creating profitable routings outside traditional inpatient channels, changing commercial models for the category.
Teaser of key findings
-
Growth trajectory: The category is on a moderate, stable growth path driven by persistent demand for effective MRSA and other Gram‑positive therapies, investment in novel formulations, and incremental label and reimbursement wins.
-
Consolidation posture: Market concentration is non-trivial — the top firms hold a material share of market sales — creating distinct advantages for scale players but leaving tactical openings for focused entrants with differentiated formulations or supply certainty.
-
Formulation-led differentiation: Novel ready‑to‑use and lipoglycopeptide formulations (offering longer dosing intervals and outpatient administration) are changing care site economics and procurement decisions.
-
Supply risk premium: Heavy geographic concentration of antibiotic API production creates a supply‑risk premium that is already reflected in procurement lead times and pricing negotiations.
Competitive landscape — what executives need to weigh
Our proprietary competitive analysis profiles the leading brand, generic, and API suppliers shaping category dynamics. The field comprises global innovators with branded lipoglycopeptides, multinational generics and injectables suppliers, and specialist API manufacturers. PW Consulting’s assessment highlights capability clusters rather than raw share tables to inform strategic choices:
-
Pfizer Inc. — As the owner of a marketed lipoglycopeptide indicated for acute bacterial skin and skin structure infections, Pfizer’s value proposition centers on differentiated dosing profiles and a branded clinical narrative that supports outpatient use. Their commercial muscle and payer engagement remain critical benchmarks for premium positioning.
-
Hikma Pharmaceuticals — A notable recent development is Hikma’s market entry with a ready‑to‑infuse vancomycin formulation approved in 2025. That approval alters hospital pharmacy workflows by simplifying IV preparation, reducing administration risk, and potentially shortening time-to-dose — attributes hospitals value highly in procurement decisions.
-
ANI Pharmaceuticals — With oral vancomycin assets focused on C. difficile, ANI occupies a specialized niche that intersects inpatient/outpatient transitions and stewardship considerations. Capsule formulations remain strategically important for outpatient management of C. difficile‑associated disease.
-
Fresenius Kabi — As a major supplier of generics and injectable formulations to hospitals, Fresenius operates at the intersection of scale manufacturing and hospital channel penetration. Their Kabi division’s injectable capabilities provide resilience where supply continuity is a hospital procurement priority.
-
Xellia, Aurobindo, Zhejiang Hisun, Viatris/Mylan — These firms represent the API and generic supply backbone. Their roles in providing vancomycin APIs and finished dosage forms create levers for cost, lead‑time, and quality. Securing partnerships or dual‑sourcing agreements with these suppliers is often a pragmatic mitigation against upstream shocks.
Strategic implication: companies without vertical integration or validated alternate sources may find themselves negotiating from a position of weakness in 2026. Conversely, manufacturers that can couple differentiated clinical assets with supply reliability will win formulary and contract concessions.
Industry context and dynamics shaping 2026 decisions
-
Regulatory updates: Advances in antimicrobial susceptibility testing and revised breakpoints for certain agents have downstream implications for formulary placement and clinical decision support tools. Companies must maintain active regulatory surveillance and update labels, dossiers, and hospital education programs accordingly.
-
API economics: A multi‑year rise in API production costs has changed unit economics; pricing strategies must be revisited and manufacturing footprints reassessed to protect margin while ensuring availability.
-
Geopolitical sourcing concentration: High import reliance from a limited set of geographies has prompted purchasers to request supplier mapping and continuity plans — an increasingly standard RFP requirement for 2026 contracting cycles.
-
Reimbursement mechanics: Specific reimbursement pathways for lipoglycopeptides in outpatient and hospital‑outpatient settings enhance their commercial case, but they also increase payer scrutiny of cost‑effectiveness and real‑world outcomes.
Actionable playbook for 2026
-
De‑risk supply: Implement dual‑sourcing mandates for critical APIs, secure long‑lead raw materials via forward contracts, and invest in near‑term inventory buffers tied to scenario triggers in the report.
-
Prioritize formulation advantages: Accelerate development or acquisition of ready‑to‑use and long‑acting formulations that reduce hospitalization days or enable outpatient infusion — these attributes command premium access and foster payor support.
-
Revisit pricing & contracting: Build tiered contracting that reflects supply reliability, outcome-based KPIs, and shared savings for reducing inpatient days or readmissions tied to specific glycopeptide therapies.
-
Engage payers earlier: Assemble pragmatic value dossiers that demonstrate real‑world effectiveness, stewardship outcomes, and site‑of‑care economics, especially for lipoglycopeptides positioned for outpatient administration.
-
Explore vertical plays: For mid‑sized manufacturers, selective upstream investment in API capacity or partnership agreements with established API houses provides negotiating leverage and margin protection.
-
Targeted M&A and alliances: Identify bolt‑on targets that fill portfolio gaps (e.g., outpatient formulations, sterile injectables, or API capacity) and accelerate time‑to‑market compared with greenfield projects.
-
Operationalize stewardship: Work with hospital systems to co‑design stewardship pathways that position glycopeptides appropriately, reducing inappropriate use while preserving access where clinically indicated.
Scenario planning — thresholds that should trigger action
PW Consulting’s report includes scenario models rooted in the 4.6% CAGR baseline, plus an upside pathway driven by rapid outpatient adoption of lipoglycopeptides and a downside path influenced by extended API disruptions or accelerated generic erosion. For 2026, recommended trigger events include sustained API lead‑time extension beyond a contractual threshold, material payer denials for outpatient coding, or a competitor achieving broad formulary replacement via a novel formulation — each of which should prompt tactical pivots identified in the playbook.
What’s in the full report (select contents)
-
Detailed market forecasts through 2032 with sensitivity bands and scenario narratives.
-
Comprehensive competitive profiles, manufacturing maps, and supply‑chain exposure matrices.
-
Regulatory and reimbursement matrix aligned to likely 2026 decision points.
-
Go‑to‑market playbooks for branded and generic strategies, including hospital contracting templates and payer engagement scripts.
-
Primary interview insights and proprietary supplier scoring methodologies.
-
Data annex with historical series and modeling assumptions (note: the report intentionally withholds highly granular regional and application split figures in this executive summary to protect proprietary analysis — full segmentation detail is available in the subscriber package).
PW Consulting’s Worldwide Glycopeptide Antibiotics Market report combines quantitative forecasting, on‑the‑ground supplier intelligence, and executable strategic guidance to support capital allocation, M&A screening, and commercial planning for 2026. For teams facing margin compression, supply uncertainty, or a need to pivot commercial models, this study provides a concise, decision‑grade foundation.
To access the full dataset, segmentation tables, and tailored advisory options, visit PW Consulting’s market research portal and request the complete study and executive briefing tailored to your organization’s role in the glycopeptide value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Glycopeptide Antibiotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com