

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Insulinoma Market to Expand at a 5.75% CAGR Through 2032, Unveiling New Growth Opportunities

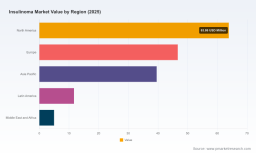
Worldwide Insulinoma Market — 2026 Strategic Preview
PW Consulting’s new market study, Worldwide Insulinoma Market (base year 2025; historical 2020–2025; forecast 2026–2032), delivers a compact but rigorous strategic playbook for companies planning to make material decisions in 2026. At the macro level, the market has expanded from roughly USD 126 million in 2020 to about USD 167 million in 2025, and our model projects continued growth through the forecast window with a steady compound annual growth rate (CAGR) of 5.75% (2026–2032) to reach an estimated market size north of USD 240 million by 2032. Those topline dynamics are the backdrop for a highly focused competitive set, a small and clinically complex patient population, and an evolving regulatory posture that together determine near-term commercial opportunity and clinical development strategy.
Worldwide Insulinoma Market
Why this report matters for 2026 decisions
-
Precision of timing: Several pivotal clinical programs and regulatory alignments now converge on a 2026 inflection point. Companies need a tight timeline-driven plan that aligns R&D, regulatory engagement, and commercial preparation in the same fiscal year.
Worldwide Insulinoma Market -
Small-population economics: Insulinoma and tumor-mediated hyperinsulinism sit within rare-disease economics. Successful value capture depends on integrating clinical differentiation with reimbursement strategy and selective commercial footprint planning.
Worldwide Insulinoma Market -
Concentration with room to move: Market concentration metrics indicate a mid-level aggregated share among the top competitors—enough scale for incumbents to defend position, yet clear openings exist for breakthrough therapies and partnerships that demonstrate meaningful clinical benefit.
Market dynamics and clinical context
The insulinoma therapeutic landscape remains anchored by surgical resection for localized disease, with medical therapies reserved for inoperable or malignant presentations. First-line medical management typically includes agents such as diazoxide, with somatostatin analogs and a range of off-label approaches used when hypoglycemia proves refractory. Epidemiology remains constrained—incidence is low, and a minority of cases behave aggressively or metastasize—creating both a challenge and an opportunity for sponsors pursuing novel modalities.
Recent regulatory and clinical developments have crystallized the pathway for anti-insulin targeted therapies. A notable example is the advancement of ersodetug, an anti-insulin monoclonal antibody developed by Rezolute, Inc., which is being evaluated in tumor-mediated hyperinsulinism including malignant insulinoma. Rezolute announced FDA alignment on a streamlined single-arm, open-label Phase 3 upLIFT trial design and expects topline data in H2 2026, with a parallel congenital hyperinsulinism program providing potential confirmatory evidence. These events underline a larger trend: regulators are willing to accept innovative, small-cohort designs accompanied by strong confirmatory linkage across related indications when unmet need and plausible mechanism of action are present.
What PW Consulting’s report provides (practical, action-focused)
-
Proprietary market model and scenario engine — granular, auditable forecasts with best/base/worst-case scenarios, sensitivity levers (pricing, uptake, addressable population), and interactive outputs to test commercial assumptions under multiple timelines.
-
Clinical-pathway maps and patient flow analysis — step-by-step depiction of diagnostic delays, referral patterns, surgical candidacy criteria, and the subset of patients likely to require chronic medical management.
-
Regulatory and trial design playbook — benchmarks and decision trees for accelerated pathways, single-arm pivotal strategies, surrogate endpoints, confirmatory evidence planning, and engagement templates for regulators and HTA bodies.
-
Commercial readiness checklist — go-to-market sequencing, field-force sizing guidance, center-of-excellence targeting, and distribution models tuned to low-volume, high-value therapies.
-
Reimbursement and value dossier framework — payer segmentation, expected evidence thresholds for coverage, pricing scenario planning, and contracting templates suitable for orphan and ultra-orphan assets.
-
Competitive intelligence dossiers — profiles of active companies, pipeline positioning, patent landscapes, and M&A/partnership heatmaps to help prioritize outreach and licensing opportunities.
-
Manufacturing and supply-chain risk matrix — demand-scaling scenarios, COGS sensitivities, and mitigation strategies for gene/biologic modalities common among next-generation insulinoma candidates.
Competitive landscape: actionable takeaways
The report aggregates competitor positioning into pragmatic categories—incumbent procedural leaders, mid-size specialty developers, and early-stage biologic innovators. While we do not publish every sub-segment table in this announcement, the study’s concentration metrics indicate that the top three firms hold a substantial, but not overwhelming, portion of market share, and the top five capture a clear majority. This concentration profile implies two strategic routes:
-
For established players: defend with clinical differentiation, broaden indications where feasible, and optimize center-level partnerships to maintain utilization of surgical and adjunctive procedures.
-
For new entrants/biotechs: pursue regulatory strategies that leverage small-cohort pivotal designs, validate value through clear downstream economic models, and seek strategic alliances for commercialization or distribution.
Rezolute’s recent regulatory alignment illustrates the profile of a development program that can materially shift the competitive map. For sponsors evaluating investment or partnership with similar candidates, our report models recruitment timelines, expected evidentiary gates for regulatory and HTA acceptance, and commercial scenarios tied to different labeling outcomes.
How 2026 corporate decisions should be informed by this study
-
R&D portfolio prioritization: Use the report’s go/no-go thresholds to allocate late-stage capital toward programs with demonstrable clinical differentiation, realistic trial recruitment plans, and clear regulatory pathways.
-
Regulatory engagement: Prioritize early and frequent dialogues with regulators to validate single-arm or hybrid trial designs, define acceptable confirmatory strategies across related indications, and reduce approval and launch risk.
-
Commercial sizing and sequencing: Prepare lean, high-impact launch plans that focus on centers of excellence and high-volume referral hubs; defer broad generalist field builds until payer coverage is secure.
-
Partnership and M&A strategy: Target bolt-on acquisitions that provide clinical trial acceleration, complementary modalities (e.g., diagnostics), or established specialty-clinic networks to compress time-to-revenue.
-
Payer strategy: Build a reimbursement dossier early—real-world evidence, economic modeling for avoided hospitalizations, and contracting approaches for rare-disease premiums are essential to secure access.
Practical tools and deliverables in the full report
Decision-makers will find immediately actionable materials: downloadable forecast workbooks, clinical trial recruitment heatmaps, payer dossier templates, a prioritized partner shortlist, and a six-quarter tactical launch plan. Our scenario engine allows executives to simulate the impact of alternative assumptions—e.g., faster-than-expected adoption versus delayed reimbursement—on net present value and break-even timelines.
Case study — resolving small-cohort regulatory risk
Rezolute’s pathway shows a pragmatic route to market in this therapeutic area: a streamlined Phase 3 single-arm trial aligned with the FDA, small patient cohorts sized to the condition’s rarity, and the strategic use of cross-indication confirmatory evidence. For companies facing similar junctures, the report lays out a template that aligns trial design, biomarker strategy, and commercial readiness so that regulatory risk and launch timing are jointly optimized rather than managed in isolation.
What the preview omits (and why you should read the full report)
In line with our “prequel” approach, this announcement intentionally omits granular regional and treatment-type split tables, detailed pricing scenarios tied to specific jurisdictions, and the full city-by-city center-of-excellence map. These are core assets within the full study because they are most valuable when tailored to an organization’s commercial, clinical, and regulatory strategy. Access to the full report unlocks the precise tables, interactive dashboards, and the downloadable financial model you will need to convert insight into action.
Final recommendation
For executives allocating capital or shaping clinical development strategies in 2026, a focused, evidence-driven approach is essential. The insulinoma market is expanding steadily, driven by better diagnostics, emergent targeted biologics, and regulatory flexibility for rare-disease programs. But success will hinge on linking clinical differentiation with pragmatic commercialization and payer strategies. PW Consulting’s Worldwide Insulinoma Market study is designed to be the single vetted source that helps you align those elements into a coherent 12–24 month execution plan.
To obtain the complete dataset, segmented forecasts, and the interactive scenario model, please consult the full report on our website. The detailed tables and tools are the executional instruments that will convert the strategic direction outlined here into measurable results.
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com