

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Oilseed Extraction Equipment Market to Expand at 5.12% CAGR (2026–2032), Reaching USD 7.45 Billion by 2032 as Asia‑Pacific Leads with USD 2.15 Billion in 2025
By pmarketresearch, 2026-07-15
PW Consulting: Strategic Brief — Worldwide Oilseed Extraction Equipment Market Outlook (2026)
Executive snapshot
PW Consulting today publishes a concise strategic briefing drawn from our forthcoming Worldwide Oilseed Extraction Equipment Market report (base year 2025, forecast 2026–2032). The global equipment market has shown steady expansion over the 2020–2025 historical window, reaching a mid‑year benchmark in 2025. Our modelling points to a compounded annual growth rate (CAGR) of approximately 5.12% across the 2026–2032 forecast horizon, culminating in a materially larger market by 2032. For executive teams preparing 2026 capital plans and supplier strategies, this trajectory underpins a near‑term environment of selective investment: continued demand for both retrofit upgrades and new crushing capacity — albeit in a market shaped by supply‑chain dynamics, raw‑material input volatility, and accelerating automation adoption.
Worldwide Oilseed Extraction Equipment Market
Why this intelligence matters for 2026 decisions
- CapEx prioritization: With moderate, predictable growth evident at the market level, procurement teams should favor staged investments that preserve optionality — e.g., pre‑engineered modular lines and phased automation that allow stepped commissioning and faster payback in variable commodity cycles.
- Vendor negotiation timing: Equipment lead times and raw‑material inputs (notably stainless steel and high‑value alloys) are the dominant drivers of price and delivery risk. Tactical postponement windows and indexed contracting can reduce exposure to short‑term spikes while protecting target throughput timelines.
- Technology differentiation: Automation control systems, heat‑recovery modules, and high‑efficiency transmission systems are shifting the performance curve. Buyers who benchmark equipment on energy intensity (kWh/ton processed), solvent‑loss metrics, and maintenance hours per shift will capture outsized gains in operating margin.
- Regulatory and food‑safety compliance: Increasing scrutiny on hygienic design and worker safety (including prescriptive infrastructure such as handwashing facilities and temperature controls in production areas) demands that M&E specifications embed compliance up front to avoid retrofits that erode ROI.
What the PW Consulting report delivers (practical, actionable content)
Our report is built as a decision‑support toolkit for C‑suite and plant‑level managers. It blends macro forecasting with hands‑on instruments that managers can deploy immediately:
Worldwide Oilseed Extraction Equipment Market
- Scenario‑based demand forecasts across 2026–2032, calibrated to energy, feedstock, and policy variables.
- CapEx vs. retrofit payback models tailored to common plant configurations and throughput bands (including sensitivity to energy and solvent prices).
- Vendor selection frameworks and RFP scorecards that prioritize total cost of ownership (TCO), spare‑parts availability, and local service footprints.
- Technology deep dives covering mechanical pressing, solvent extraction platforms, and pre‑treatment modules — with diagnostic matrices for yield, throughput, and environmental controls.
- Supply‑chain maps and risk heatmaps highlighting concentration points for critical inputs and components.
- Regulatory compliance checklists and a hygiene design matrix that aligns equipment specification with common food‑safety regimes.
- Practical deployment guidance for automation and energy‑saving retrofits, including case templates for ROI measurement and commissioning milestones.
Competition and supply‑side dynamics — what to watch in 2026
The market presents a mix of long‑standing OEM specialists and vertically integrated global suppliers. Market concentration is moderate: the combined share of the top three and top five suppliers indicates significant presence by established players while leaving room for regional specialists and new entrants. This structure creates both procurement opportunities and sourcing risks:
Worldwide Oilseed Extraction Equipment Market
- Global legacy innovators: Firms that pioneered continuous mechanical screw presses and solvent technologies remain influential. Their strengths lie in proven reliability, global commissioning experience, and comprehensive aftermarket networks — essential for large processors seeking turnkey assurance.
- Regional specialists and export champions: Several manufacturers from Asia and India specialize in cost‑competitive complete plants and have accelerated footprint expansion through export projects. These suppliers often compete on capital intensity and rapid delivery for mid‑scale crushing projects.
- Engineering systems houses: Companies offering integrated preparation, extraction, and downstream handling packages are responding to demand for single‑point accountability; these vendors combine equipment supply with project management and engineering oversight.
- Open innovation and niche OEMs: A cluster of smaller manufacturers focuses on high‑efficiency presses, bespoke pre‑treatment modules, and specialty solvent handling equipment — attractive for processors targeting differentiated product or niche seed types.
Recent industry activity underscores the ongoing market dynamism: established OEMs continue to showcase upgraded plants and extraction solutions at trade events, while international exhibitions remain pivotal venues for sourcing both technology and partners. For procurement teams, attending these events remains an efficient means to validate technical claims, assess service responsiveness, and negotiate project terms in person.
Notable suppliers (strategic profiles)
- Anderson International Corp (Cleveland, USA): Originator of continuous mechanical screw press architecture. Strengths include full‑system design capabilities and deep commissioning experience across diverse seed types and global climates. Recommended as a benchmark for reliability and system integration standards.
- French Oil Mill Machinery Company (Piqua, USA): Specialist builder of screw presses and roller mills with a strong exhibition presence and an emphasis on custom configurations. A solid option where bespoke mechanical extraction is prioritized.
- CPM / Crown Iron Works (USA): Offers advanced solvent extraction technologies and high‑performance mechanical systems. Noted for research‑led product development and a strong trade‑show program highlighting cross‑sector applications.
- Myande Group (China): Supplier of complete preparation and extraction lines with a significant installed base in Asia. Attractive for end‑to‑end project delivery and local after‑sales networks.
- GOYUM Screw Press (India): Competitive exporter of screw presses and solvent extraction plants; suited to buyers seeking lower capital intensity with acceptable performance trade‑offs.
- Henan Huatai and other Chinese OEMs: Provide broad product ranges from pre‑treatment to refining. They are important contenders for price‑sensitive projects and rapid deployments.
- Bühler Group (Switzerland): Global engineering house offering premium solutions embedded in a broader grain & oil processing portfolio; recommended for processors targeting long‑term efficiency and hygienic design leadership.
- RoseDowns and Muez Hest: Regional specialists with established mechanical press product lines and turnkey capabilities for targeted seed applications.
Input costs, materials, and operational risk
Procurement and plant engineering teams must treat raw‑material input trends as a central planning variable. Stainless steel — a core material for corrosion‑resistant components — is subject to global pricing dynamics driven by alloy‑costs, energy, and logistics. Industry references show stainless steel market and regional price variability that materially impacts equipment margins and lead‑time economics. Similarly, energy price volatility and solvent availability influence both OPEX and the relative appeal of mechanical pressing versus solvent extraction in specific operating contexts.
Operational levers for 2026
- Energy efficiency as a procurement filter: Require normalized energy consumption metrics in bids and weight them heavily in TCO calculations.
- Modularization & phased commissioning: Favor vendors that offer modular skids and phased scope to reduce first‑unit risk and enable incremental capacity additions as demand materializes.
- Service and spares strategy: Lock multi‑year spare‑parts agreements and ensure local stocking plans for critical wear items to reduce downtime exposure.
- Automation and digital twin pilots: Test automation packages with scoped pilot runs to validate yield improvements and predictive‑maintenance claims before enterprise scaling.
- Contractual protections: Use price‑index clauses for raw‑material pass‑throughs and include performance guarantees tied to energy consumption and extraction yield.
Next steps — how to use this briefing
For executives and plant managers making 2026 investment decisions, this briefing highlights the strategic inflection points and procurement levers that will determine competitiveness through the next planning cycle. PW Consulting’s full report expands each section into executable templates, detailed scenario worksheets, vendor scorecards, and a comprehensive appendix of technical specifications and benchmarking data — information designed to be adopted directly into CapEx evaluation processes and RFPs.
To access the complete dataset, granular segment analysis, and our proprietary vendor benchmarking tools, please visit the PW Consulting report landing page. The full publication contains the specific split‑level intelligence and downloadable models that we intentionally exclude here to preserve the integrity of our premium advisory product and to ensure readers engage with the full, validated dataset.
For detailed analysis of this topic, please visit the official page: Worldwide Oilseed Extraction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Medium Entropy Alloys Market Set to Reach USD 235.94 Million by 2032, Backed by a 9.5% CAGR
By pmarketresearch, 2026-07-15
Worldwide Medium Entropy Alloys Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting's newest market study — Worldwide Medium Entropy Alloys Market (base year 2025, forecast 2026–2032) — arrives at a pivotal inflection for materials-intensive industries. With the sector forecast to expand at a compound annual growth rate of 9.5% through 2032 and the global market more than set to nearly double over the forecast window, this report translates macro momentum into boardroom-ready actions for 2026 planning cycles. Our objective here is to summarize the strategic value of the research for senior executives and investment committees while preserving the report’s proprietary segment-level detail for subscribers and qualified stakeholders.
Worldwide Medium Entropy Alloys Market
Macro snapshot that matters for 2026 planning
Medium entropy alloys (MEAs) have moved beyond academia into commercial engineering by combining tailored multi-component chemistries with scalable processing routes such as powder metallurgy and additive manufacturing. PW Consulting’s topline market model — built on historical sales (2020–2025) and a bottom-up segmentation of demand drivers — shows consistent expansion through 2025 and projects robust growth across the 2026–2032 forecast horizon. The combination of accelerated adoption in high-performance applications and ongoing supply-side consolidation drives the 9.5% CAGR that underpins strategic scenarios in the report.
Worldwide Medium Entropy Alloys Market
Key takeaways for financial planning: the market today represents a distinct and investable vertical with reliable growth characteristics suitable for multi-year capex allocation, targeted M&A, and partnership playbooks. Scenario layers in our modelling quantify sensitivity to raw material swings, regulatory friction, and technology adoption rates — inputs that will directly influence operating plans and procurement strategies in 2026.
Worldwide Medium Entropy Alloys Market
What the report delivers — practical, executable intelligence
- Actionable market architecture: A clear taxonomy of MEA subtypes, manufacturing pathways, and application clusters mapped to buyer pain points and certification milestones.
- Decision-centric forecasting: Base, upside, and downside scenarios that translate macro drivers (cost inflation, commodity access, regulation) into likely revenue outcomes at enterprise and portfolio levels.
- Supply-chain heat maps: Risk-ranked supplier ecosystems, chokepoint analysis for critical elements (nickel, cobalt, chromium, titanium), and playbooks for supplier diversification and secured sourcing.
- Technology & product roadmaps: Comparative assessment of powder metallurgy, casting, thermomechanical processing, and additive manufacturing readiness, including commercialization timelines and capex intensity estimates.
- Regulatory and sustainability overlay: Compliance stress-testing and CO2 footprint mitigation strategies, including the role of recycled stainless and nickel scrap in reducing lifecycle emissions.
- M&A and partnership playbook: Target profiles, integration risks, and value-capture levers for acquirers seeking scale, IP, or upstream raw-material control.
- Commercial go-to-market templates: Pricing pressure matrices, channel strategies for industrial OEMs, and buyer persona frameworks tailored to aerospace, transportation, and power-generation procurement cycles.
Why this matters for 2026 decisions
Enterprises face three concentrated choices in 2026: deepen vertical integration, buy capability through M&A, or partner selectively to access new alloy formulations and processing know-how. Each path has materially different capital and operational implications; our report quantifies these in ways that allow CFOs and strategy teams to stress-test ROI under realistic market dynamics. Specific strategic levers highlighted include:
- Procurement hedging and indexation clauses to offset nickel and cobalt price volatility — a material input risk in MEA manufacturing.
- Investment in recycling and circularity to reduce CO2 footprints and buffer commodity price cycles; our modelling demonstrates the trade-offs between primary and recycled feedstocks in capex and lifecycle emissions.
- Accelerated adoption of computational alloy design and co-development partnerships with organizations specializing in model-driven alloy discovery to reduce time-to-market for high-value formulations.
- Targeted capability builds in additive manufacturing to capture premium unit economics in low-volume, high-spec applications.
Supply-side realities and sustainability trade-offs
Upstream exposure is the single largest operational risk in MEA commercialization. Production of key alloying elements remains geographically concentrated, creating geopolitical and logistics tail risks that are highly relevant to 2026 capital and inventory strategies. Environmental and material safety regulations are tightening in many jurisdictions, increasing compliance costs for alloy producers — a dynamic the report models explicitly.
On the opportunities side, circular feedstocks present both cost and environmental advantages. Our sustainability analysis synthesizes academic and market data to show that the incorporation of recycled stainless steel and nickel alloy scrap can lower carbon intensity meaningfully. For context, market-observed scrap channels trade within a broad price band; leveraging these streams can be both an emissions and cost mitigation strategy as companies plan for new product lines and supplier contracts in 2026.
Competitive landscape — positioning the industry’s leaders
The market remains moderately concentrated among established specialty metallurgy and advanced materials suppliers. PW Consulting’s competitive review profiles incumbents and challengers across capability vectors — alloy design, production scale, certification experience, and route-to-market. Highlights include:
- Carpenter Technology Corporation: Strong legacy in high-performance alloys and an established footprint in aerospace and defense supply chains. Their position makes them a logical partner or acquirer for firms seeking aerospace certification pathways.
- ATI Inc. (Allegheny Technologies): Deep expertise in specialty alloy production and component manufacturing; strategically positioned to integrate downstream fabrication with novel MEA formulations.
- Haynes International: Niche strength in nickel- and cobalt-based alloys; well-suited to applications demanding extreme corrosion and high-temperature resistance.
- Sandvik AB and VDM Metals: European players with integrated R&D and production capability, attractive for partnerships that require rapid scale-up and EU-compliant supply chains.
- Hitachi Metals (Proterial), Stanford Advanced Materials, Matexcel, MSE Supplies: A mix of specialty powder suppliers and materials distribution networks that accelerate adoption in additive manufacturing and research-driven product pipelines.
- QuesTek Innovations: Representative of a new class of computational alloy design specialists — high strategic value for firms looking to compress alloy development cycles and derisk application-specific performance.
Collectively, the top-tier firms exert meaningful influence over price, standards, and certification practices. The market’s three- and five-firm concentration dynamics imply that strategic partnerships or selective M&A can shift competitive balance — an insight the report quantifies under multiple commercialization timelines.
How to use this report in 2026 planning cycles
Strategists and procurement leads should use the report to: (1) set realistic revenue and margin guardrails for new MEA product launches; (2) develop sourcing playbooks that explicitly model commodity shocks; (3) evaluate make-versus-buy decisions with lifecycle emissions and certification timelines embedded; and (4) identify M&A targets where engineering capabilities or certified production lines accelerate market entry.
Investment committees and corporate development teams will find the report’s scenario outputs especially useful when aligning capital approval thresholds to realistic commercialization risk curves. For R&D and product teams, the comparative technology readiness assessments and supplier scorecards create a prioritized list of development partnerships that balance scientific novelty with manufacturability.
What we intentionally withhold — and why
In line with our “teaser” approach to this announcement, PW Consulting is publishing the strategic implications and methodological framework broadly while preserving proprietary, granular segmentation tables and supplier-level financial models for subscribers. The full report contains detailed forecasts by region, application, and alloy type, supplier scorecards with performance indicators, and transaction-ready M&A dossiers — elements that are available through the official report access channels and designed to support procurement negotiations and investment due diligence.
Next steps for executives
- Download the executive summary and scenario dashboard to benchmark current plans against our base and stress scenarios for 2026–2032.
- Schedule a strategic briefing with PW Consulting to walk through supplier scorecards and the bespoke risk simulation tailored to your portfolio.
- Initiate a short-list process for computational alloy design and AM partners using the supplier archetypes profiled in the report as selection filters.
Medium entropy alloys create a rare combination of technical upside and commercial defensibility for companies that move early and with clarity. The decisions you make in 2026 about sourcing strategy, technology partnerships, and capital allocation will define competitive positioning for the next decade. PW Consulting’s Worldwide Medium Entropy Alloys Market report equips leaders with the macro foresight, tactical tools, and risk analytics required to convert materials innovation into sustained business advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Narrow-Body Aircraft MRO Market Poised to Hit USD 80.89 Billion by 2032, Growing at a 5.6% CAGR
By pmarketresearch, 2026-07-15
Worldwide Narrow-Body Aircraft MRO Market — Strategic Outlook for 2026
As airlines, lessors, and MRO providers finalize budgets and capital plans for 2026, decision-makers need a concise, actionable read on where narrow-body maintenance demand will concentrate, which business models will win, and what operational levers will preserve margin in an environment of tight labor pools, elevated material costs, and lingering supply-chain friction. PW Consulting’s latest market study on the Worldwide Narrow-Body Aircraft MRO Market (base year 2025; forecast 2026–2032) synthesizes market-scale projections, competitive shifts, and pragmatic playbooks tailored for the year ahead — without giving away the segment-level line items that determine contract strategies.
Worldwide Narrow Body Aircraft MRO Market
Executive snapshot
In aggregate terms, the narrow-body MRO market has shown resilient recovery and sustained expansion since the pandemic trough, with total industry revenues approaching the mid‑tens of billions USD by 2025. Our model projects steady growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.6%, taking the market to roughly USD 80–81 billion by 2032. Market concentration remains meaningful but not monopolistic: the three largest players control approximately 31% of the market, while the five largest capture just under 43% — a structure that preserves room for mid-sized independents and airline-affiliated specialists to capture niche value.
Worldwide Narrow Body Aircraft MRO Market
Why 2026 is a decision inflection point
- Fleet composition is evolving, but maintenance demand is persistent. Operators continue to push higher utilization on narrow‑body fleets for short- and medium-haul networks, creating predictable recurring maintenance volumes even as newer engine types increase technical complexity.
- Licensing and certified capability are differentiators. Certification for advanced narrow‑body engines — particularly the LEAP family — has shifted where restoration work can be executed. Entrants that secured Premier or equivalent licenses in 2025–2026 are earning prolonged repair and overhaul flows.
- Cost pressures are structural, not cyclical. Wage inflation among certified technicians and elevated material prices have become baseline assumptions for 2026 planning, compressing returns for service providers that cannot translate productivity improvements into unit-cost relief.
Macro dynamics that should shape 2026 choices
Three dynamics dominate near-term strategy:
Worldwide Narrow Body Aircraft MRO Market
- Demand growth and market scale. The market’s expansion at a mid-single-digit CAGR provides a stable backdrop for capacity investments, but does not eliminate competition for profitable work. Firms must differentiate on lead times, technical breadth, and integrated supply solutions rather than relying on volume alone.
- Workforce scarcity and wage trajectory. Skilled labor shortages—especially certified mechanics and engine shop specialists—drove wage inflation of approximately 6.6% in 2024 with expected normalization toward ~5.7% in 2025. For 2026, workforce strategy (training pipelines, automation of non‑certified tasks, and retention incentives) will determine who can sustain throughput without sacrificing margin.
- Material and supply-chain volatility. Parts inflation and component lead times remain above pre‑pandemic norms; material costs rose markedly in 2024 with lingering pressure in 2025. MROs and operators that lock effective long-term supplier arrangements or invest in pooled inventory models will gain a competitive cost-of-repair advantage.
What incumbent operators and MROs are doing
Recent industry moves highlight three strategic responses that will define winners in 2026:
- Capability consolidation and licensing investments. Airline-affiliated MROs and large independents have moved to secure full licensed capability for next-generation narrow‑body engines, enabling them to capture a broader share of life-cycle spend and shorten repair loops.
- Regional capacity densification. Leading independents opened or expanded engine and airframe facilities in high-utilization hubs to reduce ferry costs and improve turnaround performance.
- Long-term service agreements and material partnerships. Operators and OEM-affiliated groups are locking multi-year material and shop-visit contracts to mitigate supply shocks and stabilize pricing — a trend that will accelerate in 2026 as airlines prioritize reliability and predictable maintenance spend.
Competitive landscape — where to watch
The market remains multi‑polar. A handful of global players—both airline-affiliated and independents—compete for core narrow‑body portfolios, while regional specialists and capacity-focused independents exploit service gaps. Key strategic profiles to monitor include:
- Large airline-affiliated MROs that leverage captive fleet volumes to justify investment in advanced engine certifications and wide hangar footprints, thereby offering integrated, high-capacity solutions.
- Global independents that combine scale, diversified facility footprints, and multi-platform capabilities to serve both airline and leasing customers, often competing on speed and scope.
- Regional specialists and independents that concentrate on line maintenance, component pools, or shop-visit niches where proximity and turnaround time create defensible value.
Notable firm-level actions in 2025–2026 illustrate these dynamics: several leading providers announced capability expansions and long-term agreements relevant to narrow-body fleets, while others secured multi‑year contracts or enlarged engine MRO capacity in strategic hubs. These moves materially affect where operators will route work in 2026 and beyond.
Operational playbook for 2026
Based on our scenario analysis and operator interviews, PW Consulting recommends five pragmatic priorities for firms that want to preserve or expand their MRO economics next year:
- Prioritize certification and cross-platform skill development. Investing in licensed LEAP family and other next-gen engine capabilities reduces dependence on third parties and shortens repair windows for high-utilization fleets.
- Reconfigure capacity with modularity in mind. Expand lines or shop bays that can switch between engine, airframe, and component throughput to smooth utilization spikes and reduce idle capital.
- Secure supply resilience through layered contracts. Combine strategic supplier agreements with regional inventory hubs and pooled parts arrangements to mitigate lead-time and price volatility.
- Embed productivity engineering into maintenance workflows. Adopt targeted automation for non-certification tasks, lean process redesign for turnaround events, and digital planning tools that minimize on-wing time and AOG exposure.
- Design commercial offers that reflect certainty value. Market multi-year, outcome-based contracts with price indexing tied to transparent cost drivers (labor, material indices), thereby sharing risk and creating stickier customer relationships.
Investment and M&A signals for 2026
With the market growing steadily and concentration at the top yet open, 2026 will present selective acquisition opportunities and greenfield logic for capacity-constrained providers. Strategic buyers should look for targets that offer:
- Established certification footprints or fast-track routes to complex engine licensing;
- Geographic hubs that shorten operator ferry legs and reduce AOG exposure;
- Proven programs for component pooling or inventory optimization that can be scaled across a buyer’s network;
- Management teams with disciplined operational execution and demonstrated cost-control during inflationary periods.
What PW Consulting’s report delivers (actionable, not exhaustive)
Our Worldwide Narrow‑Body Aircraft MRO Market study is designed to be an operational guide for 2026 planners. Practical deliverables include:
- Top-line market sizing and seven-year forecasts with scenario sensitivity for utilization, substitution, and regulatory shifts;
- Competitive positioning matrices that reveal capability overlaps, certification gaps, and likely win-sets for different contract types;
- Operational diagnostic checklists for hangar optimization, workforce planning, and parts-pool design that lead to measurable unit-cost improvements;
- Commercial playbooks for structuring long-term service agreements, performance-based contracts, and material-supply partnerships;
- Due-diligence templates for M&A and greenfield investment, including integration risks and upside levers.
We deliberately stop short of publishing granular regional or application-level splits in this public summary — those are included in the full report alongside supplier maps, facility-level capacities, and modelled P&L impacts for alternative routing strategies.
Implications for specific stakeholders
- Airlines and lessors: Lock in predictable capacity for heavy checks and engine shop visits in 2026 through staggered, indexed service agreements; invest in predictive maintenance analytics to stretch shop visit intervals safely.
- MRO providers: Focus capital on certifications that convert into guaranteed shop-visit flows and redesign workforce pipelines to reduce reliance on expensive external labor markets.
- Investors: Seek businesses with diversified revenue streams (airframe, engine, component) and proven inventory-management capabilities; caution against pure line‑maintenance plays without access to captive operator pipelines.
Next steps and how to access the detailed intelligence
PW Consulting’s report is structured to inform immediate 2026 budget cycles and multi-year strategic plans. For executives preparing CapEx proposals, contract negotiations, or M&A diligence in the narrow‑body MRO space, the full study contains the region-by-region capacity maps, facility-level operating metrics, and scenario-specific financial models required to act with conviction.
To obtain the complete dataset, segmented forecasts, and the provider-level appendix that supports the strategic recommendations summarized here, please visit the report page (link in the distribution notice) — the public summary intentionally omits those segment-level tables to preserve the contextual value of the full deliverable.
Closing perspective
2026 will not be a return to simple volume plays for narrow‑body MRO. Instead, it will reward firms that combine technical certification, supply resilience, and operational productivity — executed within commercial models that share risk while rewarding reliability. The market’s steady growth trajectory and measurable concentration at the top create both predictable revenue pools and clear whitespace for differentiated players. PW Consulting’s study equips leaders with the forecasts, competitive intelligence, and implementation tools to convert 2026’s strategic inflection into durable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: Worldwide Integral Waterproofing Compound Market to Reach USD 6,043.68 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Integral Waterproofing Compound Market — Strategic Briefing for 2026 Decision-Making
Executive snapshot
PW Consulting’s latest market study on the Worldwide Integral Waterproofing Compound market consolidates historical performance (2020–2025) and presents a structured, decision-ready forecast for 2026–2032. The global market reached approximately USD 4.22 billion in 2025 and, with a compound annual growth rate (CAGR) of 5.28% over the forecast horizon, is modelled to approach roughly USD 6.04 billion by 2032. This trajectory reflects steady demand driven by infrastructure renewal cycles, rising durability expectations, and tighter sustainability and specification regimes in both mature and growth markets.
Worldwide Integral Waterproofing Compound Market
Why this report matters for 2026 strategy
-
Actionable foresight: The study translates macro growth into scenario-based revenue and margin outcomes under alternative raw-material and regulatory paths — enabling procurement, product, and M&A leaders to stress-test business plans against plausible 2026 shock events.
Worldwide Integral Waterproofing Compound Market -
Timing: With 2026 marking a turning point for many construction programs and sustainability rollouts, the report aligns commercial planning cycles with medium-term demand inflection points and cost-pressure windows.
Worldwide Integral Waterproofing Compound Market -
Competitive clarity: A deep-dive competitive framework identifies where legacy producers, specialized crystalline innovators, and chemical conglomerates are focusing R&D and commercial expansion — informing partnership, pricing, and channel strategies.
What the report contains — practical, executable outputs
The research is built for operational teams as much as corporate strategists. Highlights include:
-
A robust top-down and bottom-up market sizing model (2020–2032) published in USD (Million), including sensitivity runs for energy and silicone price scenarios to quantify margin exposure and passthrough timelines.
-
Scenario planning playbooks that map supplier and customer actions across three realistic market states (baseline, raw-material shock, accelerated sustainability adoption) with quantified P&L and working-capital implications.
-
Go-to-market blueprints for seven commercial archetypes (global masterbrand, regional specialist, ready-mix integrator, EPC partner, distributor-led, low-cost commodity player, hybrid tech provider) with prioritized tactics and sample KPIs.
-
Supplier resilience scorecards and a procurement toolkit: bill-of-materials risk heat maps, hedging and contract templates, and a recommended cadence for vendor requalification under heightened volatility.
-
Product roadmaps and formulation levers: trade-offs between crystalline chemistries, hydrophobic modifiers, and polymeric systems with manufacturing capex and time-to-market estimates for five upgrade paths.
-
Regulatory and sustainability matrix: mapping of low-VOC, bio-based agent acceptance, and green-building credit pathways by market cluster to prioritize certification investments.
-
M&A and partnership screening: a shortlist of target profiles, integration risk checklists, and valuation sensitivities tied to achievable synergies in distribution, blending, and technology transfer.
Market dynamics shaping 2026 choices
-
Raw-material volatility: Key feedstocks (cement derivatives, silica fillers, silicone monomers and specialty polymer emulsions) remain exposed to energy and petrochem cycles. Historical swings in silicone pricing during 2021–2023 serve as an instructive precedent for how input cost shocks can compress margins and reshuffle supplier competitiveness.
-
Cost stratification and value capture: Commodity hydrophobic powder admixtures continue to compete on price in cost-sensitive manufacturing hubs, while premium crystalline and hybrid products differentiate on durability, warranty terms, and reduced lifecycle leakage risk. Pricing architecture and channel incentives will be decisive for margin recovery in 2026.
-
Sustainability and specs: An accelerating preference for low-VOC and bio-derived hydrophobic agents is influencing product roadmaps and procurement specifications — a trend tied to green building standards and public-works procurement requirements. Manufacturers that can demonstrate compliance without severe cost inflation will access premium projects.
-
Operational integration: Liquid dosing compatibility with automated ready-mix plants and supplementary cementitious materials is reshaping adoption curves for certain formulations. Manufacturers and ready-mix producers that co-develop dosing solutions and blended SKUs are unlocking scale advantages.
Competitive landscape — what incumbents and challengers signal for 2026 moves
The market exhibits a mixed structure: global chemical majors and construction-specialist groups coexist with niche crystalline innovators and regional formulators. Market concentration is moderate, reflecting both scale advantages and room for specialized entrants; this creates strategic choices for investors and corporate development teams.
-
Sika AG (Baar, Switzerland) — A long-standing leader with a broad portfolio spanning crystalline powders to liquid permeability-reducing admixtures. Sika’s heritage in integral waterproofing and global distribution capacity make it a natural partner for large infrastructure projects and multinational ready-mix players. For 2026, Sika’s strength lies in cross-selling within established construction systems and accelerating specification wins through integrated warranties and technical support.
-
Kryton International Inc. (Vancouver, Canada) — Originator of a crystalline internal membrane approach, Kryton’s technology-led positioning centers on durability and self-sealing performance. Its intellectual property and project credentials make it attractive for asset owners focused on lifecycle cost minimization. In 2026, Kryton-style innovators will be targets for licensing, distribution partnerships, or bolt-on acquisitions by formulators seeking a performance premium.
-
Xypex Chemical Corporation (Richmond, Canada) — Specialises in admixtures that integrate into the concrete matrix. Xypex’s emphasis on long-term ingress prevention aligns with tunnelling, marine, and water-containment applications — market segments that command premium pricing and extended warranty regimes.
-
The Euclid Chemical Company (Cleveland, USA) — Known for powdered stearate-based blends and practical admixtures tailored for US construction standards. Euclid’s distribution ties to regional contractors and ready-mix operators give it tactical strength in localized procurement and specification channels.
-
Anti-Hydro International & Penetron — Legacy brands with century-spanning pedigrees in integral waterproofing, offering credibility in long-life asset classes and refurbishment projects.
-
Pioneer Fibre, Chem Concrete, BASF, Mapei, Fosroc, Pidilite — A mix of regional specialists and global chemical firms: BASF and Mapei bring formulation scale and R&D breadth; Fosroc and Pidilite combine regional penetration with cost-competitive supply chains; Chem Concrete illustrates the disruptive potential of hybrid multi-mechanism admixtures with warranty-backed claims.
Strategic plays for 2026 — prioritized, measurable actions
We recommend four focused initiatives for companies seeking to convert market momentum into defensible growth in 2026:
-
Hedge and diversify feedstock exposure — implement a layered procurement strategy combining multi-year supply agreements for high-volatility chemistries, opportunistic spot exposure for benign inputs, and a supplier development fund to qualify regional alternatives within 6–9 months.
-
Product tiering with clear value propositions — define three to four SKUs per market cluster (commodity, performance-differentiated, sustainability-premium, integrated warranty) and align pricing, channel incentives, and technical service to each tier. Quantify the willingness-to-pay uplift for durability and sustainability attributes in target segments before 2H 2026 rollout.
-
Commercial partnerships with ready-mix and EPC players — co-develop dosing and blended solutions that reduce installation risk and speed spec adoption. Offer pilot warranties and co-marketing to accelerate proofs of concept on flagship infrastructure projects.
-
M&A and IP playbook — prioritize assets that deliver one of: (a) technology differentiation (crystalline/hybrid chemistries), (b) regional manufacturing footprints that lower logistics cost, or (c) distribution channels into high-growth construction markets. Use earn-outs tied to technical validation and warranty performance to mitigate integration risk.
How commercial teams should use this report in 2026
-
Procurement: adopt the report’s supplier resilience matrix and implement monthly raw-material stress tests feeding into rolling 12-month hedging decisions.
-
R&D/Product: prioritize low-VOC and bio-derived modifier pilots, mapped to the report’s regulatory matrix, with go/no-go gates tied to cost parity thresholds and certification timelines.
-
Business development: use the partner archetype playbooks to structure trials with ready-mix and EPC customers; target wins where warranty-backed performance can be demonstrated within an 18–24 month window.
-
Corporate development: apply the M&A screening tool to rank targets by technology defensibility, commercial traction, and integration ease — generating a prioritized transaction funnel for 2026 execution.
Final note — an invitation to deeper intelligence
This briefing distils the strategic contours and operational levers that will matter most in 2026. The full PW Consulting Worldwide Integral Waterproofing Compound Market report contains the proprietary segment models, granular demand drivers by application and region, supplier-level margin analytics, and downloadable decision tools referenced here. To access the complete dataset, interactive scenarios, and executable playbooks — including the confidential subsegment matrices omitted from this summary — please visit the PW Consulting report page or contact our industry desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Integral Waterproofing Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.85% CAGR for Worldwide Phenolic Molding Compound Market, Hitting USD 3,128.18 Million by 2032
By pmarketresearch, 2026-07-15
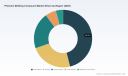
Worldwide Phenolic Molding Compound Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting today releases an executive preview of our new Worldwide Phenolic Molding Compound (PMC) Market study — an operationally oriented market intelligence product designed to inform capital, procurement and product strategy decisions for 2026 and beyond. The global PMC market has demonstrated steady expansion through the early 2020s, rising from USD 1,810.45 Million in 2020 to USD 2,245.50 Million in 2025. Our baseline projection anticipates continued growth into the next decade, reaching approximately USD 3,128.18 Million by 2032 at a compound annual growth rate (CAGR) of 4.85% over the 2026–2032 forecast horizon. This preview explains why that trajectory matters, what tactical intelligence the full report contains, and the concrete actions executives should consider in 2026.
Worldwide Phenolic Molding Compound Market
Why this report matters now
- Timing: 2026 is the inflection year for many buyers and manufacturers who are reassessing supply chains, material costs and qualification timetables for new product generations. Our forecast and scenarios provide a working roadmap for those decisions.
- Practicality: This is not a high‑level summary. The report is engineered to be used — with procurement playbooks, supplier scorecards, pricing pass‑through models and certification roadmaps that translate market signals into executable decisions.
- Risk management: With feedstock volatility and changing regional flows, manufacturers and OEMs need forward‑looking cost and capacity scenarios to protect margin and continuity of supply. Our deliverables are tailored for CFOs, procurement heads and VP‑level product leaders.
What the report delivers — operational modules
- Top‑down market sizing and validated bottom‑up forecasts (2026–2032) with scenario variants — conservative, baseline and upside — reflecting feedstock cycles and demand elasticity.
- Proprietary price pass‑through model linking phenol and cumene feedstock movements to finished PMC cost curves (run in regional scenarios), with sensitivity analyses for +/- 10–25% swings in raw materials.
- Supplier scorecards and capacity maps covering technology, qualification lead times, quality classes (including UL / RTI profiles) and logistics constraints.
- Application‑level insight and go‑to‑market playbooks for priority segments — automotive, electrical & electronics, industrial components and aerospace/defense — focused on qualification timelines and value capture.
- Commercial negotiation tools: suggested contract structures, hedging frameworks, inbound logistics optimization and inventory policy templates calibrated to PMC lead times and shelf‑stability realities.
- M&A and partnership playbook identifying the types of assets that accelerate capability (e.g., proprietary high‑adhesion formulations, UL‑qualified pellet lines, regional compounding footprint).
- Interactive Excel datasets and dashboards (time series, scenario toggles, supplier heat maps) for in‑house modelling and boardroom presentation.
Key data‑driven insights from the study
- Market momentum: The PMC market has rebounded from cyclical softness in the mid‑2020s to a structurally higher baseline in 2026. Our baseline projects the market to expand from the USD 2,245.50 Million level in 2025 to roughly USD 2,430.68 Million in 2026, setting the stage for continued, compound growth thereafter.
- Raw material dynamics: Phenol pricing exhibits meaningful regional divergence that must be embedded into procurement and pricing strategies. As of March 2026, Northeast Asia phenol was trading at approximately USD 1.01/kg (up around 8.6% from December), Europe near USD 1.00/kg (a modest decline from late‑year levels), and North America around USD 1.18/kg (a small dip versus December). These movements reflect regional feedstock availability, import flows and demand from resin manufacturers — and they materially change short‑term margin dynamics for compounders and molders.
- Certification and electrical performance as differentiators: UL certification remains a gating factor for many electrical and electronics uses. Our cross‑reference of UL database entries shows active certifications covering flame class, hot wire ignition (HWI), high current arc ignition (HAI) and relative thermal index (RTI) for pelletized PMCs — a shortlist that buyers should treat as a precondition for supplier selection in safety‑critical segments.
- Innovation pockets: Technical progress is concentrated in resin chemistries and adhesion systems that allow reliable bonding to diverse substrates and higher temperature endurance. Notably, one large supplier announced a new high‑adhesion phenolic resin series in March 2026 — a type of innovation likely to accelerate premiumization in mixed‑material assemblies.
Competitive landscape — practical takeaways
The sector combines global incumbents with regional specialty players. Our competitive analysis synthesizes public disclosures, plant footprints and recent strategic moves into actionable competitor risk profiles:
Worldwide Phenolic Molding Compound Market
- Sumitomo Bakelite Co., Ltd. — A global integrator with multi‑site production, recent capacity expansion in Nantong completed in 2024, and a March 2026 product launch focused on high‑adhesion phenolics. Their advantage lies in broad application reach and a steady investment cadence in formulation and plant footprint.
- PLENCO (Plastics Engineering Company) — A US‑based technical compounder that emphasizes dimensional stability and high‑temperature performance for industrial and electrical uses; an attractive partner for OEMs needing short qualification cycles and custom compounding.
- Bakelite Synthetics — A global thermoset supplier with strong channel presence in consumer and electrical segments; useful as a volume supply partner with standardized product ranges.
- Chang Chun Plastics (LONGLITE) — Focused on customer‑specific formulations for electrical and automotive uses; their strength is rapid customization and technical collaboration for application fit.
- Resinoid Engineering Corporation — Specialized in high‑temperature aftermarket phenolics; a relevant counterparty for thermal‑critical repair and aftermarket channels.
- Shengquan Group — Large scale phenolic resin producer with upstream integration; a key raw material partner for compounders seeking secure resin supply and cost leverage.
- Kaihua Ruida Plastic‑Tech — Producer of UL‑approved PMC grades and Bakelite powders, positioned for appliances, construction and automotive subassemblies where certification and dimensional control are priorities.
Strategic implications & recommended actions for 2026
- Lock in multi‑tier supply arrangements: Given regional phenol price dispersion and the potential for feedstock squeeze, secure at least two qualified compound suppliers in geographically diverse locations and negotiate formula‑linked pricing clauses.
- Prioritize UL/RTI pathways: For electrical and mixed‑use components, accelerate certification timelines now — product qualification can take 9–18 months and will determine 2027 sourcing flexibility.
- Adopt dynamic hedging and pass‑through contracts: Use the pass‑through model in the full report to design contracts that balance supplier margin protection with end‑market price sensitivity.
- Invest selectively in higher‑value formulations: Where customers value adhesion or thermal endurance (e.g., electric powertrain components or high‑density electrical modules), allocate R&D budget to secure differentiated PMC grades that command premium pricing and longer product lifecycles.
- Monitor consolidation targets: Mid‑sized compounders with UL portfolios or unique chemistries represent attractive bolt‑on M&A, but perform deep technical and supply continuity due diligence (our M&A checklist is included in the report).
- Operationalize scenario planning: Run quarterly scenarios with +/- 15% feedstock shifts and mapped lead‑time impacts to inventory days — the report’s dashboard facilitates this modelling for procurement and planning teams.
What to expect from the full report — the “paywall” value
This preview intentionally showcases the analytical depth and practical orientation of our work while withholding the granular segmentation matrices and company‑level scorecard detail that most firms need to act. The full report contains:
Worldwide Phenolic Molding Compound Market
- Granular regional and application splits with downloadable pivot tables and regression models (reserved for report subscribers).
- Supplier‑by‑supplier capability matrices, certification status and plant‑level capacity schedules.
- Actionable contract language templates, a pricing model workbook and a procurement playbook you can implement immediately.
- Primary interview transcripts and methodological notes supporting the forecast.
Getting the intelligence into the boardroom
Executives who need to make 2026 decisions should treat this study as a working toolkit rather than a backgrounder. We recommend a two‑hour briefing with our analysts to run your company through the scenario dashboard, followed by a tailored one‑week deep‑dive to map specific product lines, qualification gates and supplier strategies. That combination translates market intelligence into binding short‑term actions and a one‑year roadmap for procurement, R&D and capacity planning.
PW Consulting’s Worldwide Phenolic Molding Compound Market report is designed to reduce the uncertainty around feedstock volatility, certification timelines and qualification risk. For operational leaders facing tight schedules and complex supply chains, the report provides the models and playbooks required to convert a market forecast into resilient commercial decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.12% CAGR for Worldwide Dal Mill Machine Market Through 2032
By pmarketresearch, 2026-07-15
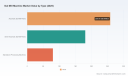
Worldwide Dal Mill Machine Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market intelligence brief on the Worldwide Dal Mill Machine Market is targeted at executives, investors, and procurement leaders who must make capital allocation, product strategy, and market-entry decisions in 2026. Using a 2025 base and a seven‑year forecast horizon (2026–2032), our model shows the market advancing from a mid‑single‑hundred million USD industry in 2020 to roughly USD 520 million in 2025, with a projected climb to approximately USD 788 million by 2032 (CAGR: 6.12%). Those headline numbers mask meaningful heterogeneity across plant types, capacity bands and national markets — this report surfaces the commercial levers that turn that heterogeneity into opportunity while deliberately reserving granular segment tables for full‑report subscribers.
Worldwide Dal Mill Machine Market
Why this brief matters for 2026 planning
-
CapEx prioritization: Manufacturers and large processors must decide which plant formats and automation features to invest in mid‑2026 to capture rising demand and maintain margins as unit economics shift.
Worldwide Dal Mill Machine Market -
Supply‑chain resilience: Recent upstream cost shocks and trade policy shifts have altered delivered equipment economics; procurement strategies must reflect new total cost of ownership (TCO) realities.
Worldwide Dal Mill Machine Market -
Regulatory compliance and export strategies: Food safety requirements and export controls are changing the addressable market for both equipment makers and end‑users; this report maps compliance obligations against product roadmaps.
-
M&A and partnership diligence: For private equity and strategic buyers, a fragmented competitive landscape creates roll‑up opportunities — we provide the competitive intelligence to guide target screening.
What the report delivers — practical, decision‑grade outputs
-
Market sizing and forecast model (2020–2032), with base year 2025 and scenario runs that stress steel, labor and trade drivers.
-
Price and cost curves for core equipment elements, including fabrication, electro‑mechanical assemblies, and control systems.
-
Buyers’ playbook: procurement checklists, expected lead times, installation and commissioning budgets, spare‑parts profiles and after‑sales best practices.
-
Technology adoption map covering PLC automation, vision/color sorting, high‑speed splitters, and AI‑driven quality inspection — including vendor positioning and likely time‑to‑value for adopters.
-
Country and macro overlays: agricultural supply trends, trade policy impact matrix, and regulatory compliance checklist tailored for major pulse‑producing and importing countries.
-
Competitive benchmarking: dossiers on leading OEMs, product line maps, installed‑base intelligence and channel strategies — ideal for commercial counterparty assessment.
-
Investment and M&A appraisal tools: valuation comparables, consolidation scenarios, and integration risk flags.
-
Primary research appendices: interview synopses with processors, OEMs and trade bodies, plus an explanation of our forecasting methodology and assumptions.
Key market dynamics shaping 2026 decisions
Five forces will determine winners and losers in the next 18–36 months. First, raw material inputs to machinery fabrication are more volatile: hot‑rolled coil prices rose materially into late 2025, raising fabrication bills and lengthening supplier negotiation cycles. Second, macro demand is being underpinned by a step‑up in pulse production in key origin markets, which is accelerating investments in automated milling capacity. Third, regulatory drivers — notably food safety mandates that require HACCP‑compatible designs for processing equipment — are shifting procurement toward vendors who can certify compliance and provide traceable validation. Fourth, labor markets are tightening and wage inflation in food processing is increasing operating cost pressure; processors are consequently accelerating automation to protect margins. Finally, trade policy changes (including duties on unprocessed pulses instituted in major producing countries) are rerouting volumes toward domestic milling, altering the market for both small modular plants and large integrated lines.
For procurement and planning teams this combination translates into three tactical imperatives: reprice TCOs with updated steel and logistics assumptions; prioritize modular, HACCP‑compliant equipment that can be upgraded with automation; and build supplier redundancy to manage lead‑time and warranty risk.
Competitive landscape — concise, actionable read
The market remains fragmented: the top three OEMs account for roughly one‑fifth of market value (CR3 ≈ 21.4%), and the top five approach one‑third (CR5 ≈ 31.8%). That structure creates room for differentiation — either by scale players pursuing full‑line supply and global distribution, or by specialists targeting niche applications and aftermarket services.
-
Milltec Machinery Pvt. Ltd. (Bengaluru, India) — A leader in fully automated plants integrating cleaning, grading, splitting and polishing. Recent demonstrations at AgriTech India showcased AI‑enabled sorting capabilities that signal a strategic move to combine mechanical expertise with computer‑vision quality control. This positions the company well for high‑volume exporters and processors seeking end‑to‑end automation.
-
Pramick Engineering Consultants Pvt. Ltd. (Hyderabad, India) — A recognized specialist in compact and semi‑automatic mills. The firm’s 2025 launch of a compact 500 kg/hr model with energy‑efficient polishers responds to rising small‑processor demand for lower OPEX and rapid payback. Pramick’s strength is speed‑to‑market for smaller capacity segments.
-
GBS Engineering Enterprises (Hyderabad, India) — Known for complete processing lines incorporating emery roll polishers and gravity selection. Their delivery of a 10‑ton plant to a large exporter underscores capabilities at higher capacities and export‑spec projects.
-
Jay Khodiyar Industries & Narnoli Engineering Works (Rajkot) — Both firms compete strongly in compact and small‑scale configurations, emphasizing cost‑effectiveness and localized service networks — a valuable proposition where labor costs and logistics favor on‑site support.
-
Bharat Agritech (Indore) — Differentiates with PLC‑controlled integrated plants and attention to export‑quality finishes; suitable for processors pursuing premium export channels.
-
Masoor Industries (Akola) — Focused product specialization (e.g., lentil/masoor specific machines) and color sorting add value for premium segments where yield and visual grading drive price premiums.
-
United Oil Mill Machinery (Ludhiana) — Offers hybrid solutions (polishers with oil coatings, aspirators) that target processors requiring specific product textures or legacy recipes.
Across vendors, capability clusters are becoming clear: full‑plant integrators competing on automation and export compliance; compact innovators targeting small and medium processors; and specialized equipment makers focused on yield and premium output quality. Recent product and trade show activity indicates that suppliers are racing to couple mechanization with digital quality control — an important axis of differentiation for buyers evaluating long‑term TCO.
Strategic scenarios and recommended actions for 2026
-
OEMs: Prioritize modular product lines and retrofit packages that meet HACCP requirements and can be upgraded with vision systems. Introduce financing/leasing options to accelerate adoption among small and medium processors who face capex constraints.
-
Large processors and exporters: Fast‑track pilot installations of AI sorting and PLC‑based traceability to secure premium quality channels. Recalculate payback under elevated steel costs and higher skilled labor wages; consider local fabrication partnerships to reduce landed costs.
-
Investors and consolidators: Target bolt‑on acquisitions that add aftermarket service networks or digital quality capabilities. Given the modest concentration ratios, well‑executed consolidations can unlock scale benefits in procurement and R&D.
-
Service providers and fintechs: Build bundled offerings that combine equipment financing, maintenance contracts and spare parts distribution — an attractive model for processors seeking predictable OPEX.
Modeling, sensitivity and what we withheld
The full report includes an interactive forecast model with sensitivity levers for raw‑material fabrication costs, wage inflation, export duty scenarios and automation adoption rates. To preserve the role of this piece as a strategic “trailer,” we have intentionally omitted detailed segment tables (by region, by plant type, and by capacity) from this release. Those granular splits, together with country‑level market maps and vendor installed‑base counts, are available in the full dataset on the report landing page.
How to use this intelligence in Q1–Q3 2026
-
Run TCO comparisons on at least three procurement scenarios: retrofit, mid‑range full plant, and top‑end automated line. Use our model assumptions for steel and wage inflation to stress‑test payback timelines.
-
Require HACCP validation and traceability features in RFPs; select vendors who can document compliance and provide process validation kits.
-
For international buyers, factor in origin country trade policy changes that may redirect volumes toward domestic milling and alter raw‑material availability for export channels.
-
Negotiate spare‑parts and service SLAs at contract stage — aftermarket service is the decisive margin lever in a fragmented market.
Conclusion — a practical playbook for 2026
PW Consulting’s Worldwide Dal Mill Machine Market report is designed as a practical playbook for 2026 decisions: it translates macro growth (market expansion through 2032 at a ~6.1% CAGR) into vendor selection criteria, procurement tactics, and M&A strategies. The industry is entering a phase where compliance, automation and supply‑chain choices will disproportionately determine outcomes. If your 2026 plan involves new capacity, vendor selection, or an investment thesis in food‑processing equipment, this report provides the analytic scaffolding and executable checklists to move from intention to impact.
For the full segment breakdowns, country maps, vendor installed‑base data and downloadable forecast model, please visit the PW Consulting report page or contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dal Mill Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Subsea Well Access & BOP Systems Market at USD 4,680 Million in 2025, Poised to Reach USD 6,762.85 Million by 2032 on a 5.4% CAGR
By pmarketresearch, 2026-07-15
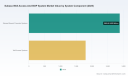
Worldwide Subsea Well Access And BOP System Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting's latest market study on the Worldwide Subsea Well Access and BOP System market provides a focused, execution‑oriented intelligence package designed to inform capital allocation, procurement strategy, and technology decisions in 2026. Anchored on a 2025 base year and a historical review covering 2020–2025, the study forecasts the market across 2026–2032. The global market is estimated at USD 4,680 Million in 2025 and, at a compound annual growth rate of 5.4%, is projected to reach approximately USD 6,762.9 Million by 2032. These macro trajectories frame a mid‑decade inflection point for operators, OEMs and service providers operating in deepwater and ultra‑deepwater environments.
Worldwide Subsea Well Access And BOP System Market
What the report delivers — practical, deployable insights
- Proprietary market sizing and forward scenarios: base‑case, supply‑constrained and upside resource‑development cases calibrated to commodity and capex cycles.
- Decision support models: configurable NPV and ROI templates that map procurement timing, system selection (BOP vs well access integration) and intervention cadence to lifecycle cost outcomes.
- Supplier intelligence and scorecards: objective assessments of OEM capabilities across technology, manufacturing depth, aftermarket capacity, and regional service footprints.
- Supply‑chain and materials diagnostics: lead‑time matrices for high‑strength steels and corrosion‑resistant alloys, and margin pressure scenarios tied to raw material volatility.
- Regulatory and technical compliance matrix: alignment checklists for API and industry standards (including intervention and BOP specifications), plus sour service material requirements.
- Operational playbooks: templates for contracting (capex vs service‑contract tradeoffs), intervention planning, and staged deployment strategies to derisk ultra‑deepwater programs.
- M&A and partnership roadmaps: criteria for bolt‑on acquisitions, JV structuring and supplier alliances to accelerate capability capture or secure long‑lead components.
Why 2026 is a pivotal planning year
- Market momentum and timing. With the market on a steady expansion path from the 2020–2025 period into an expected growth phase through 2032, 2026 sits at the start of a multi‑year procurement horizon. Early decisions on specification, sourcing and partner selection materially affect delivery risk and life‑of‑field economics.
- Technical escalation into frontier basins. Major OEMs are racing to field 20,000 psi equipment and other high‑pressure designs to access frontier reservoirs and extreme bottom‑hole pressures. This technical escalation is reshaping product roadmaps, qualification cycles and aftermarket requirements.
- Standards and sour‑service compliance. API and NACE requirements (including high‑pressure PR2 qualifications and MR0175 compliance) are becoming non‑negotiable for equipment and materials in sour environments. Compliance affects supplier pools and unit costs, and imposes longer qualification lead times.
- Material and cost inflation pressure. Manufacture of subsea stacks is steel‑intensive; high‑strength steels and corrosion‑resistant alloys are a chokepoint for capacity and pricing. Typical wide pricing ranges for subsea BOP stacks (reflecting pressure rating and specification complexity) are forcing operators to re‑visit procurement model assumptions.
- Concentration and negotiating dynamics. The market exhibits meaningful concentration among incumbent OEMs and large service providers, creating distinct tradeoffs between technological capability and procurement leverage. Strategic sourcing must factor in the limited set of suppliers who can deliver fully qualified ultra‑deepwater systems on schedule.
Competitive landscape — interpreting OEM moves and strategic signals
The supplier landscape is anchored by a cohort of large, vertically integrated OEMs and highly specialized service providers. Leaders combine manufacturing, controls and intervention capability with global service footprints. From a strategic perspective, buyers should evaluate vendors across three vectors: delivery integration, technology differentiation and aftermarket resilience.
Worldwide Subsea Well Access And BOP System Market
- Baker Hughes Company (Houston) — Strengths lie in integrated subsea well access systems and Installation and Workover Control Systems. The firm's broad product set, including BOPs and IWOCS, positions it to offer end‑to‑end delivery on complex deepwater projects.
- SLB (Schlumberger Limited) (Houston) — OneSubsea and associated completions technology remain central to SLB's strategy. Recent large awards for ultra‑deepwater completions underscore its emphasis on interval control systems and full‑system deployments in pre‑salt and analogous plays.
- Aker Solutions ASA (Fornebu) and TechnipFMC (Newcastle/Houston) — Both prioritize integrated subsea production systems and intervention packages, offering buyers consolidated solutioning that reduces interface risk but often reduces competitive pricing pressure.
- NOV Inc. (National Oilwell Varco) , Dril‑Quip and Weatherford — Focused on pressure control hardware and wellhead systems, these suppliers maintain deep manufacturing capability for high‑pressure ram BOPs and specialized completion equipment.
- Oceaneering , Helix Energy Solutions and Expro — Service‑oriented players that bring riserless intervention and novel valve systems to the market. Notably, Expro's recent launch of a consolidated shear‑and‑seal ball valve (validated to API and NACE standards) highlights continued incremental innovation aimed at reducing intervention complexity and cost.
- Proserv and other niche specialists — Provide control and subsea production enhancement technologies that can be critical differentiators in tightly constrained projects.
Market concentration metrics reinforce a market where a handful of firms capture a majority of revenue and delivery capacity. This dynamic benefits buyers that can align early with an OEM to secure capacity, but it also elevates the value of competitive tender design, strict specification control and staged qualification strategies. Recent activity — large upstream awards and targeted product launches — underlines the practical consequences of OEM positioning for procurement windows and negotiation leverage.
Worldwide Subsea Well Access And BOP System Market
Strategic recommendations for buyers and investors in 2026
- Adopt staged procurement and qualification gates. Lock material‑critical long‑lead items early (qualified to the applicable API/NACE standards), while deferring discretionary modular elements until nearer to hook‑up to preserve flexibility.
- Prioritize lifecycle cost over headline unit price. Integrate intervention frequency, spare‑parts strategy and operational downtime exposure into procurement scoring to avoid cost surprises during operations.
- Insist on demonstrated high‑pressure qualifications. For frontier programs, require supplier evidence of 20,000 psi capability or credible roadmap and test data to mitigate technical execution risk.
- Design contracting to manage capacity risk. Use blended strategies (capex buyouts + service contracts) to hedge supplier concentration and ensure access to skilled personnel and testing slots.
- Diversify supply‑chain exposure for critical alloys. Where feasible, source alternate qualified manufacturers or hold strategic spares to blunt lead‑time variability driven by material shortages.
- Pilot innovations in a controlled manner. New simplified valve systems and consolidated components (e.g., single‑valve shear‑and‑seal assemblies) deliver cost and reliability benefits but require controlled field trials before fleet‑wide adoption.
- Pursue strategic partnerships and JV models. For operators entering new basins or deploying ultra‑deep campaigns, co‑investing in local qualification facilities or service capacity can accelerate delivery and reduce unit costs over multi‑well programs.
- Embed regulatory readiness into project plans. API 16A/17G alignment, PR2 processes for high‑pressure BOPs and material NACE MR0175 certification must be scheduled into procurement timelines to prevent terminal delays.
How PW Consulting helps execute
Our report is built as a practitioner’s toolkit: interactive financial models, supplier scorecards and procurement templates that can be used directly in RFP design, vendor negotiations and board‑level investment cases. We combine granular technical checklists with scenario economics so that engineering, procurement and finance teams speak from the same playbook when deciding between vendor integration, phased procurements, or service‑led solutions.
This bulletin is intentionally a strategic preview: it surfaces the trends, the competitive dynamics and the action levers that will matter in 2026 without disclosing the detailed proprietary segmentation tables that underpin our full forecast. For program‑level sizing, supplier benchmarking outputs and configurable NPV models, request the full report on the PW Consulting report page to unlock the complete data package and decision support assets.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide NBR Latex Market to Expand at 8.01% CAGR, Reaching USD 4,476 Million by 2032 as Asia‑Pacific Leads
By pmarketresearch, 2026-07-15
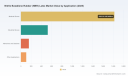
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on Worldwide Nitrile Butadiene Rubber (NBR) Latex synthesizes five years of historical intelligence (2020–2025) and delivers a seven‑year forward-looking forecast (2026–2032). The objective of this briefing is to translate the report’s macro findings into a concise set of decision levers for corporate leaders planning capital, sourcing and product strategies in 2026. We highlight the trajectory of the overall market, the structural dynamics shaping supplier economics, and the practical actions that will preserve margin and optionality through near-term volatility and medium-term growth.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Market trajectory — a recovering market with durable upside
After cyclical pressure during the early 2020s, the global NBR latex market regained momentum through 2024–2025. Our market model sizes the industry at approximately USD 2.61 billion in 2025, with a projected expansion to roughly USD 2.885 billion in 2026 and continued growth to around USD 4.476 billion by 2032. That path implies a compound annual growth rate (CAGR) of approximately 8.01% across the 2026–2032 forecast window — a healthy expansion that supports both organic capacity investments and strategic consolidation.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
The recovery and forecasted growth are underpinned by two durable demand pillars: healthcare/differentiated glove applications and performance-driven industrial uses. At the same time, volatility in feedstock and logistics (notably butadiene and acrylonitrile pricing and periodic shipping disruptions) is shaping producer cost curves and prompting faster product and supply‑chain adjustments than seen in prior cycles.
Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
What PW Consulting’s report delivers — practical, transaction‑ready intelligence
The full report is designed as a working tool for commercial, procurement and corporate development teams. Key deliverables include:
- Top‑down market sizing and bottom‑up demand modelling calibrated across 2020–2025, with rolling forecasts through 2032 and scenario sensitivities that stress feedstock price swings and logistics constraints.
- Price, margin and break‑even analyses reflecting feedstock pass‑through potential and varying grade mixes.
- Granular demand drivers by application class and grade design (medical vs industrial vs specialty), combined with practical implications for product development and sales prioritisation.
- Supply‑side mapping: manufacturer benchmarking, plant footprints, and a proprietary concentration analysis summarising market shares and competitive tightness (CR3 and CR5 metrics are included to support consolidation diligence).
- Regulatory and sustainability overlays that quantify compliance cost implications (e.g., low‑VOC requirements under regional chemical regulation frameworks) and estimate the commercial premium for bio‑based and lower‑carbon grades.
- Transaction – ready analysis: M&A scorecards, JV sourcing frameworks, and near‑term capex decision matrices that align payback expectations to our demand scenarios.
- Primary‑research driven perspectives (supplier and buyer interviews) that validate market behavior, contract flexibility, and propensity for long-term sourcing commitments.
To preserve competitive value for clients and readers, the report intentionally withholds certain detailed sub‑segment datapoints in this press release. The complete dataset, company‑level models and downloadable scenario files are available in the full PW Consulting report.
Competitive landscape — who matters and why
The NBR latex supply base is diverse, with established chemical majors, regional specialists and integrated petrochemical groups all playing distinct roles. Several themes emerge from our competitive benchmarking:
- Scale and specialization: A small set of global and regional leaders dominate higher‑value supply chains serving medical and critical industrial applications. These players combine large upstream feedstock access with technical grades and distribution networks that support fast-response glove dipping and specialty dipping customers.
- Technology and grade differentiation: Producers prioritizing innovation — specialty NBR grades, low‑VOC chemistries, and bio‑based offerings — are capturing premium placements in regulated markets. Recent product launches across the supplier base confirm accelerating product differentiation as a competitive strategy.
- Supply elasticity: Several suppliers have pursued capacity additions and regional finishing capabilities to reduce logistics risk and meet just‑in‑time demand from glove manufacturers and industrial dippers. This makes spot availability more resilient in some corridors while leaving others vulnerable to shipping and tariff shocks.
- Consolidation pressure: Market concentration metrics indicate moderate consolidation among top suppliers, creating opportunities for acquisitive strategies by mid‑sized producers seeking scale and for end‑users to negotiate longer‑term strategic partnerships.
Our company profiles cover leading manufacturers and regional specialists, with analysis of strategic positioning, innovation pipelines, and commercial behavior. Recent industry moves — for example, launches of bio‑based NBR latex and regional capacity additions — are analyzed for their implications on pricing, contract structures and supplier selection criteria.
2026 strategic imperatives — what decision‑makers must act on now
Given the market trajectory and the operational pressures in play, we recommend that executives prioritize four interlinked actions in 2026:
- Lock in feedstock and logistics resilience. Establish layered purchasing strategies: short‑term hedges to protect against immediate butadiene and acrylonitrile swings, combined with strategically staggered long‑term offtakes with key suppliers. Evaluate nearshore or localised finishing capacity to reduce exposure to shipping corridor disruptions and tariffs.
- Differentiate product portfolio toward regulatory and sustainability premiums. Accelerate development or sourcing of low‑VOC and bio‑based NBR latex grades for customers operating in regulated jurisdictions. Our pricing simulations show a measurable commercial premium for sustainable and REACH‑compliant grades in tender outcomes.
- Shift commercial models toward strategic partnerships. For glove manufacturers and industrial dippers, pursue committed volume agreements with supplier clauses for capacity priority, joint inventory buffers, and collaborative product roadmaps. For suppliers, consider tolling, co‑investment and embedded service models that secure feedstock access and stable throughput for new plants.
- Use scenarios to time capex and M&A. With an approximate 8.01% CAGR in our base forecast, greenfield investments can be attractive — subject to feedstock price scenarios and realistic commissioning timelines. Opportunistic M&A to acquire differentiated grades or regional finishing capability can shorten time‑to‑market and reduce logistics risk; use the report’s M&A scorecards to triage targets against integration risk and payback thresholds.
Risk map & scenario planning
Our analysis emphasizes three acute risk clusters that should be stress‑tested in every 2026 plan:
- Feedstock cost shocks: Sudden rises in crude‑linked feedstock prices materially compress margins unless pricing can be passed through or hedged.
- Trade & logistics disruptions: Shipping route interruptions and tariff escalations can produce regional shortages quickly, affecting manufacturers that lack diversified sourcing.
- Regulatory tightening & sustainability premiums: Accelerating requirements for lower‑VOC chemistries and documentation of lifecycle emissions shift buyer preference toward certified suppliers; failure to invest can erode access to regulated markets.
For each cluster, the report provides quantified scenario outcomes and recommended contingency playbooks — from immediate procurement triggers to mid‑term investment contingencies — enabling teams to align budgets and commercial KPIs to risk appetite.
Operational tactics — immediate steps for procurement, R&D and BD teams
To translate strategy into action during 2026, PW Consulting recommends the following operational steps (executable within 90–180 days):
- Procurement: Implement layered contracting with mix of spot, fixed‑volume, and index‑linked agreements; add logistics contingency clauses and priority allocation language.
- R&D: Fast‑track certification pathways for low‑VOC and bio‑based grades; engage strategic partners for co‑development to reduce capex and accelerate commercialization.
- Business Development: Reframe commercial proposals to buyers with value‑based pricing that includes supply assurance, sustainability credentials, and co‑innovation commitments.
- Corporate Development: Run targeted M&A screens using our scorecards to identify targets that supply critical grades, regional finishing, or proprietary chemistries — prioritize assets that shorten customer lead times.
Why this matters for 2026
The combination of steady market growth (our model points to expansion from roughly USD 2.61 billion in 2025 to over USD 4.47 billion by 2032 at an ~8.01% CAGR), ongoing regulatory pressure, and supply‑side volatility creates a strategic sweet spot. Companies that secure feedstock resilience, differentiate along sustainability and quality axes, and pursue pragmatic partnerships will capture outsized share and margin gains. Those that defer supplier diversification and product investment risk being priced out of regulated end‑markets or suffering from episodic shortages.
Next steps & accessing the full analysis
This briefing highlights the context and recommended decision levers emerging from PW Consulting’s Worldwide NBR Latex Market study. The full report contains the detailed data tables, regional and application splits, proprietary demand model, company scorecards and downloadable scenario workbooks referenced here. For procurement teams, R&D leaders and corporate development professionals looking to convert insight into actions in 2026, the full report and accompanying advisory services provide the executable playbooks and validated models required to move from strategy to results.
PW Consulting stands ready to support rapid workshops, supplier negotiation playbooks, and transaction advisory informed by the report’s primary research and modelling. To access the full report and bespoke advisory offerings, please consult the PW Consulting distribution channels.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrile Butadiene Rubber (NBR) Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com