

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.12% CAGR for Worldwide Dal Mill Machine Market Through 2032

Worldwide Dal Mill Machine Market — Strategic Outlook for 2026 Decision‑Makers
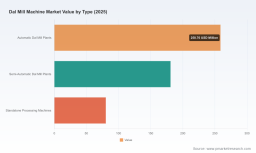
PW Consulting’s new market intelligence brief on the Worldwide Dal Mill Machine Market is targeted at executives, investors, and procurement leaders who must make capital allocation, product strategy, and market-entry decisions in 2026. Using a 2025 base and a seven‑year forecast horizon (2026–2032), our model shows the market advancing from a mid‑single‑hundred million USD industry in 2020 to roughly USD 520 million in 2025, with a projected climb to approximately USD 788 million by 2032 (CAGR: 6.12%). Those headline numbers mask meaningful heterogeneity across plant types, capacity bands and national markets — this report surfaces the commercial levers that turn that heterogeneity into opportunity while deliberately reserving granular segment tables for full‑report subscribers.
Worldwide Dal Mill Machine Market
Why this brief matters for 2026 planning
-
CapEx prioritization: Manufacturers and large processors must decide which plant formats and automation features to invest in mid‑2026 to capture rising demand and maintain margins as unit economics shift.
Worldwide Dal Mill Machine Market -
Supply‑chain resilience: Recent upstream cost shocks and trade policy shifts have altered delivered equipment economics; procurement strategies must reflect new total cost of ownership (TCO) realities.
Worldwide Dal Mill Machine Market -
Regulatory compliance and export strategies: Food safety requirements and export controls are changing the addressable market for both equipment makers and end‑users; this report maps compliance obligations against product roadmaps.
-
M&A and partnership diligence: For private equity and strategic buyers, a fragmented competitive landscape creates roll‑up opportunities — we provide the competitive intelligence to guide target screening.
What the report delivers — practical, decision‑grade outputs
-
Market sizing and forecast model (2020–2032), with base year 2025 and scenario runs that stress steel, labor and trade drivers.
-
Price and cost curves for core equipment elements, including fabrication, electro‑mechanical assemblies, and control systems.
-
Buyers’ playbook: procurement checklists, expected lead times, installation and commissioning budgets, spare‑parts profiles and after‑sales best practices.
-
Technology adoption map covering PLC automation, vision/color sorting, high‑speed splitters, and AI‑driven quality inspection — including vendor positioning and likely time‑to‑value for adopters.
-
Country and macro overlays: agricultural supply trends, trade policy impact matrix, and regulatory compliance checklist tailored for major pulse‑producing and importing countries.
-
Competitive benchmarking: dossiers on leading OEMs, product line maps, installed‑base intelligence and channel strategies — ideal for commercial counterparty assessment.
-
Investment and M&A appraisal tools: valuation comparables, consolidation scenarios, and integration risk flags.
-
Primary research appendices: interview synopses with processors, OEMs and trade bodies, plus an explanation of our forecasting methodology and assumptions.
Key market dynamics shaping 2026 decisions
Five forces will determine winners and losers in the next 18–36 months. First, raw material inputs to machinery fabrication are more volatile: hot‑rolled coil prices rose materially into late 2025, raising fabrication bills and lengthening supplier negotiation cycles. Second, macro demand is being underpinned by a step‑up in pulse production in key origin markets, which is accelerating investments in automated milling capacity. Third, regulatory drivers — notably food safety mandates that require HACCP‑compatible designs for processing equipment — are shifting procurement toward vendors who can certify compliance and provide traceable validation. Fourth, labor markets are tightening and wage inflation in food processing is increasing operating cost pressure; processors are consequently accelerating automation to protect margins. Finally, trade policy changes (including duties on unprocessed pulses instituted in major producing countries) are rerouting volumes toward domestic milling, altering the market for both small modular plants and large integrated lines.
For procurement and planning teams this combination translates into three tactical imperatives: reprice TCOs with updated steel and logistics assumptions; prioritize modular, HACCP‑compliant equipment that can be upgraded with automation; and build supplier redundancy to manage lead‑time and warranty risk.
Competitive landscape — concise, actionable read
The market remains fragmented: the top three OEMs account for roughly one‑fifth of market value (CR3 ≈ 21.4%), and the top five approach one‑third (CR5 ≈ 31.8%). That structure creates room for differentiation — either by scale players pursuing full‑line supply and global distribution, or by specialists targeting niche applications and aftermarket services.
-
Milltec Machinery Pvt. Ltd. (Bengaluru, India) — A leader in fully automated plants integrating cleaning, grading, splitting and polishing. Recent demonstrations at AgriTech India showcased AI‑enabled sorting capabilities that signal a strategic move to combine mechanical expertise with computer‑vision quality control. This positions the company well for high‑volume exporters and processors seeking end‑to‑end automation.
-
Pramick Engineering Consultants Pvt. Ltd. (Hyderabad, India) — A recognized specialist in compact and semi‑automatic mills. The firm’s 2025 launch of a compact 500 kg/hr model with energy‑efficient polishers responds to rising small‑processor demand for lower OPEX and rapid payback. Pramick’s strength is speed‑to‑market for smaller capacity segments.
-
GBS Engineering Enterprises (Hyderabad, India) — Known for complete processing lines incorporating emery roll polishers and gravity selection. Their delivery of a 10‑ton plant to a large exporter underscores capabilities at higher capacities and export‑spec projects.
-
Jay Khodiyar Industries & Narnoli Engineering Works (Rajkot) — Both firms compete strongly in compact and small‑scale configurations, emphasizing cost‑effectiveness and localized service networks — a valuable proposition where labor costs and logistics favor on‑site support.
-
Bharat Agritech (Indore) — Differentiates with PLC‑controlled integrated plants and attention to export‑quality finishes; suitable for processors pursuing premium export channels.
-
Masoor Industries (Akola) — Focused product specialization (e.g., lentil/masoor specific machines) and color sorting add value for premium segments where yield and visual grading drive price premiums.
-
United Oil Mill Machinery (Ludhiana) — Offers hybrid solutions (polishers with oil coatings, aspirators) that target processors requiring specific product textures or legacy recipes.
Across vendors, capability clusters are becoming clear: full‑plant integrators competing on automation and export compliance; compact innovators targeting small and medium processors; and specialized equipment makers focused on yield and premium output quality. Recent product and trade show activity indicates that suppliers are racing to couple mechanization with digital quality control — an important axis of differentiation for buyers evaluating long‑term TCO.
Strategic scenarios and recommended actions for 2026
-
OEMs: Prioritize modular product lines and retrofit packages that meet HACCP requirements and can be upgraded with vision systems. Introduce financing/leasing options to accelerate adoption among small and medium processors who face capex constraints.
-
Large processors and exporters: Fast‑track pilot installations of AI sorting and PLC‑based traceability to secure premium quality channels. Recalculate payback under elevated steel costs and higher skilled labor wages; consider local fabrication partnerships to reduce landed costs.
-
Investors and consolidators: Target bolt‑on acquisitions that add aftermarket service networks or digital quality capabilities. Given the modest concentration ratios, well‑executed consolidations can unlock scale benefits in procurement and R&D.
-
Service providers and fintechs: Build bundled offerings that combine equipment financing, maintenance contracts and spare parts distribution — an attractive model for processors seeking predictable OPEX.
Modeling, sensitivity and what we withheld
The full report includes an interactive forecast model with sensitivity levers for raw‑material fabrication costs, wage inflation, export duty scenarios and automation adoption rates. To preserve the role of this piece as a strategic “trailer,” we have intentionally omitted detailed segment tables (by region, by plant type, and by capacity) from this release. Those granular splits, together with country‑level market maps and vendor installed‑base counts, are available in the full dataset on the report landing page.
How to use this intelligence in Q1–Q3 2026
-
Run TCO comparisons on at least three procurement scenarios: retrofit, mid‑range full plant, and top‑end automated line. Use our model assumptions for steel and wage inflation to stress‑test payback timelines.
-
Require HACCP validation and traceability features in RFPs; select vendors who can document compliance and provide process validation kits.
-
For international buyers, factor in origin country trade policy changes that may redirect volumes toward domestic milling and alter raw‑material availability for export channels.
-
Negotiate spare‑parts and service SLAs at contract stage — aftermarket service is the decisive margin lever in a fragmented market.
Conclusion — a practical playbook for 2026
PW Consulting’s Worldwide Dal Mill Machine Market report is designed as a practical playbook for 2026 decisions: it translates macro growth (market expansion through 2032 at a ~6.1% CAGR) into vendor selection criteria, procurement tactics, and M&A strategies. The industry is entering a phase where compliance, automation and supply‑chain choices will disproportionately determine outcomes. If your 2026 plan involves new capacity, vendor selection, or an investment thesis in food‑processing equipment, this report provides the analytic scaffolding and executable checklists to move from intention to impact.
For the full segment breakdowns, country maps, vendor installed‑base data and downloadable forecast model, please visit the PW Consulting report page or contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dal Mill Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com