

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Subsea Well Access & BOP Systems Market at USD 4,680 Million in 2025, Poised to Reach USD 6,762.85 Million by 2032 on a 5.4% CAGR

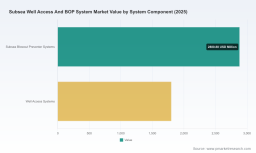
Worldwide Subsea Well Access And BOP System Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting's latest market study on the Worldwide Subsea Well Access and BOP System market provides a focused, execution‑oriented intelligence package designed to inform capital allocation, procurement strategy, and technology decisions in 2026. Anchored on a 2025 base year and a historical review covering 2020–2025, the study forecasts the market across 2026–2032. The global market is estimated at USD 4,680 Million in 2025 and, at a compound annual growth rate of 5.4%, is projected to reach approximately USD 6,762.9 Million by 2032. These macro trajectories frame a mid‑decade inflection point for operators, OEMs and service providers operating in deepwater and ultra‑deepwater environments.
Worldwide Subsea Well Access And BOP System Market
What the report delivers — practical, deployable insights
- Proprietary market sizing and forward scenarios: base‑case, supply‑constrained and upside resource‑development cases calibrated to commodity and capex cycles.
- Decision support models: configurable NPV and ROI templates that map procurement timing, system selection (BOP vs well access integration) and intervention cadence to lifecycle cost outcomes.
- Supplier intelligence and scorecards: objective assessments of OEM capabilities across technology, manufacturing depth, aftermarket capacity, and regional service footprints.
- Supply‑chain and materials diagnostics: lead‑time matrices for high‑strength steels and corrosion‑resistant alloys, and margin pressure scenarios tied to raw material volatility.
- Regulatory and technical compliance matrix: alignment checklists for API and industry standards (including intervention and BOP specifications), plus sour service material requirements.
- Operational playbooks: templates for contracting (capex vs service‑contract tradeoffs), intervention planning, and staged deployment strategies to derisk ultra‑deepwater programs.
- M&A and partnership roadmaps: criteria for bolt‑on acquisitions, JV structuring and supplier alliances to accelerate capability capture or secure long‑lead components.
Why 2026 is a pivotal planning year
- Market momentum and timing. With the market on a steady expansion path from the 2020–2025 period into an expected growth phase through 2032, 2026 sits at the start of a multi‑year procurement horizon. Early decisions on specification, sourcing and partner selection materially affect delivery risk and life‑of‑field economics.
- Technical escalation into frontier basins. Major OEMs are racing to field 20,000 psi equipment and other high‑pressure designs to access frontier reservoirs and extreme bottom‑hole pressures. This technical escalation is reshaping product roadmaps, qualification cycles and aftermarket requirements.
- Standards and sour‑service compliance. API and NACE requirements (including high‑pressure PR2 qualifications and MR0175 compliance) are becoming non‑negotiable for equipment and materials in sour environments. Compliance affects supplier pools and unit costs, and imposes longer qualification lead times.
- Material and cost inflation pressure. Manufacture of subsea stacks is steel‑intensive; high‑strength steels and corrosion‑resistant alloys are a chokepoint for capacity and pricing. Typical wide pricing ranges for subsea BOP stacks (reflecting pressure rating and specification complexity) are forcing operators to re‑visit procurement model assumptions.
- Concentration and negotiating dynamics. The market exhibits meaningful concentration among incumbent OEMs and large service providers, creating distinct tradeoffs between technological capability and procurement leverage. Strategic sourcing must factor in the limited set of suppliers who can deliver fully qualified ultra‑deepwater systems on schedule.
Competitive landscape — interpreting OEM moves and strategic signals
The supplier landscape is anchored by a cohort of large, vertically integrated OEMs and highly specialized service providers. Leaders combine manufacturing, controls and intervention capability with global service footprints. From a strategic perspective, buyers should evaluate vendors across three vectors: delivery integration, technology differentiation and aftermarket resilience.
Worldwide Subsea Well Access And BOP System Market
- Baker Hughes Company (Houston) — Strengths lie in integrated subsea well access systems and Installation and Workover Control Systems. The firm's broad product set, including BOPs and IWOCS, positions it to offer end‑to‑end delivery on complex deepwater projects.
- SLB (Schlumberger Limited) (Houston) — OneSubsea and associated completions technology remain central to SLB's strategy. Recent large awards for ultra‑deepwater completions underscore its emphasis on interval control systems and full‑system deployments in pre‑salt and analogous plays.
- Aker Solutions ASA (Fornebu) and TechnipFMC (Newcastle/Houston) — Both prioritize integrated subsea production systems and intervention packages, offering buyers consolidated solutioning that reduces interface risk but often reduces competitive pricing pressure.
- NOV Inc. (National Oilwell Varco) , Dril‑Quip and Weatherford — Focused on pressure control hardware and wellhead systems, these suppliers maintain deep manufacturing capability for high‑pressure ram BOPs and specialized completion equipment.
- Oceaneering , Helix Energy Solutions and Expro — Service‑oriented players that bring riserless intervention and novel valve systems to the market. Notably, Expro's recent launch of a consolidated shear‑and‑seal ball valve (validated to API and NACE standards) highlights continued incremental innovation aimed at reducing intervention complexity and cost.
- Proserv and other niche specialists — Provide control and subsea production enhancement technologies that can be critical differentiators in tightly constrained projects.
Market concentration metrics reinforce a market where a handful of firms capture a majority of revenue and delivery capacity. This dynamic benefits buyers that can align early with an OEM to secure capacity, but it also elevates the value of competitive tender design, strict specification control and staged qualification strategies. Recent activity — large upstream awards and targeted product launches — underlines the practical consequences of OEM positioning for procurement windows and negotiation leverage.
Worldwide Subsea Well Access And BOP System Market
Strategic recommendations for buyers and investors in 2026
- Adopt staged procurement and qualification gates. Lock material‑critical long‑lead items early (qualified to the applicable API/NACE standards), while deferring discretionary modular elements until nearer to hook‑up to preserve flexibility.
- Prioritize lifecycle cost over headline unit price. Integrate intervention frequency, spare‑parts strategy and operational downtime exposure into procurement scoring to avoid cost surprises during operations.
- Insist on demonstrated high‑pressure qualifications. For frontier programs, require supplier evidence of 20,000 psi capability or credible roadmap and test data to mitigate technical execution risk.
- Design contracting to manage capacity risk. Use blended strategies (capex buyouts + service contracts) to hedge supplier concentration and ensure access to skilled personnel and testing slots.
- Diversify supply‑chain exposure for critical alloys. Where feasible, source alternate qualified manufacturers or hold strategic spares to blunt lead‑time variability driven by material shortages.
- Pilot innovations in a controlled manner. New simplified valve systems and consolidated components (e.g., single‑valve shear‑and‑seal assemblies) deliver cost and reliability benefits but require controlled field trials before fleet‑wide adoption.
- Pursue strategic partnerships and JV models. For operators entering new basins or deploying ultra‑deep campaigns, co‑investing in local qualification facilities or service capacity can accelerate delivery and reduce unit costs over multi‑well programs.
- Embed regulatory readiness into project plans. API 16A/17G alignment, PR2 processes for high‑pressure BOPs and material NACE MR0175 certification must be scheduled into procurement timelines to prevent terminal delays.
How PW Consulting helps execute
Our report is built as a practitioner’s toolkit: interactive financial models, supplier scorecards and procurement templates that can be used directly in RFP design, vendor negotiations and board‑level investment cases. We combine granular technical checklists with scenario economics so that engineering, procurement and finance teams speak from the same playbook when deciding between vendor integration, phased procurements, or service‑led solutions.
This bulletin is intentionally a strategic preview: it surfaces the trends, the competitive dynamics and the action levers that will matter in 2026 without disclosing the detailed proprietary segmentation tables that underpin our full forecast. For program‑level sizing, supplier benchmarking outputs and configurable NPV models, request the full report on the PW Consulting report page to unlock the complete data package and decision support assets.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com