

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
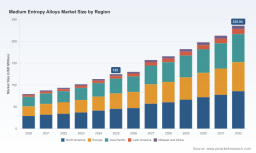
PW Consulting: Worldwide Medium Entropy Alloys Market Set to Reach USD 235.94 Million by 2032, Backed by a 9.5% CAGR

Worldwide Medium Entropy Alloys Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting's newest market study — Worldwide Medium Entropy Alloys Market (base year 2025, forecast 2026–2032) — arrives at a pivotal inflection for materials-intensive industries. With the sector forecast to expand at a compound annual growth rate of 9.5% through 2032 and the global market more than set to nearly double over the forecast window, this report translates macro momentum into boardroom-ready actions for 2026 planning cycles. Our objective here is to summarize the strategic value of the research for senior executives and investment committees while preserving the report’s proprietary segment-level detail for subscribers and qualified stakeholders.
Worldwide Medium Entropy Alloys Market
Macro snapshot that matters for 2026 planning
Medium entropy alloys (MEAs) have moved beyond academia into commercial engineering by combining tailored multi-component chemistries with scalable processing routes such as powder metallurgy and additive manufacturing. PW Consulting’s topline market model — built on historical sales (2020–2025) and a bottom-up segmentation of demand drivers — shows consistent expansion through 2025 and projects robust growth across the 2026–2032 forecast horizon. The combination of accelerated adoption in high-performance applications and ongoing supply-side consolidation drives the 9.5% CAGR that underpins strategic scenarios in the report.
Worldwide Medium Entropy Alloys Market
Key takeaways for financial planning: the market today represents a distinct and investable vertical with reliable growth characteristics suitable for multi-year capex allocation, targeted M&A, and partnership playbooks. Scenario layers in our modelling quantify sensitivity to raw material swings, regulatory friction, and technology adoption rates — inputs that will directly influence operating plans and procurement strategies in 2026.
Worldwide Medium Entropy Alloys Market
What the report delivers — practical, executable intelligence
- Actionable market architecture: A clear taxonomy of MEA subtypes, manufacturing pathways, and application clusters mapped to buyer pain points and certification milestones.
- Decision-centric forecasting: Base, upside, and downside scenarios that translate macro drivers (cost inflation, commodity access, regulation) into likely revenue outcomes at enterprise and portfolio levels.
- Supply-chain heat maps: Risk-ranked supplier ecosystems, chokepoint analysis for critical elements (nickel, cobalt, chromium, titanium), and playbooks for supplier diversification and secured sourcing.
- Technology & product roadmaps: Comparative assessment of powder metallurgy, casting, thermomechanical processing, and additive manufacturing readiness, including commercialization timelines and capex intensity estimates.
- Regulatory and sustainability overlay: Compliance stress-testing and CO2 footprint mitigation strategies, including the role of recycled stainless and nickel scrap in reducing lifecycle emissions.
- M&A and partnership playbook: Target profiles, integration risks, and value-capture levers for acquirers seeking scale, IP, or upstream raw-material control.
- Commercial go-to-market templates: Pricing pressure matrices, channel strategies for industrial OEMs, and buyer persona frameworks tailored to aerospace, transportation, and power-generation procurement cycles.
Why this matters for 2026 decisions
Enterprises face three concentrated choices in 2026: deepen vertical integration, buy capability through M&A, or partner selectively to access new alloy formulations and processing know-how. Each path has materially different capital and operational implications; our report quantifies these in ways that allow CFOs and strategy teams to stress-test ROI under realistic market dynamics. Specific strategic levers highlighted include:
- Procurement hedging and indexation clauses to offset nickel and cobalt price volatility — a material input risk in MEA manufacturing.
- Investment in recycling and circularity to reduce CO2 footprints and buffer commodity price cycles; our modelling demonstrates the trade-offs between primary and recycled feedstocks in capex and lifecycle emissions.
- Accelerated adoption of computational alloy design and co-development partnerships with organizations specializing in model-driven alloy discovery to reduce time-to-market for high-value formulations.
- Targeted capability builds in additive manufacturing to capture premium unit economics in low-volume, high-spec applications.
Supply-side realities and sustainability trade-offs
Upstream exposure is the single largest operational risk in MEA commercialization. Production of key alloying elements remains geographically concentrated, creating geopolitical and logistics tail risks that are highly relevant to 2026 capital and inventory strategies. Environmental and material safety regulations are tightening in many jurisdictions, increasing compliance costs for alloy producers — a dynamic the report models explicitly.
On the opportunities side, circular feedstocks present both cost and environmental advantages. Our sustainability analysis synthesizes academic and market data to show that the incorporation of recycled stainless steel and nickel alloy scrap can lower carbon intensity meaningfully. For context, market-observed scrap channels trade within a broad price band; leveraging these streams can be both an emissions and cost mitigation strategy as companies plan for new product lines and supplier contracts in 2026.
Competitive landscape — positioning the industry’s leaders
The market remains moderately concentrated among established specialty metallurgy and advanced materials suppliers. PW Consulting’s competitive review profiles incumbents and challengers across capability vectors — alloy design, production scale, certification experience, and route-to-market. Highlights include:
- Carpenter Technology Corporation: Strong legacy in high-performance alloys and an established footprint in aerospace and defense supply chains. Their position makes them a logical partner or acquirer for firms seeking aerospace certification pathways.
- ATI Inc. (Allegheny Technologies): Deep expertise in specialty alloy production and component manufacturing; strategically positioned to integrate downstream fabrication with novel MEA formulations.
- Haynes International: Niche strength in nickel- and cobalt-based alloys; well-suited to applications demanding extreme corrosion and high-temperature resistance.
- Sandvik AB and VDM Metals: European players with integrated R&D and production capability, attractive for partnerships that require rapid scale-up and EU-compliant supply chains.
- Hitachi Metals (Proterial), Stanford Advanced Materials, Matexcel, MSE Supplies: A mix of specialty powder suppliers and materials distribution networks that accelerate adoption in additive manufacturing and research-driven product pipelines.
- QuesTek Innovations: Representative of a new class of computational alloy design specialists — high strategic value for firms looking to compress alloy development cycles and derisk application-specific performance.
Collectively, the top-tier firms exert meaningful influence over price, standards, and certification practices. The market’s three- and five-firm concentration dynamics imply that strategic partnerships or selective M&A can shift competitive balance — an insight the report quantifies under multiple commercialization timelines.
How to use this report in 2026 planning cycles
Strategists and procurement leads should use the report to: (1) set realistic revenue and margin guardrails for new MEA product launches; (2) develop sourcing playbooks that explicitly model commodity shocks; (3) evaluate make-versus-buy decisions with lifecycle emissions and certification timelines embedded; and (4) identify M&A targets where engineering capabilities or certified production lines accelerate market entry.
Investment committees and corporate development teams will find the report’s scenario outputs especially useful when aligning capital approval thresholds to realistic commercialization risk curves. For R&D and product teams, the comparative technology readiness assessments and supplier scorecards create a prioritized list of development partnerships that balance scientific novelty with manufacturability.
What we intentionally withhold — and why
In line with our “teaser” approach to this announcement, PW Consulting is publishing the strategic implications and methodological framework broadly while preserving proprietary, granular segmentation tables and supplier-level financial models for subscribers. The full report contains detailed forecasts by region, application, and alloy type, supplier scorecards with performance indicators, and transaction-ready M&A dossiers — elements that are available through the official report access channels and designed to support procurement negotiations and investment due diligence.
Next steps for executives
- Download the executive summary and scenario dashboard to benchmark current plans against our base and stress scenarios for 2026–2032.
- Schedule a strategic briefing with PW Consulting to walk through supplier scorecards and the bespoke risk simulation tailored to your portfolio.
- Initiate a short-list process for computational alloy design and AM partners using the supplier archetypes profiled in the report as selection filters.
Medium entropy alloys create a rare combination of technical upside and commercial defensibility for companies that move early and with clarity. The decisions you make in 2026 about sourcing strategy, technology partnerships, and capital allocation will define competitive positioning for the next decade. PW Consulting’s Worldwide Medium Entropy Alloys Market report equips leaders with the macro foresight, tactical tools, and risk analytics required to convert materials innovation into sustained business advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com