

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Central Nervous System (CNS) Stimulants Market to Rise from USD 31.35 Billion in 2025 to USD 47.92 Billion by 2032 at a 6.25% CAGR

Worldwide CNS Stimulants Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
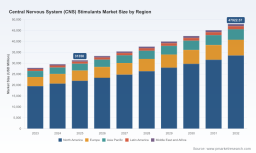
PW Consulting’s forthcoming Worldwide Central Nervous System (CNS) Stimulants Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes interoperable quantitative forecasts and qualitative strategic frameworks designed to inform executive decision-making in 2026. Our model projects the global CNS stimulants market to expand at a compound annual growth rate (CAGR) of 6.25% across the 2026–2032 forecast window. Measured in USD (Million), the market has climbed steadily from the mid-2020s and is projected to continue that trajectory through 2032 under our central case assumptions.
Worldwide Central Nervous System (CNS) Stimulants Market
Why this matters to leaders in 2026
- Strategic timing: 2026 is a pivotal year for product launches, reformulation rollouts, and contract negotiations. The combination of regulatory updates and adjusted aggregate production quotas means supply-side decisions made now will determine access and market positioning over the next biannual planning cycle.
- Portfolio resilience: Manufacturers, generics players, and speciality biotech firms must manage a dual challenge — sustaining supply for established ADHD and narcolepsy treatments while selectively investing in differentiated delivery systems, prodrugs and lifecycle extensions that protect value.
- Reimbursement reshaping: Policy initiatives and pilot pricing models introduced in late 2025 and early 2026 are increasing payer scrutiny of high-use CNS categories. Companies that can articulate clear efficiency and adherence cases will have leverage in formulary negotiations and value-based contracting pilots.
Market trajectory — what the headline numbers tell us
PW Consulting’s top-line view is purposefully straightforward: after a period of steady expansion through the early 2020s, the CNS stimulants market reached approximately USD 31,350 Million (base year 2025). Our 2026 baseline positions the market above USD 33,300 Million, with the model compounding annually at 6.25% to reach a mid-2030s range that reflects continuity of demand, constrained but improving supply dynamics, and incremental product differentiation. The forecast is scenario-programmed to reflect regulatory shocks, quota adjustments, and varying uptake rates for new formulations.
Worldwide Central Nervous System (CNS) Stimulants Market
What’s driving growth — structural and tactical factors
- Persistent clinical demand: ADHD and narcolepsy remain the primary clinical anchors for stimulant use globally. Demographic trends, increasing diagnostic awareness in certain markets, and adherence-improving delivery platforms underpin base demand.
- Formulation innovation: Extended-release, delayed‑release, transdermal and prodrug approaches are creating premium niches with margin resilience, even as generic competition intensifies in immediate‑release segments.
- Supply-side dynamics: API concentration and episodic shortages have contributed to volatile availability for amphetamine-based products. This creates both risk and opportunity — premium pricing for reliable supply and incentives for near-shore or dual-source strategies.
- Regulatory and policy momentum: Recent regulatory actions and enforcement levers are altering label requirements, manufacturing oversight, and aggregate production quotas — factors that materially affect production planning and time-to-market for reformulations.
Regulatory and supply landscape — 2025–2026 developments that shape 2026 choices
- Labeling updates: In mid-2025 regulators mandated expanded warnings for certain extended‑release amphetamine and methylphenidate products addressing pediatric safety risks. This alters risk communication strategies, pediatric labelling plans, and clinical trial design for pediatric submissions.
- Quota adjustments: Aggregate production quotas for key stimulants were revised upward in late 2025, responding to manufacturer requests and market shortages. While quota increases can relieve near-term supply pressure, they also formalize manufactured volumes and therefore influence inventory and pricing strategies.
- Quality surveillance and generics assurance: Public sampling and quality confirmations for certain generic extended‑release tablets in early 2026 have moderated some manufacturer risk, but persistent API sourcing constraints mean shortages may continue to be episodic.
- Reimbursement scrutiny: Emerging CMS pricing models and international cost-containment pilots have targeted categories with large utilization footprints; CNS stimulants are on that roster. Companies should prepare differentiated evidence on adherence, clinical outcomes and health economics to safeguard access.
Competitive landscape — what incumbents and challengers are prioritizing
The CNS stimulants arena is a mixed-structure market: concentration is meaningful but not absolute. Leading players command a substantive share of the market while a broad base of generics and niche developers exert pricing and innovation pressure. Our market concentration metrics indicate a moderate level of market share clustering among the top firms, underscoring both incumbent influence and material room for challengers with differentiated value propositions.
Worldwide Central Nervous System (CNS) Stimulants Market
Across the competitive set, strategic priorities diverge:
- Established originators are defending brand equity through lifecycle management — extended-release variants, label expansions where possible, and targeted patient support programs.
- Large generics manufacturers focus on scale, supply reliability and rapid launch readiness when innovator exclusivities lapse.
- Specialty and emerging firms are pursuing technical differentiation — prodrugs, novel delivery systems (including transdermal and delayed-release morning/evening dosing), and pediatric-friendly formulations that respond to new safety labelling demands.
- Manufacturers with integrated manufacturing footprints or diversified API sourcing are converting supply reliability into commercial advantage during periods of constrained availability.
Practical implications and action playbook for 2026
PW Consulting recommends a pragmatic, multi-track approach for corporate leadership, market-access teams and manufacturing strategists:
- Stress-test supply chains now. Scenario-planning should model quota volatility, API disruptions and quality sampling outcomes. Contingency funds for dual‑sourcing, contract manufacturers, and strategic inventory buffers are prudent.
- Prioritize formulary evidence. Prepare concise, payer-focused dossiers that link treatment adherence (supported by differentiated delivery systems) to measurable healthcare utilization reductions.
- Defend margins with targeted innovation. Invest selectively in delivery-platform upgrades and prodrug candidates that create clinically defensible differentiation and delay commoditization.
- Use M&A and capacity partnerships tactically. Strategic bolt-ons that add API capacity, regulatory dossiers, or complementary delivery technologies can be executed with rapid payback in a constrained supply environment.
- Engage regulators proactively. Early dialogue around pediatric labeling implications, post-marketing safety commitments, and quality surveillance programs reduces surprise and shortens approval pathways for lifecycle innovations.
What PW Consulting’s report provides (practical deliverables)
Our full report is constructed to be operationally useful for teams mobilizing in 2026. Key elements include:
- Proprietary forecast model (2026–2032) with scenario toggles (regulatory shock, supply disruption, high/low uptake) and downloadable outputs for integration into corporate financial planning.
- Competitive scorecards and capability heatmaps for the leading and mid‑tier firms, highlighting R&D pipelines, supply footprints, regulatory posture and commercial reach.
- Supply-chain risk matrix and API sourcing map, prioritized by disruption risk and mitigation options.
- Regulatory tracker with timelines, likely labeling impacts and recommended submission strategies aligned to current policy changes.
- Commercial playbooks for market access negotiations, pricing defense tactics, and launch sequencing for differentiated formulations.
What we are intentionally withholding here — and why
In keeping with a “trailer” approach, this announcement emphasizes strategic value and the report’s practical utility while omitting granular regional, drug-type, and indication-specific revenue breakdowns. Those detailed tables, company-level revenue splits, and activation maps are included in the full report and interactive models available through PW Consulting. The goal is to provide decision-makers enough strategic insight to prioritize internal planning while inviting teams to access the full data suite for execution-level actions.
Final note — how to use this intelligence in 2026
For 2026 planning cycles, the imperative is to convert market insight into operational decisions within a tightened regulatory and supply context. Firms that systematically align supply resiliency, payer evidence, and targeted innovation will convert competitive pressure into sustainable advantage. PW Consulting’s report equips leadership teams with the scenarios, tools and tactical playbooks needed to do that work with confidence.
For access to the full forecast model, company scorecards, and region-by-indication detail that underpin our recommendations, refer to the PW Consulting report landing page and request the comprehensive dataset and briefings tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com