

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mobile Unified Communications & Collaboration Market to Grow at 17.52% CAGR (2026–2032), Reaching USD 85,994.92 Million by 2032

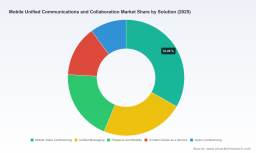
Worldwide Mobile Unified Communications and Collaboration Market: Strategic Imperatives for 2026
Executive Snapshot
PW Consulting today releases its authoritative market study, Worldwide Mobile Unified Communications and Collaboration Market (base year 2025, forecast 2026–2032). The research documents a multi-year expansion that accelerated through the mid-2020s: global market size increased from approximately USD 11.8 billion in 2020 to nearly USD 27.8 billion by 2025, and is projected to reach roughly USD 33.4 billion in 2026. Under our central forecast the market grows at a compound annual growth rate of 17.52% across the 2026–2032 horizon, culminating in an addressable market that exceeds USD 85 billion by 2032.
Worldwide Mobile Unified Communications and Collaboration Market
Why this report matters to 2026 enterprise decision-makers
- Timing and tempo: The near-term surge in demand for mobile-first collaboration capabilities coincides with an inflection in network investments and regulatory activity. C-suite teams that align vendor selection, network architecture, and procurement windows with this momentum will capture disproportionate value.
- Risk-calibrated scaling: Rapid growth is accompanied by rising concentration—the top vendors now control a meaningful share of market revenue—making vendor diversification, integration flexibility, and contractual safeguards essential to manage lock-in and service continuity.
- Operational readiness: The shift from desktop-centric UC to mobile-native experiences adds new security, compliance, and integration vectors. Decisions made in 2026 on identity fabrics, endpoint management, and network QoS will materially influence total cost of ownership over the next investment cycle.
What the report delivers (practical, decision-focused content)
- Executive playbooks: A procurement checklist, contract negotiation levers, and migration roadmaps tailored for phased migration to mobile-first UC platforms.
- Vendor scorecards and selection matrices: Comparative frameworks that weigh strategic fit, integration risk, AI capability, channel ecosystem, and enterprise-grade support—designed to shorten vendor evaluation from months to weeks.
- Network and operations blueprints: Guidelines for hybrid deployments (cloud + on-prem), carrier integration patterns, edge compute placement, and QoS profiles that map to typical enterprise traffic mixes.
- Security, compliance and resiliency frameworks: Practical controls and compliance pathways for data sovereignty, secure voice/video signaling, and incident response—aligned to contemporary regulatory shifts and disaster reporting obligations.
- Commercial models and TCO scenarios: Comparative TCO analyses across cloud-native, managed, and hybrid UC approaches; sensitivity analyses for seat growth, AI add-ons, and international expansions.
- AI readiness and roadmap templates: A phased capability approach for adding agentic and assistive AI to contact centers and collaboration flows without amplifying operational risk.
Market dynamics: Forces shaping vendor and buyer strategies in 2026
Three interlocking trends dominate the strategy landscape.
Worldwide Mobile Unified Communications and Collaboration Market
- Network and infrastructure evolution: Significant investments in multi-gigabit access and node densification—driven by cable operator DOCSIS upgrades, distributed access architectures, and ongoing mid-band spectrum planning—are materially improving mobile UC performance and enabling richer mobile video and low-latency voice experiences.
- Regulation and sovereignty: Policymakers are actively reshaping the operating environment. Notable examples include changes to disaster reporting requirements and sustained policy work around mid-band spectrum allocation; regional investments in sovereign communications infrastructure continue to influence vendor selection and deployment topology for global enterprises.
- Platform intelligence and consolidation: Providers are embedding AI into meeting experiences, agent workflows, and automated contact-center services. This infusion of intelligence accelerates differentiation but also changes procurement criteria—buyers increasingly evaluate vendors on AI governance, data residency, and model retraining controls as much as on classic feature sets.
Competitive landscape — who matters and why
The market is served by a mix of hyperscale platform providers, traditional enterprise communications vendors, cloud-native UCaaS players, and network operators. Our analysis shows a moderate-to-high level of concentration: market share is moving toward established platform leaders even as nimble cloud vendors capture new greenfield opportunities in SMB and mid-market segments.
Worldwide Mobile Unified Communications and Collaboration Market
- Microsoft Corporation — Positioned as a platform anchor, Microsoft leverages a broad productivity ecosystem to embed mobile UC within workflow and identity. Recent AI-enhanced feature releases deepen the value proposition for enterprises on premium suites.
- Cisco Systems, Inc. — Cisco combines device-level and software integration to appeal to large enterprises with demanding security and hardware interoperability requirements. Strategic acquisitions to add document workflows and contact-center capabilities signal an emphasis on end-to-end engagement stacks.
- Zoom Video Communications, Inc. — Zoom continues to compete on simplicity and developer extensibility, extending mobile-first experiences into unified voice and workspace offerings designed for rapid user adoption.
- RingCentral, 8x8, Nextiva and other cloud-native UCaaS vendors — These providers emphasize agility, channel ecosystems, and verticalized feature packs (including contact-center integrations), competing on go-to-market speed and packaged operational services.
- Traditional enterprise vendors (Avaya, Mitel, Alcatel-Lucent Enterprise, NEC) — Their strengths are hybrid architectures and migration services for large, distributed estates where a phased approach to cloud adoption remains the practical reality.
- Telcos and network owners (Verizon and others) — Service providers are moving up the stack, offering bundled connectivity and UCaaS with quality guarantees; their uniquely positioned network assets and managed services appeal to enterprises prioritizing SLA-backed experiences.
Recent market moves to watch
- Vendor feature momentum: Major vendors are accelerating embedded AI releases and agentic capabilities to improve meeting outcomes and customer engagement. Expect AI packaging and consumption models to become negotiation points during contract renewals in 2026.
- Partnerships and distribution plays: Network operators are bundling UC offerings into public-sector and large-enterprise contracts—creating integrated offers that bundle connectivity, managed services, and UCaaS under a single supplier relationship.
- Portfolio modernization by legacy providers: Long-standing vendors are refactoring portfolios for hybrid cloud deployments and are emphasizing continuity controls to keep existing enterprise customers on migration paths that reduce disruption.
Key implications and recommended actions for 2026
- Adopt a “mobile-first, network-aware” strategy: Treat mobile UC not as a set of device apps but as an architectural layer that requires explicit design for network quality, edge compute, and session continuity.
- Negotiate for AI governance and cost predictability: As vendors bundle AI features, buyers must secure transparent pricing and contractual commitments on data usage, model updates, and performance SLAs.
- Prioritize integration and exit flexibility: Insist on standards-based APIs, documented migration paths, and phased pilots to limit vendor lock-in and reduce migration risk across a multi-year technology refresh cycle.
- Embed regulatory and resilience requirements into procurement: With changes to disaster reporting and sovereign infrastructure builds, compliance and continuity clauses should be explicit procurement requirements rather than afterthoughts.
- Plan for a two-tier deployment approach: Combine rapid user enablement for mobile collaboration with a deliberate backend modernization program (identity, session management, contact-center orchestration) to balance speed and long-term resilience.
How PW Consulting’s report helps you act
This report is designed as a near-operational artifact: it translates market trajectories into executable decisions. Buyers will find playbooks to re-platform contact centers, scorecards to evaluate AI-enabled meeting capabilities, network integration schemas, and contractual language templates to protect entitlements and data governance. For strategy teams, the report offers scenario-based forecasts and investment wallets tied to key pivot points (regulatory milestones, spectrum releases, and major vendor roadmap shifts).
Trailer principle: what we show and what we reserve
In keeping with our role as a strategic adviser, this release highlights market scale, growth trajectory, competitive contours, and actionable recommendations to support 2026 decisions. To preserve the commercial utility of our primary research and to encourage rigorous vendor selection and procurement practice, detailed segmented breakouts (regional allocations, solution-by-solution revenue lines, and vertical-specific dollar breakdowns) are purposefully reserved for the full report and dataset. These granular tables, model files, and regional scenario analyses are available on the report landing page.
Next steps
Enterprises preparing procurement cycles, IT modernization roadmaps, or contact-center transformations for 2026 should use this report as a strategic north star. For access to the complete analytical dataset, vendor-by-vendor benchmarks, shaded scenario models, and procurement templates, please consult the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com