

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft Brake Calipers Market to Rise from USD 592.28 Million in 2025 to USD 1,022.99 Million by 2032 at an 8.12% CAGR

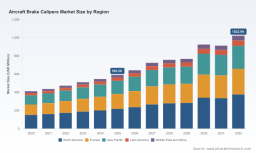
Worldwide Aircraft Brake Calipers Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As aviation stakeholders prepare for a pivotal planning cycle in 2026, PW Consulting’s latest market study on the Worldwide Aircraft Brake Calipers Market offers a concise, decision-focused intelligence package. Grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study documents a market that expanded from approximately USD 412.5 million in 2020 to USD 592.3 million in 2025. Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of 8.12% through 2032, reaching roughly USD 1,023.0 million by the end of the forecast period. This briefing highlights the implications of those dynamics for strategic planning, while directing experienced readers to the full report for granular segment and competitive tables reserved for subscribers.
Worldwide Aircraft Brake Calipers Market
Why this matters for 2026 strategic planning
-
Recovering traffic profiles, fleet modernisation and renewed aftermarket activity are shifting capital and service priorities across OEMs, MROs and component suppliers. The pace implied by an ~8.1% CAGR demands active portfolio and capacity decisions in the next 12–18 months.
Worldwide Aircraft Brake Calipers Market -
Concentration is meaningful: the market shows a high degree of vendor clustering at the top (three-firm and five-firm concentration measures indicate a consolidated competitive landscape). That concentration alters bargaining dynamics, M&A calculus and aftermarket capture strategies.
Worldwide Aircraft Brake Calipers Market -
Certification and materials choices (lightweight aluminium/titanium architectures versus carbon-ceramic high-performance options) are becoming strategic differentiators rather than purely engineering decisions — with direct bearings on product roadmaps, supplier selection and total life-cycle cost models.
Core demand drivers and near-term constraints
-
Fleet growth and replacement cycles: Airlines renewing narrow- and wide-body fleets and military platforms modernising braking systems are primary demand sources. As operators prioritise fuel-efficiency and weight reduction, caliper design trade-offs influence procurement specifications.
-
Aftermarket and MRO tailwinds: Increased utilisation and a stretched supply chain elevates demand for component repairs, FAA-PMA replacements and aftermarket-certified caliper parts. The market’s aftermarket segment represents a strategic margin pool for firms that can secure OEM approvals or strong distribution partnerships.
-
Regulatory & certification complexity: FAA advisory circulars and technical standard orders remain binding constraints that shape product development timetables and testing budgets. Regulatory compliance for rejected takeoff (RTO) and landing performance is a gating item that directly affects time-to-revenue for new caliper designs.
-
Material and supply-chain volatility: Titanium and carbon-ceramic composites offer performance upside but come with supply, cost and manufacturing complexity. Aluminium alloys still dominate where balance of cost, weight and manufacturability matter.
Technology, materials and the electrification vector
Three technology threads are set to re-shape competitive advantage through 2032. First, material engineering — the selective use of titanium and carbon-ceramic composites — enables higher thermal tolerance and lower life-cycle weight but requires investments in process control and supplier relationships. Second, actuation systems are evolving: while hydraulic calipers remain the incumbent workhorse, electric brake actuation architectures are gaining attention for integrated brake-by-wire functionality and potential maintenance advantages on next-generation platforms. Third, digital enablement — sensorised calipers, prognostics and integrated health-management — is emerging as a service enabler for MROs and fleet operators seeking to reduce unscheduled removals and extend component intervals.
Regulatory and certification landscape
-
FAA AC 25.735-1 and related airworthiness guidance continue to frame dynamic testing and wear-limit regimes used in certification programs. Familiarity with these advisory circulars and their interpretation is table stakes for entering transport-category platforms.
-
TSO-C26d establishes minimum performance and dynamic test protocols for transport wheels and brakes. Suppliers targeting large commercial platforms should factor the cost and schedule impact of dynamic testing into 2026 development budgets.
Competitive landscape — who matters and why
The market is shaped by a mix of global OEM-tier incumbents and specialist niche players. Leading landing and brake systems integrators, multi-national aerospace suppliers, and specialised general aviation manufacturers each play distinct roles across OEM sales, aftermarket spares and MRO channels.
-
Safran Landing Systems (France) — Positioned as a global leader in integrated landing and braking systems for large commercial platforms. Its portfolio breadth (complete wheels-and-brakes systems) and programme level relationships with large OEMs give it strategic leverage on both new-build and aftersales capture.
-
Meggitt Aircraft Braking Systems / Parker Meggitt (UK/USA) — Strong in business, regional and military segments, with an installed-base focus and vertical capability through component subsidiaries. Their depth in both products and repair networks supports resilient aftermarket revenue.
-
Collins Aerospace (RTX Corporation) and Honeywell Aerospace (USA) — Major diversified aerospace suppliers with cross-platform reach. They combine product engineering, integration experience and OEM relationships that make them natural partners for platform-level contracts and integrated actuation solutions.
-
Tier 2 and specialist players — Cleveland Wheel & Brake Systems, Grove, NMG Aerospace, Nasco and FAA-PMA suppliers — are critical in the general aviation, business-jet and aftermarket replacement ecosystems. Their agility and certification portfolios make them the go-to for MROs and operators seeking rapid turnarounds and approved spares.
-
Smaller OEMs and niche manufacturers (Beringer Aero, MATCO, Jay-Em, Rapco Fleet Support, Aerobrake) continue to serve light aircraft and experimental markets, preserving high-margin niches and enabling platform-specific innovation.
Notably, the market concentration metrics underline that a small number of firms capture the lion’s share of value — an important data point for executives weighing partnership, pricing and defensive M&A options.
Recent developments worth watching
-
April 2026: Cleveland Wheel and Brake Systems was awarded a firm fixed-price purchase order for wheel and brake components — a concrete reminder that government and defence-linked procurement remains a current source of demand and cash flow for component suppliers.
-
Across the supplier community, announcements around electric actuation pilots, sensorised brake trials and supply-chain safeguards are accelerating. These are early indicators of where aftermarket service models and certification investments will concentrate over the next 24 months.
Practical implications and recommended 2026 actions
-
Prioritise product-roadmap triage. Allocate investment to designs that balance near-term certification feasibility with medium-term weight and thermal gains (e.g., selective use of titanium or hybrid material architectures).
-
Define an aftermarket capture plan. For OEMs and distributors, securing maintenance contracts and FAA-PMA approvals can generate high-margin revenue and stabilise order books during new-build cyclicality.
-
De-risk certification paths early. Incorporate FAA advisory circular and TSO testing requirements into programme budget and timeline planning to avoid costly rework and missed contract milestones.
-
Assess M&A and partnership opportunities against concentration dynamics. For mid-tier players, targeted acquisitions or long-term supply agreements with top-tier integrators can accelerate scale and improve bargaining power.
-
Invest in digital prognostics. Brakes-as-a-service pilots and health-management offerings can reduce operator on-wing time and create recurring revenue streams tied to predictive maintenance.
-
Hedge material exposure. Create dual-sourcing strategies for critical alloys and composite inputs to limit price volatility and supply disruptions.
What the PW Consulting report delivers (practical, actionable contents)
The full report is structured to support commercial and technical decision-making. Key deliverables include:
-
Bottom-up market sizing and validated forecast model (2026–2032), with scenario sensitivity and demand drivers by fleet type and actuation architecture.
-
Competitive intelligence dossiers on leading suppliers, including capability maps, go-to-market models, manufacturing footprints and MRO channel analysis.
-
Regulatory and certification playbook summarising test regimes, timeline implications and typical cost buckets for compliance (including guidance tied to FAA AC and TSO requirements).
-
Supply-chain risk matrix and raw-material exposure analysis with mitigation options tailored for procurement and operations leaders.
-
Strategic growth playbook: M&A screening templates, pricing levers, aftermarket commercial models and a 12–36 month implementation roadmap.
-
Proprietary scenario analyses and an interactive financial model to stress-test capital allocation, production scale-up and aftermarket capture strategies.
To preserve the report’s commercial value for subscribing clients, we refrain from reproducing detailed segment-level shares and company-specific revenue figures in this release. The full dataset and downloadable models are accessible on the report landing page.
How to use this intelligence in 90 days
-
30 days — Rapid internal alignment: Share the executive brief with product, procurement and commercial leads and map current programs against certification timelines highlighted in the report.
-
60 days — Tactical decisions: Finalise supplier hedging arrangements for critical materials, and prioritise a single pilot for digital prognostics or electric-actuation integration.
-
90 days — Strategic actions: Execute an M&A screening or partnership outreach to close capability gaps identified in the competitive intelligence dossiers.
Next steps
For procurement leaders, OEM product strategists, private equity investors and MRO executives preparing budgets and bids in 2026, the full PW Consulting report provides the granular segmentation, competitor revenue breakouts and downloadable forecast model necessary to convert insight into action. Access to the complete dataset and bespoke advisory support is available via the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com