

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Linear Position Sensors Market to Expand at 6.45% CAGR (2026–2032) as Asia Pacific Emerges as Market Leader

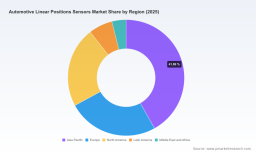
Worldwide Automotive Linear Position Sensors Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As vehicle architectures evolve toward greater electrification, automation and tighter emissions control, the humble linear position sensor has become a strategic component rather than a commodity. PW Consulting’s latest market study projects continued, steady expansion of the global automotive linear position sensors market during the 2026–2032 forecast window. The sector’s trajectory is underpinned by a 6.45% compound annual growth rate (CAGR) across the forecast period and a market that has grown from the low‑thousands in revenue back in 2020 to an estimated US$4.3 billion in 2025, with a projected rise toward approximately US$6.66 billion by 2032.
Worldwide Automotive Linear Positions Sensors Market
This briefing distills the report’s most actionable implications for corporate strategy in 2026. It highlights where executive teams should prioritize R&D and sourcing, how procurement and product groups can de‑risk supply, and why M&A and partnership playbooks need to account for both technological and regulatory tailwinds.
Worldwide Automotive Linear Positions Sensors Market
Why this market matters in 2026
- Performance and compliance intersection: Linear position sensors are now integral to powertrain efficiency, transmission automation, advanced braking and steering control, and emissions management. Design choices at the sensor level materially affect fuel economy and compliance outcomes.
- Technology polarization: Magnetic (Hall‑effect) and inductive solutions are consolidating as the primary approaches. Each class of solution brings tradeoffs in cost, tolerance to harsh environments, packaging and calibration complexity—factors that reshape supplier selection and OEM design choices.
- Commercial leverage points: With the market concentrated among a small set of global Tier‑1s (a top‑five concentration that indicates measurable aggregation but room for challengers), opportunities exist for focused suppliers to win design‑ins via platform attachments, software complements and reliability differentiation.
Strategic implications for OEMs and Tier‑suppliers
For senior leaders planning capital allocation and product roadmaps in 2026, the following implications should be prioritized:
Worldwide Automotive Linear Positions Sensors Market
- Align sensor selection with system‑level KPIs: Decisions between Hall‑effect, inductive and contact‑based solutions should be made at the subsystem level, not in isolation. Use system simulations to quantify lifecycle energy, calibration overhead and failure modes, and bake those into module cost models.
- Invest in software and diagnostics: Sensor hardware is increasingly commoditized; value accrues to firms that pair sensors with robust diagnostic algorithms, self‑calibration routines and predictive maintenance signals. These capabilities shorten warranty cycles and reduce field‑service costs.
- Strategic sourcing and dual‑sourcing: Given component criticality, adopt dual‑sourcing strategies that combine global Tier‑1 relationships with regional specialists to mitigate geopolitical, logistics and single‑point‑failure risks.
- M&A and partnerships lens: Mid‑sized players with differentiated inductive designs, ruggedized housings, or integrated IC capabilities are compelling bolt‑on targets. Pursue partnerships that accelerate time‑to‑market for safety‑critical applications rather than purely volume‑capture plays.
Market trajectory — what the macro numbers tell us
The aggregate market dynamics embedded in our analysis show a resilient growth path: from a multi‑billion‑dollar base in 2025 the market is poised to expand materially through 2032. The 6.45% forecast CAGR reflects a mix of steady unit growth driven by higher electronic content per vehicle, and price mix improvements from higher‑value sensing solutions that include smarter ICs and diagnostic features.
Historical performance through 2025 shows recovery and expansion following the supply disruptions of the early 2020s, and the forecast assumes continued adoption of advanced transmissions, active chassis systems and electrified drivetrains that demand precise linear feedback. Importantly, growth is not uniform: pockets of above‑average expansion will appear where regulatory pressure and advanced vehicle architectures coincide—creating corridors of strategic priority for investment.
Key demand drivers and risk factors
- Drivers: Emissions regulations, increased electrification and the proliferation of automated transmissions and advanced driver assistance systems (ADAS) are the primary demand accelerants. Sensors that support throttle control, exhaust actuation and transmission automation will see persistent demand pressure.
- Technological levers: Improved magnetic ICs, miniaturized inductive architectures and contactless sensing that tolerate metal targets and misalignment are shifting engineering preferences, especially in space‑constrained and harsh environments.
- Supply risks: Raw‑material pressures, specialized manufacturing capacity constraints and single‑sourced components present short‑to‑medium term risks. Firms should map supplier criticality and evaluate alternative technologies as hedges.
- Regulatory and commercial cyclicality: Emissions compliance cycles and global commercial vehicle retrofit programs can create demand phasing; scenario planning for tightening standards and for slower macro cycles is essential.
Competitive landscape — who matters and why
The market is anchored by a group of established global players with differentiated propositions across product breadth, systems integration and sensor IC capability. Our report evaluates each firm across engineering depth, manufacturing footprint, product portfolio (mechanical and magnetic), and go‑to‑market reach. High‑level positioning summaries include:
- Bosch (Germany, https://www.bosch-mobility.com): Global leader with wide portfolio across Hall‑effect and other linear solutions for pedals, suspension and transmission systems. Strengths lie in systems integration and scale manufacturing.
- Continental AG (Germany, https://www.continental.com): Broad position‑sensor portfolio focused on powertrain, chassis and safety systems; strong OEM relationships in both passenger and commercial vehicle segments.
- Honeywell International Inc. (United States, https://sensing.honeywell.com): Emphasizes non‑contact Hall‑effect devices and SMART Position Sensors for motion control in harsh duty cycles—priority partner for ruggedized applications.
- CTS Corporation (United States, https://www.ctscorp.com): Noted for both contacting and non‑contacting linear sensors, with a clear focus on pedal and emissions‑sensitive applications.
- Sensata Technologies (United States, https://www.sensata.com): Specializes in compact spring‑return and other space‑efficient designs for feedback in constrained installations.
- TE Connectivity (Switzerland/Ireland, https://www.te.com): Strong in steering and chassis sensors; notable for cross‑domain connector and sensor systems that ease integration.
- Infineon Technologies AG (Germany, https://www.infineon.com): Supplier of magnetic and Hall ICs that underpin many higher‑level sensor modules; a key enabler for smarter sensor electronics.
- Specialists (Piher, Littelfuse, Phinia, Vishay, Allegro, Novotechnik): These firms bring differentiated inductive, magnetostrictive or contactless solutions and are often preferred for unique packaging, customization or specialized commercial vehicle offerings.
Collectively, the top tier of suppliers account for a meaningful share of the market, producing an industry that is neither a pure oligopoly nor highly fragmented. This creates room for both scale players and niche innovators to co‑exist—if strategic plays are executed with clarity on IP, reliability and supply continuity.
Recent signals to act on (selected)
- Product innovation persists: January–March 2026 saw new Hall‑effect introductions with higher electrical stroke and tighter linearity and resolution—evidence that higher‑precision magnetic solutions are moving into mainstream motion‑control applications.
- Regulatory reinforcement: Ongoing emissions standards and efficiency programs continue to elevate the role of sensors in control loops—making early sensor selection a determinant of system compliance and lifecycle cost.
- Technology substitution opportunities: Inductive solutions are being positioned as cost‑effective, misalignment‑tolerant alternatives to LVDTs in several applications—creating choices for cost‑sensitive platforms.
What our full report delivers (operational contents)
PW Consulting’s full market study is designed as a decision‑readiness tool, not just a dataset. It contains:
- Granular demand forecasting models with scenario planning (base, accelerated electrification, and regulatory shock scenarios) that allow you to stress‑test capital and sourcing plans.
- Technology readiness and migration maps that show likely adoption pathways for Hall‑effect, inductive, magnetostrictive and contact‑based solutions across vehicle subsystems.
- Competitive scorecards and supplier heatmaps assessing engineering capability, capacity, geographic footprint and execution risk.
- Supply chain risk matrices and mitigation playbooks, including dual‑sourcing templates and alternative‑technology sourcing ladders.
- Commercial playbooks for OEMs and Tier‑suppliers covering design‑in strategies, cost‑to‑serve calculators, warranty provisioning models and service‑network implications.
- M&A screening framework and 18‑month integration checklists to help buyers prioritize bolt‑on targets that deliver immediate technological or go‑to‑market synergies.
How leading companies should use the report in 2026
- Product heads: Use the technology migration maps to set 24–36 month development priorities and to define feature roadmaps tied to diagnostics and IC integration.
- Procurement teams: Deploy the supplier heatmaps to create prioritized dual‑sourcing plans and to model total cost of ownership under different logistics and commodity scenarios.
- Strategy and corporate development: Use the M&A screening framework to identify targets that accelerate electrified powertrain or commercial‑vehicle automation capabilities.
- Regulatory and compliance functions: Leverage our scenario analyses to quantify the sensor‑level impact of pending emissions and efficiency standards on vehicle architectures and retrofit markets.
Final recommendation and next steps
In 2026, linear position sensors represent both an enabling technology and a competitive battleground. Executive teams should treat sensor strategy as cross‑functional—spanning product engineering, procurement, regulatory, and corporate development. Action priorities for the next 12 months should include:
- Initiate subsystem‑level TCO and reliability trade‑offs for Hall‑effect vs. inductive options on major platforms.
- Build dual‑sourcing plans that combine scale suppliers with regional specialists for critical applications.
- Prioritize investments in diagnostics and sensor IC integration to extend value beyond hardware.
- Use targeted M&A or partnerships to close capability gaps in ruggedized or space‑constrained sensor solutions.
For teams preparing budgets and strategic plans for 2026, the full PW Consulting Worldwide Automotive Linear Position Sensors Market report provides the detailed inputs, models and executable playbooks necessary to convert market growth and technological change into lasting competitive advantage. To access the complete forecast tables, supplier scorecards and strategic annexes, visit the report landing page and download the full document.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Linear Positions Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com