

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Charge Plate Monitor Market to Rise from USD 55.21 Million in 2025 to USD 80.22 Million by 2032 at a 5.48% CAGR — Asia Pacific Leads with USD 26.48 Million in 2025
By pmarketresearch, 2026-07-15
Worldwide Charge Plate Monitor Market: Strategic Insights to Shape 2026 Decision-Making
PW Consulting’s latest market brief on the Worldwide Charge Plate Monitor market synthesizes seven years of historical performance and a seven-year forecast to 2032, delivering the strategic context that procurement leaders, product managers, and investors need as they set priorities for 2026. The market has expanded steadily from a modest base in 2020 and is projected to grow at a mid-single-digit compound annual growth rate. Our analysis translates that trajectory into operational, go-to-market, and M&A implications while intentionally preserving the proprietary granularity of segment-level tables—access to the full dataset is available through the complete report.
Worldwide Charge Plate Monitor Market
Why this market matters in 2026
- Charge plate monitors are a small but strategically critical instrument class for industries where electrostatic discharge (ESD) control and ionizer performance verification are mission‑critical—semiconductors, flat panel displays, electronic assembly, medical devices, and aerospace among them. As device geometries shrink and contamination tolerance tightens, the monitoring and verification layer becomes not just quality assurance but an operational enabler.
- From 2020 through our base year of 2025 the total market expanded materially, and our forecast through 2032 reflects continued steady expansion—supported by capital expenditure growth in core end markets, replacement demand driven by regulatory and quality cycles, and incremental adoption in adjacent sectors such as life sciences cleanrooms.
- Regulatory and standards dynamics (notably ANSI/ESD STM3.1 and ANSI/ESD SP3.3) continue to codify the role of charge plate monitors in verification programs. Compliance is driving baseline demand among OEMs and contract manufacturers, while value‑added features—automation, programmability, and compact form factors—are creating premium tiers within the product landscape.
What the numbers tell us (and what we intentionally omit)
At the total‑market level, our model shows a clear and consistent expansion from the early 2020s into the next decade, reflecting a compound annual growth rate in the mid‑single digits. That macro trajectory supports conservative capital planning for 2026: buyers should budget for replacement cycles and modest unit demand growth, while vendors can prioritize software and service attachments to lift average selling prices.
Worldwide Charge Plate Monitor Market
PW Consulting deliberately presents these macro dynamics without disclosing the full set of segmental allocations in this release. We follow a ‘trailer’ approach here—demonstrating model robustness and strategic implications while guiding deeper stakeholder engagement through the full report, which contains the granular regional, type and application splits, scenario models, and downloadable financial tables.
Worldwide Charge Plate Monitor Market
Key strategic implications for 2026 decisions
- Procurement and CapEx planning: For 2026, procurement leaders should incorporate predictable refresh cycles for ESD verification gear into their CapEx roadmaps rather than treating charge plate monitoring as discretionary. Lifecycle budgeting that aligns instrument refresh with ionizer recalibration and cleanroom certification reduces unplanned downtime and measurement variance.
- Product innovation and differentiation: Vendors that win in 2026 will be those that convert test instrumentation into verification platforms—integrating programmable testing, automated logging, and simple connectivity into field‑friendly hardware. Collapsible and portable plate options already demonstrate demand for compact, on‑the‑go measurement in audit kits and production lines; the next wave is seamless data capture into factory analytics stacks.
- Service and recurring revenue: Given the steady hardware growth outlook, the most defensible margin improvement path for suppliers lies in services—calibration, audit subscriptions, software licenses for automated test sequences, and managed verification programs aimed at high‑risk production zones such as cleanrooms for medical device manufacturing.
- Risk-adjusted sourcing: Supply chain resilience remains important. Buyers should evaluate instrument vendors on calibration network depth, spare parts availability, and the ability to ship portable/benchtop replacements quickly—particularly for high‑mix electronics and life sciences customers where downtime penalties are significant.
Competitive landscape — who to watch (and why)
The market exhibits a moderate level of concentration. Leading vendors bring differentiated portfolios that combine longstanding instrumentation expertise with focused product lines for ESD verification. Key companies profiled in our analysis represent the breadth of incumbent strengths and emerging strategies:
- Advanced Energy (Trek / Monroe) — A U.S.‑headquartered incumbent offering advanced active charge plate monitors and a range of models tailored to ionization evaluation. Their portfolio emphasizes precision measurement of offset voltage and discharge times and is positioned to serve semiconductor fabs and high‑end assembly customers that demand repeatable, laboratory‑grade verification.
- Simco‑Ion, Technology Group — Known for programmable and automated testing instruments, Simco‑Ion targets ionizer performance evaluation across AC, pulsed DC and steady‑state DC technologies. Their systems appeal to manufacturers seeking integrated validation workflows and are increasingly used where automated test sequences must map directly into quality systems.
- SCS (Desco Industries) — Offers practical, portable monitors designed for on‑line ESD verification within EPA (ESD Protected Area) environments. Their products are frequently adopted by SMT lines and electronics assembly operations that prioritize ease of use and quick audits.
- Transforming Technologies (Warmbier) — With devices explicitly positioned to satisfy ANSI/ESD test protocols, this vendor focuses on field meters and verification tools commonly used for compliance testing in production and cleanroom contexts.
- Prostat Corporation — Their portable, collapsible plate assemblies are purpose‑built for audit kit usability and field verification; the company underscores the practical requirements of capacity, portability, and standards compliance for on‑site testing.
- Static Clean International — Distributors and specialists in portable handheld monitors, serving users who need rapid verification of ionizer balance and static decay in decentralized testing scenarios.
Across these providers, differentiation is increasingly determined by three axes: measurement fidelity, ease of integration into factory data flows, and after‑sales support (calibration and managed verification). In our view, vendors that bundle instrumentation with verification software and analytics will capture the most attractive margins and secure stronger enterprise relationships through 2026 and beyond.
Report contents — what PW Consulting delivers
The full Worldwide Charge Plate Monitor Market report is structured to be decision‑centric. It includes:
- Rolling historicals (2020–2025) and a seven‑year forecast (2026–2032) with scenario analysis tailored to demand shocks, standards changes, and technology substitution.
- A downloadable financial model in USD (revenue units in Million) that supports what‑if sensitivity testing against price, volume, and service attachment rates.
- Actionable buyer frameworks for procurement leaders, including total cost of ownership templates, calibration scheduling playbooks, and vendor evaluation scorecards.
- Go‑to‑market and product roadmap recommendations for vendors—covering platform features, service bundling, and channel expansion strategies—with example business cases showing margin and ARR improvements from service attachments.
- Supply chain risk maps and supplier due‑diligence checklists to help operations teams secure instrument availability and calibration continuity.
- Competitive benchmarking profiles and a technology feature matrix comparing actuation modes, programmability, portability, and data interfaces across key suppliers.
Practical 90‑day playbook for 2026
- For buyers: Initiate a verification audit that aligns instrument refresh with facility certification windows; build calibration cadence into supplier contracts; pilot a managed verification subscription with one strategic supplier to validate cost and uptime benefits.
- For vendors: Launch a minimal viable offering that packages a portable charge plate monitor with cloud logging and scheduled calibration services; prioritize API hooks for MES/QA integration to reduce enterprise friction.
- For investors: Screen targets for software‑attach potential, recurring revenue conversion, and channel depth—those are predictive indicators of margin expansion across our forecast horizon.
Methodology and confidence
Our dataset synthesizes primary interviews, vendor product specifications, and standards reference points (notably ANSI/ESD STM3.1 and SP3.3) to construct both cautious and upside scenarios. We assign high confidence to the directionality of core trends—steady market growth, increasing emphasis on verification automation, and the emergence of services as a margin lever—while the report retains the full breakdowns, segment tables, and model drivers for stakeholders who require line‑level inputs for budgeting or due diligence.
Next steps — how to get the full picture
This preview is calibrated to inform near‑term strategy while preserving the proprietary detail that delivers competitive advantage. PW Consulting’s full report includes the complete segmentation matrices, vendor scorecards, and an interactive financial model that business leaders can license for their internal planning. For decision teams preparing 2026 budgets, the report is a timely tool to convert market momentum into defensible plans.
Contact PW Consulting to request the full Worldwide Charge Plate Monitor Market report and schedule a briefing with our senior analyst team, who can tailor the findings into a bespoke workshop for procurement, engineering, or corporate development stakeholders.
For detailed analysis of this topic, please visit the official page: Worldwide Charge Plate Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Thoracic Drainage Devices Market to Reach USD 1,459.38 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Thoracic Drainage Devices Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide Thoracic Drainage Devices presents a forward‑looking, action‑oriented analysis designed to inform executive decisions in 2026. Anchored on a 2025 base year and projecting through 2032, the study quantifies a resilient market trajectory — from a 2025 market size of approximately USD 940 million to a pathway that surpasses USD 1.45 billion by 2032 under the base forecast, reflecting a compound annual growth rate of 6.48% across the 2026–2032 horizon. This press release summarizes the study’s strategic value, highlights critical industry dynamics, and outlines the practical tools executives can use immediately — while reserving the detailed segment tables and scenario spreadsheets for the full report.
Worldwide Thoracic Drainage Devices Market
Why this report matters for 2026
- Translate macro growth into portfolio prioritization: use the report to decide which thoracic drainage investments should be accelerated versus rationalized.
- Align R&D and regulatory timelines: understand how FDA 510(k) dynamics and electrical safety expectations for digital systems affect time‑to‑market.
- Mitigate short‑term supply and competitive shocks: learn which vendor changes and recalls create near‑term openings for market share capture or partnership.
- Target commercial models and contracting: use reimbursement and procedure coding intelligence to optimize hospital procurement and value‑based purchasing plays.
Market trajectory and strategic implications
The thoracic drainage devices market has demonstrated steady recovery and modernization over the past five years. After navigating pandemic‑era elective procedure fluctuations, market value reached around USD 940 million in 2025. PW Consulting’s base forecast projects a continuation of demand expansion, with the market exceeding USD 1.0 billion in 2026 and growing at a mid‑single‑digit CAGR (6.48%) to reach approximately USD 1.46 billion by 2032 under central assumptions.
Worldwide Thoracic Drainage Devices Market
Several structural drivers underpin this outlook:
Worldwide Thoracic Drainage Devices Market
- Persistent demand from post‑operative thoracic and cardiothoracic procedures and trauma care — procedural volumes and clinical practice patterns remain the primary demand anchors.
- Rapid adoption of digital chest drainage solutions that offer objective air‑leak monitoring, mobility benefits, and data capture for patient pathways; these product innovations command premium pricing and create upgrade cycles.
- Increasing focus on shortening length of stay and facilitating early ambulation, which favors compact, wearable and digital drainage systems with robust clinical evidence supporting safety and cost offsets.
- Regulatory and reimbursement environments that reward demonstrated outcomes and interoperability with hospital information systems, shaping procurement choices in high‑volume centres.
Competitive landscape — strategic reads on the leading players
The market’s competitive structure is moderately consolidated; the three largest players control a meaningful share, while the top five capture a majority of revenue. This mix creates both stability and opportunity for challenger brands.
- Becton, Dickinson and Company (BD) — As an entrenched supplier of chest tubes and drainage catheters, BD remains a strategic partner for health systems focused on procurement scale and trusted clinical familiarity. For executives: evaluate BD primarily as a platform partner for broad clinical adoption and bundled supply strategies.
- Getinge AB (Atrium) — Atrium’s product breadth across dry‑seal and water‑seal solutions positions Getinge well in hospitals looking for versatile portfolios. Their presence in both adult and pediatric niches implies opportunities for differentiated product placements and OR/ICU cross‑sell.
- Cardinal Health — Recent strategic moves have materially changed Cardinal’s role: the announced US commercial discontinuation of select chest drainage lines (effective late 2025) followed by a Class II device recall in early 2026 have created near‑term distribution and inventory dislocations. For competitors and customers, this is both a supply risk and an addressable opportunity. Tactical recommendations include contingency sourcing, short‑cycle contracting, and targeted promotional programs to capture reallocated volume.
- Teleflex, Cook Medical, Vygon, Utah Medical — These companies compete on product range and catheter design. Their strengths are in direct clinician relationships and procedural familiarity; they are natural partners for incremental product upgrades and procedure‑specific solutions.
- Medtronic, Medela, ATMOS, Centese — These firms are at the forefront of digital thoracic drainage. Medela’s Thopaz+ and ATMOS C 051 exemplify the trend toward objective air‑leak monitoring and enhanced patient mobility. Centese’s Thoraguard brings automation (clog clearance and quantitative drainage measurement) into the clinical conversation. For strategy teams, digital capability and data services are now differentiating features that justify premium pricing and new procurement categories.
- Regional and emerging manufacturers (Redax, Sinapi Biomedical, Sterimed, Angiplast) — These players provide localized manufacturing, cost‑competitive products, and increasing technical sophistication. They are critical partners for volume deployments in price‑sensitive markets or for OEM/contract manufacturing strategies.
Recent industry developments that affect 2026 planning
- Regulatory event: Cardinal Health’s device recall (Class II) announced in early 2026 creates short‑term clinical and procurement disruption. Hospitals and group purchasing organizations should reassess inventory and vendor continuity plans immediately.
- Commercial exit: Cardinal’s prior announcement to discontinue certain chest drainage units in the US (effective November 2025) has already shifted the competitive landscape; expect competitors to accelerate field campaigns for dislocated accounts.
- Technology and regulatory clearance: New entrants and adjacent‑tech firms (e.g., FluidAI Medical’s 510(k) clearance in 2025) are expanding monitoring capabilities around surgical drainage, signaling an influx of software‑enabled adjuncts and new data monetization vectors.
- Clinical engagement and visibility: Regional innovators such as Sinapi Biomedical actively participating in cardiothoracic forums show the importance of trade show presence and surgeon engagement in adoption pathways.
Regulatory and reimbursement dynamics executives must internalize
Thoracic drainage devices in the U.S. are predominantly regulated as Class II devices via the FDA 510(k) pathway. Digital and electrically powered drainage systems must also meet consensus standards for electrical safety and performance, extending product development and validation timelines. On the reimbursement side, thoracic procedures involving chest tube insertion are coded under established CPT listings (e.g., CPT 32551) and linked to APCs and MS‑DRG payments that consider case severity and CC/MCC status — a nuance that materially affects hospital economic modeling for product adoption.
Strategic playbook for 2026 (practical actions)
- Prioritize digital drainage investments where clinical evidence can be generated within 12–18 months: pilot programs that produce LOS and readmission data accelerate contracting wins.
- Execute immediate supply continuity plans: identify alternative suppliers, build buffer inventories for high‑volume accounts, and negotiate flexible restocking terms to mitigate recall/discontinuation risk.
- Reassess pricing and contracting frameworks: structure value‑based agreements that link device fees to measurable outcomes (e.g., days to chest tube removal, LOS reduction).
- Pursue tuck‑in M&A or distribution agreements to capture reallocated volumes in markets affected by recent commercial exits; focus on companies with digital capability or unique catheter technologies.
- Invest in regulatory engineering for digital systems early: compliance with electrical and interoperability standards should be designed into hardware and software roadmaps to avoid late‑stage rework.
- Localize manufacturing and service models for price‑sensitive geographies via licensing or contract manufacturing partnerships to improve margin resilience and procurement flexibility.
What’s in the PW Consulting report (practical deliverables)
The full report blends market intelligence with executable toolkits tailored for deal teams, commercial leaders, and R&D heads. Highlights include:
- Market sizing and scenario forecasts (2020–2032) with upside/downside scenarios and sensitivity analyses for procedure volumes, pricing, and adoption curves.
- Competitive landscaping: detailed profiles, product maps, and go‑to‑market playbooks for the leading incumbents and emerging challengers.
- Regulatory and reimbursement playbooks: step‑by‑step guidance on 510(k) strategy, electrical safety requirements, and hospital coding/revenue impact modeling.
- Commercial tools: sample tender language, value‑story slides for hospital committees, and contracting templates tied to outcomes metrics.
- Innovation scouting and M&A pipeline: prioritized targets and integration risk checklists, plus a 90‑day capture plan for displaced volumes after vendor exits.
- Operational risk matrix and supplier continuity model that quantify exposure from recalls, single‑source components, and regional manufacturing constraints.
Conclusion — how to use this insight in 2026
For C‑suite executives, the strategic question for 2026 is not whether the thoracic drainage market will grow — it will — but how to position the organization to capture premium growth driven by digital adoption, clinical outcomes, and supply resilience. The market’s mid‑single‑digit CAGR and the expected uplift to well over USD 1.4 billion through 2032 create opportunities for companies that combine product innovation with pragmatic commercialization and regulatory execution.
PW Consulting’s full report contains the underlying segment models, scenario spreadsheets, and competitive scorecards necessary to convert these insights into boardroom decisions. To access the complete dataset, segmentation tables, and step‑by‑step playbooks that support M&A, product investment, and market entry strategies, please consult the full report on the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Complicated UTI Treatment Market Poised to Expand at a 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Complicated Urinary Tract Infections (cUTI) Treatment Market — A Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Complicated Urinary Tract Infections Treatment Market is calibrated to the needs of senior executives, corporate strategists, portfolio managers, and policy-makers preparing for the decisive planning cycle of 2026. The report converts a complex and rapidly evolving therapeutic space into pragmatic, decision-ready intelligence — showing where value will be created, who will capture it, and which operational choices will most materially affect outcomes over the 2026–2032 forecast window.
Worldwide Complicated Urinary Tract Infections Treatment Market
Why this report matters for 2026 strategy
-
Clear macro trajectory: The cUTI treatment market demonstrates steady expansion, underpinned by both demand-side clinical pressures and supply-side innovation. Our analysis uses a 2025 base year and models the market forward to 2032, incorporating historical trends (2020–2025) and scenario-adjusted assumptions for the 2026–2032 forecast period, projecting a compound annual growth rate of roughly 6.5% through 2032.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Investment timing: The timing of late-stage clinical readouts, regulatory decisions, and patent cliffs in the 2026–2028 window will reshape competitive dynamics. Our report highlights the inflection points that should guide R&D budgets, licensing decisions, and M&A prioritization for the 2026 planning round.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Actionable implications: Rather than offer only descriptive market sizing, the study emphasizes operational playbooks — from supply-chain mitigation to formulary positioning — so that leadership teams can translate market signals into executable plans in 2026.
Market trajectory in context
Between 2023 and 2025 the market expanded materially from the low- to mid-thousand-million dollar range and continues on a steady upward path into the forecast period. Our base-year 2025 calibration anchors a forward projection that reaches northward over the next seven years, driven by a mix of novel antibacterial approvals, expanded indication use, and persistent clinical need for effective empiric and directed therapies in complex inpatient and complicated outpatient settings. The modeled 6.5% CAGR for 2026–2032 embodies both conservative uptake assumptions for newer agents and upside from improved stewardship and reimbursement alignment.
What’s included — practical, executable sections
-
Market sizing & forecast: A transparent, reproducible financial model with topline projections, sensitivity tables, and scenario variants calibrated to different adoption curves and pricing trajectories.
-
Clinical and pipeline review: Deep, agent-level dossiers covering approved products, late-stage candidates, mechanism-of-action overlays, and probability-adjusted launch timelines.
-
Regulatory & reimbursement intelligence: Country- and region-specific regulatory milestones, QIDP impacts, exclusivity windows, and payer positioning analysis that directly inform launch sequencing and pricing strategies.
-
Competitive benchmarking: A strategic matrix mapping capability, commercial reach, clinical differentiation, and vulnerability to generic threats for key players.
-
Supply-chain risk assessment: Identification of critical API dependencies, shortage scenarios, and recommended mitigation constructs — from dual-sourcing to long-term supplier contracts.
-
Go-to-market playbooks: Tactical roadmaps for hospital formulary access, outpatient stewardship engagement, and digital/remote distribution models, including online pharmacy dynamics.
-
M&A and partnership targets: A prioritized list of tuck-in candidates, licensing archetypes, and collaboration structures optimized for mid-sized and large pharma buyers.
Competitive landscape — who matters and why
The cUTI market is contested across several fronts: novel chemical entities and combinations addressing resistant Gram-negative pathogens; extended-spectrum beta-lactamase and carbapenemase-active agents; and oral agents that enable early transition of care. Key industry participants covered in our report include long-standing large-cap antimicrobial franchises and agile specialty biotechs that have advanced novel pathways to market. The strategic roles of those players are summarized below (profiles and deeper competitive analysis are included in the full report).
-
Merck & Co., Inc. — leverages a marketed cephalosporin-beta-lactamase inhibitor combination with established hospital positioning and formulary presence. Its commercial footprint and clinical evidence base make it a baseline comparator for new entrants.
-
GlaxoSmithKline plc — markets a cephalosporin/β-lactamase inhibitor that has received regulatory approvals in major jurisdictions for limited-option patients; regulatory precedent in Europe strengthens its specialty hospital access.
-
Pfizer Inc. — maintains broad distribution and lifecycle strategies around approved ceftazidime-avibactam therapy, with a strong hospital sales force and existing payer relationships that support utilization in complicated cases.
-
Allergan (AbbVie Inc.) — while better known in other therapeutic areas, it participates in the cUTI arena via agents that have both labeled and off-label hospital use; portfolio integration and hospital access are its strategic levers.
-
Basilea Pharmaceutica Ltd. — a smaller innovator with complementary assets and partnership models focused on resistant infections; its positioning demonstrates how mid-sized players can influence niche resistant strains through targeted collaborations.
-
Spero Therapeutics, Inc. — represents a textbook late-stage disruptor: an oral carbapenem prodrug with QIDP signaling and positive Phase 3 topline results that could materially alter outpatient and early-discharge pathways if approved and commercialized efficiently.
-
VenatoRx (formerly Entasis) — the recent approvals for agents active against Acinetobacter highlight the market’s shift toward addressing highly resistant hospital pathogens and the commercial opportunities tied to acute-care stewardship and infection control budgets.
Recent regulatory and market events that shape 2026 choices
-
Regulatory incentives and exclusivity matter. QIDP designations and associated review accelerations materially shorten time-to-revenue for qualifying molecules and create five-year exclusivity windows in the U.S.; these factors should be central to portfolio cadence planning.
-
Approvals and paradigm shifts. Recent FDA approvals for agents targeting resistant Gram-negative pathogens have created both clinical precedent and commercial pathways for similarly positioned launches — but each approval also raises the bar for comparative-effectiveness evidence demanded by hospitals and payers.
-
Patent timelines. Approaching patent expirations on core agents (notably mid-decade cliffs for certain beta-lactam/beta-lactamase inhibitor combinations) will reshape pricing dynamics and generic entry strategies; companies need to model erosion curves and bundling strategies for 2026 budgeting.
-
Supply-side fragility. Documented API shortages for legacy penicillin-derived combinations have already disrupted hospital ordering patterns; as utilization rebounds post-pandemic, resilience investments (dual sourcing, strategic inventories) will command board-level attention.
-
Reimbursement nuances. Inclusion on public formularies and tiering decisions materially influence hospital and outpatient uptake. The interplay of copay tiers, hospital DRG incentives, and stewardship policies creates both obstacles and leverage points for commercialization.
Strategic recommendations for 2026 planning
-
Prioritize launch sequencing based on regulatory runway and formulary friction. For companies with late-stage assets, allocate concentrated commercial resources to territories where regulatory precedence and reimbursement mechanics reduce time-to-adoption.
-
Embed supply-chain resiliency into go-to-market budgets. Allocate capital for redundant API sourcing and contingency inventories, and negotiate contractual protections (price collars, force majeure clauses) to hedge against recurrence of shortages.
-
Differentiate through stewardship-aligned evidence. New agents should be launched with protocols and real-world evidence programs that demonstrate reductions in length of stay, need for escalation to intensive care, or readmission rates — financial endpoints that payers and hospital CFOs value most.
-
Use selective partnerships to de-risk commercialization. For mid-sized innovators, co-promotion agreements or regional licensing can unlock commercialization scale while preserving upside; for big pharma, targeted bolt-on acquisitions can rapidly fill pipeline gaps where internal programs are late or uncertain.
-
Prepare for generic/differentiated competition. Model the financial impact of patent expirations and construct tiered defense plans — lifecycle management, clinical differentiation, and indication expansion — to preserve value into the late-2020s.
-
Reassess distribution strategy in light of digitization. Online pharmacy channels and outpatient infusion/transition-of-care models are rising; companies should pilot hybrid distribution and remote-support models to maximize patient access while maintaining stewardship oversight.
How PW Consulting’s report supports boardroom decisions in 2026
Our study is intentionally engineered as a “strategy-to-execution” toolkit. Beyond headline market trajectories, it delivers executable inputs for 2026 budgeting and scenario planning: probability-weighted revenue paths for candidate launches, prioritized lists of M&A targets and partnership archetypes, a negotiable playbook for hospital access negotiations, and a suite of metrics to track early-launch health. The result is a single reference that reduces strategic uncertainty and expedites decision cycles.
Next steps — a discreet preview offer
This executive brief demonstrates the analytical scaffolding and strategic outcomes you can expect from the full PW Consulting report. To access the complete dataset, agent-level dossiers, and the reproducible financial model (including all sensitivity analyses and scenario outputs), please visit our report landing page. The full report contains the precise segmentation tables, region- and channel-level forecasts, and the granular competitive benchmarks omitted here as part of our “trailer” approach to preserve the actionable premium contained in the complete deliverable.
For a tailored briefing or to commission a bespoke extension (e.g., country-level forecasts, payer-value dossiers, or bespoke M&A target screens tied to your portfolio), PW Consulting’s life sciences practice is available for immediate engagement as firms finalize 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Piriformis Syndrome Market Poised to Top USD 320.96 Million by 2032 with 5.51% CAGR
By pmarketresearch, 2026-07-15
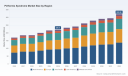
Worldwide Piriformis Syndrome Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting’s latest market intelligence brief on the Worldwide Piriformis Syndrome market delivers a concise, decision-grade view tailored for executive teams planning moves in 2026. Built on a calibrated historical series (2020–2025, base year 2025) and a seven‑year forecast window (2026–2032), the research frames evolution in treatment modalities, reimbursement posture, competitive positioning and technology convergence. At a macro level, the market expanded from roughly USD 170 million in 2020 to USD 220.5 million in 2025 and is projected to continue growing through the forecast, reaching about USD 321.0 million by 2032 — a compound annual growth rate (CAGR) of 5.51% for 2026–2032. These headline metrics are the foundation for scenario planning, deal assessment and product positioning in the year ahead.
Worldwide Piriformis Syndrome Market
Why this matters for 2026 corporate strategy
-
Predictable, mid-single-digit growth creates a low‑volatility environment that is attractive for targeted R&D investments and roll‑out pilots. The consistent growth trajectory gives market entrants and incumbents room to test differentiated therapies without requiring a rapid scale gamble.
Worldwide Piriformis Syndrome Market -
Market concentration is moderate. The top three players account for roughly one‑third of market value while the top five approach half the market, indicating clear leadership but ample space for niche innovation and localized competitors to capture share.
Worldwide Piriformis Syndrome Market -
Payer and coding clarity — especially recent guidance around injection billing and Medicare LCDs addressing botulinum toxin use — reduces uncertainty for commercialization plans that rely on interventional treatments or developer reimbursement strategies.
-
The evidence base is strengthening. Randomized trials and ongoing clinical studies are refining the comparative effectiveness picture across corticosteroid injections, shockwave therapy, manual techniques and minimally invasive procedures. This creates opportunities for evidence‑led market access plays.
-
Convergence across device, pharmaceutical and digital therapy vendors is accelerating. Wearable TENS, injectable biologics/toxins and minimally invasive surgical options are competing on the same value dimension — durable pain relief with low throughput cost and outpatient delivery.
What the PW Consulting report delivers (practical contents)
-
Executive summary with scenario maps keyed to regulatory and payer trajectories for 2026–2032.
-
Full historical market model (2020–2025) and forward projections by treatment pathway and channel, presented with sensitivity runs and high/medium/low adoption cases.
-
Actionable go‑to‑market playbooks for pharmaceutical firms, device manufacturers, specialty clinics and health systems (including recommended pilot geographies and KPI templates).
-
Regulatory & reimbursement navigator covering coding, Medicare LCDs and payer decision triggers that materially affect access and pricing.
-
Competitive landscape deep dives: strategy, pipeline and capability appraisal for established and emerging players — with acquisition and partnership targets prioritized by strategic fit.
-
Investor brief with valuation scenarios and M&A heat‑map informed by concentration metrics and growth drivers.
-
Data annex featuring the complete time‑series market model, assumptions workbook and a reproducible methodology for clients to run bespoke sensitivity analyses.
Competitive landscape — who matters and why
-
Deuk Spine Institute (United States) — A case study in procedural innovation. The institute’s promoted minimally invasive piriformis release procedure highlights how a proprietary, outpatient surgical intervention with a strong safety narrative can shift care pathways. For strategic buyers and partners, the key questions are scaleability, reproducibility outside the origin center and the potential to license the technique or instruments to specialty networks.
-
Allergan (AbbVie) — A mainstream pharmaceutical competitor with established onabotulinumtoxinA assets. The product’s off‑label and adjunctive use for targeted muscle injections positions a large pharma incumbent to influence adoption through clinical sponsorship, payer engagement and integrated care bundles.
-
King Brand Healthcare Products — An example of targeted physical‑modal therapy products (cold/heat wraps) that capitalize on non‑pharmacologic demand. These simple, consumable items underscore revenue diversification opportunities for clinics and retail channels.
-
Bayer, Novartis, Sanofi, Teva, Endo — Large pharma and generic houses maintain market relevance by supplying analgesics, NSAIDs and muscle relaxants. Their strategic choices are typically around labeling, guideline engagement and distribution leverage rather than high‑risk clinical innovation.
-
Omron Healthcare and digital/wearable vendors — Represent the non‑invasive device cohort. Promotion of wearable TENS devices by digital health players demonstrates a route to recurring revenue and direct‑to‑consumer adoption that bypasses some traditional provider bottlenecks.
-
Market implications — The mix of specialty innovators (procedural developers), large pharma and device/digital entrants suggests a multi‑modal competitive set. Partnerships (e.g., pharma + device + clinic networks) are likely to be the most effective route to scale given payer preferences for demonstrable outcomes and cost offsets.
Regulatory, reimbursement and clinical signals shaping 2026
-
Coding and billing guidance from major payers is converging on clearer rules for injections and interventional coding — reducing friction for outpatient procedures where needle guidance imaging has unclear marginal benefit.
-
Medicare local coverage determinations recognize the reasonable necessity of botulinum toxins for certain refractory indications when criteria are met — a favorable precedent for payer coverage pathways that companies can leverage.
-
FDA approvals for several botulinum toxin products create a predictable regulatory backdrop for toxin‑based interventions, although off‑label use and evidence generation remain important for piriformis‑specific claims.
-
Clinical practice conservatism: surgery is still predominantly reserved for refractory cases after conservative and interventional therapies fail. This slows rapid uptake of invasive options but rewards minimally invasive outpatient approaches that demonstrate durable outcomes.
Recent developments that matter for near‑term strategy
-
April 2026 — Promotion of a patented minimally invasive piriformis release procedure (as an outpatient technique) underlines how procedural IP can be commercialized via center‑of‑excellence models before broader rollout.
-
April 2026 — Publication of a randomized controlled trial comparing corticosteroid injection vs extracorporeal shockwave therapy adds comparative evidence that payers and guideline committees will scrutinize when defining coverage criteria.
-
March 2026 — Active promotion of wearable TENS devices highlights a parallel adoption pathway that could erode some demand for clinic‑delivered interventions if robust real‑world effectiveness is demonstrated.
-
Ongoing — Multiple clinical trials listed on clinical registries continue to explore manual techniques, shockwave therapy and procedural options; readouts over the next 12–24 months will be pivotal to market share assumptions.
Strategic playbook for 2026 — six executable moves
-
Prioritize evidence generation: sponsor pragmatic trials that demonstrate real‑world comparative effectiveness and health economic benefits (QALYs, reduction in downstream opioid use, decreased throughput costs).
-
Secure coding & reimbursement readiness: prepare LCD dossiers and engage early with payer medical directors to expedite favorable coverage determinations for new procedures or device‑drug bundles.
-
Pursue asymmetric partnerships: device makers should seek pharma collaborations to combine procedural and pharmacologic approaches into bundled offerings; specialty clinics can partner on commercial pilots to validate outpatient pathways.
-
Test direct channels for low‑touch solutions: scale wearable and OTC pain relief offerings via digital marketing pilots to ascertain incremental market capture without heavy provider dependence.
-
Adopt a staged geographic expansion: use outcome data from centers of excellence to support payer negotiations in successive jurisdictions rather than broad simultaneous launches.
-
Model M&A with concentration context: given the market’s moderate concentration, small‑to‑mid size strategic acquisitions (clinical networks, specialized device firms, or proprietary procedural platforms) are likely to be accretive without triggering large antitrust hurdles.
Signals to monitor closely through 2026
-
Key trial readouts and meta‑analyses that shift comparative effectiveness rankings.
-
Payer LCD updates or national coverage decisions affecting interventional and toxin‑based therapies.
-
Scaling metrics from early procedural adopters (complication rates, time‑to‑discharge, repeat intervention rates).
-
Device adoption curves for wearables and clinic‑based TENS units, and their demonstrated impact on clinic visit volumes.
-
Regulatory moves or guideline endorsements that alter the point at which surgery is recommended.
PW Consulting’s Worldwide Piriformis Syndrome market brief is designed to be immediately operational for leadership teams grooming product roadmaps, payer strategies, and M&A pipelines in 2026. This preview outlines the strategic signals we believe will shape the year ahead — but the full report contains the granular segmentation tables, regional and channel split models, company market shares and the scenario workbooks you will need to build executable plans.
To access the complete dataset, detailed company profiles, and our tailored recommendations for your organization, please download the full report or contact PW Consulting for a customized briefing and model walk‑through.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Food Encapsulating Technology Market to Reach USD 19.93 Billion by 2032, Growing at an 8.12% CAGR
By pmarketresearch, 2026-07-15
Worldwide Food Encapsulating Technology Market — Strategic Outlook for 2026 Decision-Makers
As food manufacturers, ingredient suppliers, and strategic investors prepare plans for 2026, the global market for food encapsulating technologies has reached an inflection point. Our newest market study from PW Consulting establishes a clear macro trajectory: the market expanded markedly through the early 2020s and, with robust fundamentals, is projected to continue growing into the early 2030s at a compound annual growth rate of 8.12%. With a 2025 base-year close to USD 11.6 billion and an anticipated rise toward the high‑single‑digit‑billion range by 2032, the sector offers both scale opportunities for incumbents and fertile ground for differentiated entrants.
Worldwide Food Encapsulating Technology Market
Why this market matters for 2026 decision cycles
-
From ingredient stability to label claims, encapsulation is now an enabling technology that translates scientific advantage into commercial differentiation across an expanding set of food and beverage categories.
Worldwide Food Encapsulating Technology Market -
Macro drivers — demographic demand for fortified and convenient nutrition, sustainability pressures on formulation and packaging, and regulatory attention to fortification and food safety — align to make encapsulation a strategic lever rather than a niche R&D line item.
Worldwide Food Encapsulating Technology Market -
Capital allocation decisions made in 2026 (R&D budgets, pilot lines, M&A/partnerships, and manufacturing expansions) will determine market positioning for the remainder of the decade. Timing matters: capacity and validated IP invested now will compound value as adoption accelerates.
What PW Consulting’s report delivers — practical, actionable intelligence
Beyond headline numbers, the report is structured to turn market insight into executable choices for 2026 planning. Key deliverables include:
-
Macro forecast and scenario analysis with upside/downside paths tied to ingredient‑level adoption rates and regulatory shifts.
-
Technology performance matrix comparing spray drying, spray chilling, fluid‑bed coating, extrusion and emergent plant‑protein microcapsules across stability, sensory impact, release profile, and scale economics.
-
Commercialization playbooks — from pilot to full production — with CAPEX benchmarking, typical scale‑up failure modes, and go/no‑go criteria for plant investment.
-
Supplier and partner maps that pair formulation needs (e.g., fat‑soluble vitamins, probiotics, flavors) with wall‑material expertise and toll‑manufacturing capacity.
-
Regulatory and compliance checklist tailored to fortified foods, probiotic claims, and novel ingredient delivery systems, including food safety measures for bacteriocin/antimicrobial encapsulation.
-
Commercial insights: pricing dynamics, tender and volume pricing playbooks, and recommendations for structuring long‑term offtake and raw‑material hedging contracts.
To preserve commercial intent and to respect client confidentiality in this pre-release narrative, granular regional and application breakdowns—our most sensitive segmentation tables—are intentionally omitted here. The full report provides those tables and interactive models for subscribers and corporate clients.
Strategic imperatives for 2026
-
Prioritize capability, not just capacity. Investments should pair production scale with targeted formulation expertise (e.g., enteric release for probiotics, stability for fat‑soluble vitamins). A new high‑capacity facility creates value only if paired with validated process‑ingredient know‑how.
-
Portfolio segmentation by value‑capture, not only by application. Differentiate product lines by customer willingness‑to‑pay: premium functional ingredients with controlled release versus low‑margin commodity flavor encapsulates.
-
Lock in wall‑material supply chains. Polysaccharides (starches, maltodextrins, gum arabic) and proteins (whey, soy, pea) remain core inputs; securing feedstocks and contingency suppliers is a near‑term priority.
-
Design for regulatory alignment and label‑friendly claims. Encapsulation can enable compliance with tightening fortification and labeling requirements while supporting clean‑label narratives; incorporate regulatory teams early in product development.
-
Use partnership and licensing to accelerate capability buildout. The market concentration profile shows leading players hold meaningful share but not complete dominance, creating openings for co‑development, licensing, and framed acquisitions.
Competitive landscape: who to watch and how they shape strategy
The competitive field combines global ingredient majors, flavor houses, and specialist encapsulation firms. Understanding each archetype helps firms pick the right competitive or partnership posture:
-
Large ingredient integrators (examples: global agribusiness and starch specialists) bring scale manufacturing, carbohydrate science, and route‑to‑market strength. Their advantage is rapid scale and wide distribution networks — an essential partner for commoditized encapsulates and beverage systems.
-
Flavor and premix multinationals offer integrated taste and delivery systems. Their R&D footprints and application labs let them bundle sensory optimization with delivery performance — a compelling proposition for finished‑goods customers seeking simplified supplier relationships.
-
Specialist microencapsulation firms focus on technical performance and niche release profiles. They are sources of disruptive IP and frequently become targets for licensing or acquisition by larger players aiming to fill capability gaps.
-
New‑wave entrants and bio‑based innovators are introducing sustainable wall materials and plant‑protein based capsules, targeting clean‑label and environmental narratives crucial to many consumer categories.
Two recent industry developments illustrate distinct strategic playbooks. First, a major microencapsulation supplier announced a capacity expansion, signaling confidence in long‑term demand and a move to secure industrial‑scale supply for bakery, confectionery, and meat applications. Second, a plant‑protein microcapsule developer published peer‑reviewed validation showing protection of fat‑soluble nutrients through processing and enteric release, underscoring both the technical maturity of alternative wall materials and the commercial appeal of sustainability‑based differentiation.
These moves show parallel trends: incumbent consolidation around scale and emergent technology validation that lowers entry barriers for sustainable alternatives. Both trends demand active response from market participants.
Operational playbook for near‑term execution
-
R&D: Run 6–12 month de‑risking sprints focused on the top three delivery challenges: oxidative protection, taste masking, and targeted release. Use accelerated shelf‑life protocols and simulated digestion studies to validate claims.
-
Piloting: Establish modular pilot lines capable of spray drying and fluid‑bed coatings. Prioritize flexible lines that can run multiple wall materials to respond quickly to customer demand.
-
Supplier strategy: Qualify at least two suppliers for each critical wall material and negotiate supply‑chain resilience clauses. Consider toll‑manufacturing partnerships to meet near‑term demand spikes while longer‑term CAPEX is evaluated.
-
Commercial: Reframe sales teams to sell benefits (stability, label claims, sensory) rather than unit costs. Build case studies showing reduced restitution, extended shelf life, and consistent dosing as the basis for premium pricing.
Risk map and mitigation
-
Raw material volatility: Lock in indexed contracts and create reformulation contingencies for key polysaccharides and proteins.
-
Regulatory uncertainty: Invest in regulatory foresight and scenario planning for regional labeling changes and novel‑ingredient pathways.
-
Scale failure: De‑risk scale up with staged investments—pilot → semi‑works → full plant—and use contract manufacturing to bridge capacity gaps.
-
Competition and margin compression: Use IP, co‑development agreements, and branded ingredient programs to protect margins.
How PW Consulting’s data supports 2026 capital and commercial choices
The report’s integrated forecast and scenario modules translate the macro CAGR and market size trajectory into discrete capacity and revenue build models for the next six years. It couples these projections with vendor benchmarking, process KPIs, and a regulatory compliance roadmap — the inputs that CFOs and strategic planners need to build defensible five‑year CAPEX proposals and commercial rollout plans.
Importantly, we have intentionally withheld the full granular regional and application‑level tables in this summary to preserve the strategic value of the complete dataset. Those detailed breakdowns—critical for deciding where to invest production capacity, which applications to prioritize, and which customers to target—are available in the full report and our interactive subscription portal.
Final recommendation
For leaders setting 2026 priorities: treat food encapsulation as a strategic capability that combines material science, process engineering, and regulatory navigation. If you are a manufacturer, accelerate pilots and secure partnerships to ensure you can translate ingredient innovation into marketable, label‑compliant products. If you are an investor or acquirer, focus on validated IP, proven scale‑up pathways, and firms that bridge sustainability claims with demonstrable performance.
PW Consulting’s Worldwide Food Encapsulating Technology Market report provides the detailed forecasting, vendor intelligence, and operational playbooks needed to act with confidence in 2026. Access the full dossier for the complete segment and regional tables, vendor scorecards, and interactive scenario tools that we use with our corporate clients to convert market insight into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Food Encapsulating Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wearable Injectors Market Poised to Grow at 13.5% CAGR Over 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Wearable Injectors Market — Strategic Outlook for 2026: Key Imperatives from PW Consulting
PW Consulting’s new market study, Worldwide Wearable Injectors Market (base year 2025, forecast 2026–2032), translates the rapid commercial maturation of wearable drug delivery into an actionable corporate playbook for 2026 decision‑makers. The market has moved from an early-adopter phase into sustained commercial scale: global revenue expanded from the mid‑single billions in 2020 to approximately USD 9.2 billion in 2025, and our base forecast—anchored to observed commercialization, regulatory milestones and technology adoption curves—projects a compound annual growth rate (CAGR) of 13.5% across 2026–2032, driving the market into the low‑double‑decade billions by the end of the forecast horizon. This study is designed to be the operational blueprint for executives needing to convert strategic intent into executable programs in 2026.
Worldwide Wearable Injectors Market
Why 2026 is the pivotal year
-
Commercial inflection. Several platform vendors converted development pipelines into commercial agreements and regulatory clearances in 2024–2025, creating tangible go‑to‑market paths for pharma partners and payers. These moves accelerate adoption timelines for large‑volume subcutaneous biologics and broaden therapy areas beyond diabetes into oncology, immunology and chronic disease management.
Worldwide Wearable Injectors Market -
Regulatory and reimbursement clarity. Evolving device standards and clearer reimbursement codes are shortening commercialization risk cycles. Compliance requirements such as ISO 11608‑01:2012 for needle‑based systems and IEC 60601‑1 for electrical safety are now front‑and‑center in product development roadmaps, and the availability of HCPCS codes for wearable injector supplies has materially improved Medicare coverage predictability in the U.S.
Worldwide Wearable Injectors Market -
Platform consolidation and partnership momentum. Strategic alliances and supply agreements announced in 2024–2025 indicate a market shifting from point solutions to integrated platform/pharma models. The pattern we observe will determine licensing, revenue share and service‑bundle strategies that corporate leaders must decide in 2026.
What the report delivers — practical, transaction‑ready content
-
Comprehensive market sizing and methodology. A reproducible top‑down and bottom‑up approach covering historical (2020–2025) and scenario‑based forecasts (2026–2032), with sensitivity runs that map revenue outcomes to key adoption variables.
-
Go‑to‑market playbooks. Market entry templates by therapy cluster, payer engagement roadmaps, and commercial contracting examples designed for pharma/device co‑development and commercialization.
-
Regulatory pathway maps and checklists. Stepwise requirements for device classification, safety testing, clinical comparators and post‑market surveillance aligned to major jurisdictions.
-
Manufacturing, sourcing and cost levers. Bill‑of‑materials benchmarking, low‑cost material strategies, and supplier selection filters—grounded in current inputs such as medical‑grade polymer pricing and production scale curves.
-
Competitive and partnership landscape. Operator profiles, strategic positioning matrices, technology readiness assessments and partnership diligence templates for licensing, supply and commercialization agreements.
-
Investment, M&A and valuation guidance. Playbook for buy, build or partner choices, with deal comparators and integration risk checklists tailored to wearable injectors.
-
Risk matrices and mitigation plans. Practical contingencies for regulatory delays, component shortages, and reimbursement revisions—each paired with execution checklists.
Competitive landscape — what leading vendors signal to the market
The sector is characterized by a mix of specialised device firms, incumbent pharmaceutical partners, and regional low‑cost entrants. Rather than enumerate sensitive segment shares here, PW Consulting’s report provides detailed benchmarking; below we summarize strategic positioning and implications for 2026 strategy:
-
Ypsomed (Switzerland — https://www.ypsomed.com): A mature on‑body platform vendor with strong product heritage and recent investments in connectivity. Its next‑generation platform emphasizes real‑time dose monitoring and integration with digital therapeutics — a clear signal that clinical and adherence data will increasingly be negotiated as part of commercial contracts.
-
West Pharmaceutical Services (USA — https://www.westpharma.com): A device incumbent translating component supply strength into system‑level offerings. Recent commercial supply agreements highlight a route to co‑development that leverages legacy pharma relationships; companies considering scale should evaluate supply security and partner IP control when negotiating licensing terms.
-
Enable Injections (USA — https://enableinjections.com): A regulatorily validated entrant with 510(k) clearances that shortens the time to market for partners. The availability of FDA‑cleared variants reduces clinical and regulatory execution risk for therapeutics seeking subcutaneous large‑volume delivery.
-
Stevanda (India — https://www.stevanda.com): Focused on cost‑competitive platforms for emerging markets. Their presence underscores geographic segmentation strategies: low‑cost offerings can expand addressable markets if paired with appropriate regulatory and distribution models.
-
Medipim (Belgium — https://www.medipim.com) and Nexus Pharmaceuticals (USA — https://www.nexuspharma.com): Both illustrate differentiated approaches — multi‑day delivery and partnership distribution models respectively — that expand use‑cases beyond single‑dose self‑administration.
Regulatory and reimbursement dynamics — actionable implications
-
Standards compliance is non‑negotiable. Device programs must demonstrate adherence to ISO 11608‑01:2012 and relevant electrical safety standards like IEC 60601‑1 early in development. Incorporate standardized test plans into vendor RFQs to avoid late‑stage redesigns.
-
Reimbursement tractability accelerates commercial uptake. The presence of specific HCPCS identifiers for wearable injector supplies has created a pragmatic pathway for Medicare coverage in the U.S.; payer dossiers should anticipate and document real‑world adherence and cost‑offset evidence to secure favorable reimbursement.
Operational levers — cost, sourcing and supply‑chain resilience
Device economics are sensitive to materials and assembly costs, with medical‑grade polymers forming a significant portion of the bill of materials. Current sector benchmarks for common housing resins point to bulk pricing in the low‑double digits per kilogram; design decisions that reduce polymer mass, enable modular assembly, or substitute higher‑cost components with qualified alternatives can yield meaningful margin upside at scale.
Actionable steps for 2026:
-
Lock strategic supply agreements for critical polymers and electronics subassemblies with indexation clauses to manage volatility.
-
Qualify multiple injection‑moulding partners across geographies to reduce single‑site risk.
-
Implement design‑for‑assembly and design‑for‑recycling principles early to lower unit costs and support ESG commitments.
M&A, partnerships and the build vs. buy decision
2024–2025 deal activity shows three pragmatic motifs: (1) pharma looking to de‑risk launch timelines by partnering with device specialists, (2) device vendors securing commercial supply contracts to guarantee scale economics, and (3) regional entrants addressing affordability in emerging markets. For 2026 strategy, PW Consulting recommends a decision framework built on three criteria: time‑to‑market tolerance, control over IP/data, and total economic return. For therapies where adherence data is a core value driver, acquisition or exclusive licensing of platform technology may be justified. For therapies requiring rapid launch with constrained internal device capability, non‑exclusive supply and co‑commercial partnerships will often be superior.
Signals from recent market moves
-
New product launches with enhanced connectivity (e.g., platforms enabling real‑time dose monitoring) indicate that clinical evidence packages will increasingly include digital adherence and PK/PD correlation data.
-
Regulatory clearances of variant device forms reduce clinical risk and shorten commercialization lead times for partnering therapeutics.
-
Commercial supply agreements between device vendors and major pharma demonstrate that contract terms around data ownership, service levels and revenue sharing are now central negotiation points.
How to use the full PW Consulting report
This press note highlights the strategic takeaways you need to act in 2026; the full PW Consulting study contains the granular tools that will convert these insights into executable plans. Subscribers gain access to:
-
Interactive financial models with scenario toggles for adoption speed, pricing, and reimbursement outcomes.
-
Negotiation playbooks and sample contract clauses for platform licensing and supply agreements.
-
Detailed segment breakdowns, region and therapy‑specific adoption curves and channel models — intentionally withheld here to maintain this preview’s trailer role and to drive acquisition of the full dataset.
Conclusion — the strategic mandate for 2026
Wearable injectors are no longer a speculative adjunct to biologic delivery; they are a strategic lever for therapeutic differentiation, patient adherence, and new reimbursement value pools. The market’s strong growth trajectory and recent vendor and regulatory activity create both opportunity and execution risk. PW Consulting’s Worldwide Wearable Injectors Market report supplies the quantitative foundation, operational checklists and contract‑level playbooks necessary to convert 2026 strategic decisions into sustainable commercial outcomes. For executives planning portfolio prioritization, partnership negotiations or M&A targeting, this study is intended to be the reference document for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global High-Concentration Glufosinate Ammonium Market Set to Surge at a 14.02% CAGR
By pmarketresearch, 2026-07-15
Worldwide High‑Concentration Glufosinate Ammonium Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market intelligence brief, Worldwide High Concentration Glufosinate Ammonium Market (Base Year 2025; Forecast 2026–2032), translates a complex, fast‑moving landscape into prioritized actions for commercial, procurement and corporate strategy teams preparing plans in 2026. Our analysis finds the global market reached approximately USD 621.9 million in 2025 and, under our base forecast, is set to grow at a compound annual growth rate of 14.02% through 2032 — crossing the USD 1.55 billion mark by the end of the projection horizon. This release summarizes the strategic implications embedded in the full report and explains why accessing the complete dataset and scenario models is essential for robust, defensible decisions next year.
Worldwide High Concentration Glufosinate Ammonium Market
Why 2026 Is a Pivot Year
-
Regulatory recalibration is reshaping addressable demand. Recent approvals and residue‑level updates in major jurisdictions have broadened permitted use cases while simultaneously increasing compliance levers that suppliers must manage. These dynamics accelerate product adoption in some crop systems but raise near‑term registration and stewardship costs.
Worldwide High Concentration Glufosinate Ammonium Market -
Supply‑side shocks and trade policy changes have compressed effective capacity visibility and pushed price discovery earlier in the commercial cycle. Producers with scale or flexible tolling arrangements are capturing margin opportunities; buyers without diversified sources face premium risk exposure.
Worldwide High Concentration Glufosinate Ammonium Market -
Technology and trait adoption (including trait‑stacked seed systems) are changing timing and volume patterns for herbicide demand — creating both growth corridors and tactical inventory timing challenges for formulators and distributors.
What the PW Consulting Report Delivers (Practical, Transaction‑Ready Content)
-
Proprietary market sizing and time‑series models (2020–2025 historical baseline; 2026–2032 scenario suite) calibrated to commercial uptake curves and regulatory milestones.
-
Supply chain mapping down to plant and tolling‑partner exposures, with supplier concentration metrics and three‑tier counterparty risk scores for procurement teams.
-
Price dynamics module incorporating upstream raw material indices, policy shocks, and trade measures to simulate pass‑through and margin outcomes under alternative scenarios.
-
Competitive playbooks and diligence checklists for M&A, JVs, and distribution partnerships — including integration considerations for L‑glufosinate manufacturing and formulation transfer.
-
Regulatory impact matrix and compliance calendar across major markets, tied to commercial triggers (registration windows, tolerance limits, label amendments).
-
Go‑to‑market and channel strategies specific to formulators, generic distributors and trait‑aligned seed partners, together with a rapid‑response communications guide for regulatory or trade disruptions.
Note: this public summary intentionally omits detailed sub‑segment and regional breakdowns included in the full report to preserve competitive value and direct readers to the source for granular datasets and models.
Competitive Landscape: Structure, Players and Strategic Moves
The high‑concentration glufosinate ammonium market shows a moderate‑to‑high degree of concentration: the three largest commercial groups account for a notable majority of global supply, and the top five players consolidate an even larger share. That structure is shaping commercial behavior in three observable ways:
-
Incumbent chemical majors leverage integrated portfolios and brand equity to secure trait‑aligned seed partnerships and to accelerate adoption in large‑acre crops.
-
Large regional producers from Asia have pursued capacity expansion and export orientation, competing on technical supply and scale economics while navigating evolving trade and tax policy headwinds.
-
Generic formulators and distributors have intensified channel partnerships and service differentiation (e.g., local stewardship programs, application training) to protect margin against bulk price volatility.
Core companies reviewed in the report include global agriculture majors that combine portfolio scale and registration reach with specialized producers that are expanding capacity and downstream formulation capability. Each firm demonstrates a distinct strategic posture — from full value‑chain integration and trait‑licensing cooperation to outlet‑focused generics playbooks — and the report provides bespoke recommendations for partnering and competitive responses.
Recent Developments That Should Be in Every 2026 Playbook
-
Policy shifts affecting export economics have immediate supply‑chain implications and require recalibrated sourcing strategies and cost pass‑through models.
-
Regulatory approvals and tolerance decisions in major markets expand end‑use opportunities but also raise label compliance and testing obligations that increase time‑to‑market for new formulations.
-
Notable earnings and capacity announcements from large producers underscore the financial upside of scale in L‑glufosinate manufacturing — and highlight acquisition targets for firms seeking faster capability gains.
Our full timeline maps these events to commercial triggers, showing when buyers, formulators and corporate development teams need to act to capture upside or mitigate downside.
Actionable Strategic Levers for 2026
-
Procurement diversification: establish dual‑sourcing or long‑term supply agreements with graded performance SLAs; prioritize partners offering tolling and substitution flexibility for specialty ingredients.
-
Price risk management: develop layered hedging and contract structures that combine fixed‑price windows with index‑linked components to balance certainty and competitiveness.
-
Regulatory resourcing: align commercial launches to the compliance calendar; invest in residue testing partnerships and label‑to‑market readiness to reduce time lost in registrational bottlenecks.
-
Product and channel differentiation: for formulators, accelerate value‑added services (application advisory, stewardship, digital use monitoring) to defend margin; for seed and trait firms, integrate herbicide strategy into product roadmaps.
-
M&A and capacity plays: evaluate bolt‑on technical production and tolling assets in low‑cost jurisdictions, prioritizing those with export‑compliant certifications and environmental compliance records.
Scenario Planning: Three Paths to 2032
-
Base Case — Steady Scale: adoption follows modeled CAGR driven by trait integration, regulatory clarity, and managed supply growth — producing predictable capacity utilization and profitable rollouts for well‑positioned suppliers.
-
Supply‑Constrained Case — Policy & Cost Shock: trade‑policy shifts and upstream cost spikes compress available technical supply, generating short‑term price stress and advantaging vertically integrated producers and tolling partners.
-
Demand‑Accelerated Case — Rapid Trait Uptake: accelerated adoption for resistance management and broader registration acceptance propel above‑trend growth in selected crop systems, creating procurement shortages and premium pricing for compliant high‑concentration material.
PW Consulting’s interactive models quantify financial, margin and working capital outcomes for each scenario; these tools are included in the full report to support board‑level stress testing and capital allocation decisions.
How Executives Should Use This Analysis Today
-
CEOs and boards: use our scenario suite to test acquisition targets and capex plans against regulatory and trade permutations before committing capital.
-
Commercial leaders: leverage supplier scorecards and channel playbooks to lock in supply and defend pricing across key markets and customer segments.
-
Procurement teams: apply the supply‑chain maps and counterparty risk scores to redesign contracts and inventory strategies for 2026 procurement cycles.
-
R&D and regulatory functions: adopt the compliance calendar and residue modeling to prioritize registration dossiers and label updates aligned with commercial launches.
Next Steps — Where to Find the Full Intelligence
This briefing highlights the decision‑critical takeaways. The full PW Consulting Worldwide High Concentration Glufosinate Ammonium Market report contains the detailed segmentation, per‑plant capacity tables, supplier supply‑and‑demand curves, and the downloadable scenario models that corporations and investors need to move from insight to action. To preserve the commercial value of those datasets, we have purposely kept sub‑segment allocations and granular regional splits out of this public summary.
For governance teams, transaction advisors and commercial leaders preparing 2026 plans: the time to act is now. The combination of regulatory momentum, supplier repositioning and trait evolution is creating both tactical risks and strategic windows of opportunity. PW Consulting’s full report furnishes the models, checklist and playbooks you need to quantify those opportunities and to execute with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide High Concentration Glufosinate Ammonium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Industrial Flexible Hose Market to Expand at a 5.12% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Industrial Flexible Hose Market — Strategic Outlook and 2026 Playbook
Executive snapshot
PW Consulting’s new Worldwide Industrial Flexible Hose Market report (base year 2025; historical range 2020–2025; forecast 2026–2032) equips CEOs, procurement chiefs, product leaders and private-equity sponsors with a pragmatic, decision-focused blueprint for 2026. The global market for industrial flexible hoses has expanded steadily over the past half-decade — rising from just over USD 12 billion in 2020 to approximately USD 15.7 billion in 2025 — and is projected to reach roughly USD 22.3 billion by 2032, corresponding to a compound annual growth rate of 5.12% across the forecast window. While the market remains structurally fragmented (CR3 ≈ 18.5%; CR5 ≈ 28.1%), pockets of technical differentiation and aftermarket capture are creating attractive levers for margin improvement and share consolidation.
Worldwide Industrial Flexible Hose Market
Why this report matters for 2026 decisions
-
Timing: As capital deployment, supplier reconfiguration and product roadmap resets accelerate in 2026, executives must move beyond conventional supplier scorecards toward scenario-ready procurement and engineering playbooks. Our report transforms market growth estimates into tactical choices — when to localize, when to dual-source, and where to accelerate product certification.
Worldwide Industrial Flexible Hose Market -
Risk calibration: Volatile raw-material inputs (for example, a meaningful uptick in natural rubber and fluoropolymer resin prices in recent quarters) and evolving standards (notably updates to hydraulic hose requirements) materially affect total cost of ownership and time-to-market. We quantify the transmission of these shocks into unit economics and replacement cycles to give you defensible sensitivity ranges for 2026 budgeting.
Worldwide Industrial Flexible Hose Market -
Opportunity focus: The growth profile is broad but uneven: some end-use and material combinations are driving higher ASPs and aftermarket demand. The report preserves strategic granularity for subscribers while intentionally omitting detailed segment disclosures in public summaries — directing decision-makers to the full dataset for contract-level and plant-level actions.
Report content — what you’ll get
The PW Consulting report is designed as an action pack, not an academic compendium. It contains:
-
A high-resolution market model (historical 2020–2025; forecast 2026–2032) with scenario modules that translate macro drivers into demand curves and revenue impact at the product-family level.
-
Supplier benchmarking and capability heat-maps covering materials, pressure classes, certification footprints and aftermarket channels, enabling target selection for strategic partnerships or bolt-on acquisitions.
-
Procurement playbooks: step-by-step guidance for cost-out initiatives, including hedging strategies for critical elastomers and resins, TCO templates for insourcing vs. outsourcing, and supplier consolidation thresholds driven by risk-adjusted economics.
-
Manufacturing and footprint optimization: plant-level CAPEX profiles, automation levers, labor-cost sensitivity analyses and a 24–36 month implementation timeline for re-shoring or near-shoring initiatives.
-
Regulation and standards impact assessment: practical actions to adapt to standard updates and to accelerate product recertification cycles with minimal revenue disruption.
-
M&A and alliance playbook: valuation anchors, integration checklists and synergy ranges for targets across the supply chain — from custom rubber fabricators to PTFE-lined specialists.
Competition: how the field shapes strategic choices
The market’s competitive landscape is a mix of global industrial OEMs, specialized independent manufacturers and regional champions. Leading global players such as Gates Corporation (Denver), Parker Hannifin (Cleveland), Eaton (Aeroquip brand), Continental (ContiTech), and Trelleborg are competing on breadth, global channel reach and engineering services. Specialist firms — including Alfagomma, Manuli, Yokohama Rubber, Bridgestone, Goodall, Novaflex, Aflex Hose, Ryco and Pacific Hoseflex — retain strong niche positions in high-spec or regional applications.
Key strategic observations for 2026:
-
Product differentiation is migrating from basic material choice to integrated system performance: abrasion-resistant compounds, hybrid constructions, PTFE-lined solutions and metal-composite assemblies are becoming procurement decision drivers.
-
Trade shows and product launches throughout 2023–2024 (including new thermoplastic and hybrid hose introductions) demonstrate incumbents’ focus on mining, construction, subsea and heavy equipment applications — areas that will dictate capex cycles for end-users in 2026.
-
Fragmentation creates M&A optionality: disciplined roll-ups targeting aftermarket distribution, certification capabilities and rapid prototyping can unlock both margin expansion and defensible regional footprints.
Market dynamics shaping near-term strategy
Several external trends converge to make 2026 a consequential year:
-
Raw-material cost volatility: Natural rubber and fluoropolymer resin price increases observed in late 2024 have tightened gross margins for commodity hose lines and elevated payback thresholds for capital-intensive manufacturing upgrades. Procurement leaders should incorporate rolling price scenarios and supplier pass-through clauses into 2026 contracts.
-
Standards and certification: Recent updates to international standards governing hydraulic hose assemblies create both a compliance cost and a market access advantage for early adopters. Companies that front-load recertification stand to gain share in regulated end-markets.
-
Sectoral capex: Renewed upstream capex in oil & gas and elevated investment in mining and heavy infrastructure translate into multi-year demand tails for specialty hoses — shaping inventory, lead times and aftermarket service strategies.
-
Labor-cost and automation trade-offs: Rising assembly labor rates in established manufacturing markets are accelerating interest in semi-automated assembly cells and standardized subassemblies to protect margins in higher-cost locations.
Actionable recommendations for 2026
Based on modeled scenarios and competitive analysis, PW Consulting recommends a prioritized set of actions for next-year planning:
-
Rebalance procurement toward dual-source agreements with indexed pricing and joint development clauses for high-risk elastomers and resins. Build a 12–18 month raw-material hedge plan aligned with production schedules.
-
Fast-track certification programs for high-potential product families to convert standards updates into market share opportunities rather than cost headwinds.
-
Invest selectively in automation for mid-volume assembly lines where labor-cost trends erode margins; retain manual capability where customization and speed-to-market are primary value drivers.
-
Pursue bolt-on acquisitions that add aftermarket distribution, engineering testing labs or unique material expertise (e.g., PTFE convoluted systems), rather than acreage-focused roll-ups without technical complementarity.
-
Design aftermarket service models (predictive maintenance, certified replacement programs, rapid-response spares) to extend customer lifetime value and reduce cyclicality from OEM sales.
What we deliberately withhold — and why
In keeping with the “trailer” principle of this release, we have shown aggregate market size, growth trajectory and concentration metrics to establish confidence in our methodology and strategic recommendations. To preserve the commercial value of detailed segmentation intelligence — including breakouts by material, region and specific end-use shares that drive plant-level sourcing and pricing decisions — the full subsegment tables and line-item projections are available exclusively in the subscription report. This ensures enterprise clients can act on contract-level insights that deliver measurable ROI in 2026.
Who should read this report
-
Procurement executives evaluating long-term supplier agreements and hedging strategies.
-
Product and R&D leaders planning material investments, certification roadmaps and modular product families.
-
Private-equity investors and corporate development teams seeking disciplined M&A targets to consolidate aftermarket channels and technical niches.
-
Plant operations and manufacturing strategy teams building footprint and automation plans aligned to 2026 demand scenarios.
Next steps
PW Consulting’s Worldwide Industrial Flexible Hose Market report is intentionally built as a toolbox: a quantitative core model, executable playbooks and supplier/pricing intelligence to guide 2026 operational and capital decisions. To access the full report, complete segment-level datasets and executable templates, visit PW Consulting’s report page or contact our industrial practice for a briefing tailored to your company’s positioning and goals.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Flexible Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com