

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Global High-Concentration Glufosinate Ammonium Market Set to Surge at a 14.02% CAGR

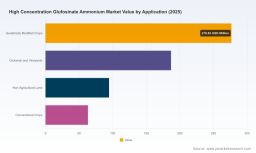
Worldwide High‑Concentration Glufosinate Ammonium Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market intelligence brief, Worldwide High Concentration Glufosinate Ammonium Market (Base Year 2025; Forecast 2026–2032), translates a complex, fast‑moving landscape into prioritized actions for commercial, procurement and corporate strategy teams preparing plans in 2026. Our analysis finds the global market reached approximately USD 621.9 million in 2025 and, under our base forecast, is set to grow at a compound annual growth rate of 14.02% through 2032 — crossing the USD 1.55 billion mark by the end of the projection horizon. This release summarizes the strategic implications embedded in the full report and explains why accessing the complete dataset and scenario models is essential for robust, defensible decisions next year.
Worldwide High Concentration Glufosinate Ammonium Market
Why 2026 Is a Pivot Year
-
Regulatory recalibration is reshaping addressable demand. Recent approvals and residue‑level updates in major jurisdictions have broadened permitted use cases while simultaneously increasing compliance levers that suppliers must manage. These dynamics accelerate product adoption in some crop systems but raise near‑term registration and stewardship costs.
Worldwide High Concentration Glufosinate Ammonium Market -
Supply‑side shocks and trade policy changes have compressed effective capacity visibility and pushed price discovery earlier in the commercial cycle. Producers with scale or flexible tolling arrangements are capturing margin opportunities; buyers without diversified sources face premium risk exposure.
Worldwide High Concentration Glufosinate Ammonium Market -
Technology and trait adoption (including trait‑stacked seed systems) are changing timing and volume patterns for herbicide demand — creating both growth corridors and tactical inventory timing challenges for formulators and distributors.
What the PW Consulting Report Delivers (Practical, Transaction‑Ready Content)
-
Proprietary market sizing and time‑series models (2020–2025 historical baseline; 2026–2032 scenario suite) calibrated to commercial uptake curves and regulatory milestones.
-
Supply chain mapping down to plant and tolling‑partner exposures, with supplier concentration metrics and three‑tier counterparty risk scores for procurement teams.
-
Price dynamics module incorporating upstream raw material indices, policy shocks, and trade measures to simulate pass‑through and margin outcomes under alternative scenarios.
-
Competitive playbooks and diligence checklists for M&A, JVs, and distribution partnerships — including integration considerations for L‑glufosinate manufacturing and formulation transfer.
-
Regulatory impact matrix and compliance calendar across major markets, tied to commercial triggers (registration windows, tolerance limits, label amendments).
-
Go‑to‑market and channel strategies specific to formulators, generic distributors and trait‑aligned seed partners, together with a rapid‑response communications guide for regulatory or trade disruptions.
Note: this public summary intentionally omits detailed sub‑segment and regional breakdowns included in the full report to preserve competitive value and direct readers to the source for granular datasets and models.
Competitive Landscape: Structure, Players and Strategic Moves
The high‑concentration glufosinate ammonium market shows a moderate‑to‑high degree of concentration: the three largest commercial groups account for a notable majority of global supply, and the top five players consolidate an even larger share. That structure is shaping commercial behavior in three observable ways:
-
Incumbent chemical majors leverage integrated portfolios and brand equity to secure trait‑aligned seed partnerships and to accelerate adoption in large‑acre crops.
-
Large regional producers from Asia have pursued capacity expansion and export orientation, competing on technical supply and scale economics while navigating evolving trade and tax policy headwinds.
-
Generic formulators and distributors have intensified channel partnerships and service differentiation (e.g., local stewardship programs, application training) to protect margin against bulk price volatility.
Core companies reviewed in the report include global agriculture majors that combine portfolio scale and registration reach with specialized producers that are expanding capacity and downstream formulation capability. Each firm demonstrates a distinct strategic posture — from full value‑chain integration and trait‑licensing cooperation to outlet‑focused generics playbooks — and the report provides bespoke recommendations for partnering and competitive responses.
Recent Developments That Should Be in Every 2026 Playbook
-
Policy shifts affecting export economics have immediate supply‑chain implications and require recalibrated sourcing strategies and cost pass‑through models.
-
Regulatory approvals and tolerance decisions in major markets expand end‑use opportunities but also raise label compliance and testing obligations that increase time‑to‑market for new formulations.
-
Notable earnings and capacity announcements from large producers underscore the financial upside of scale in L‑glufosinate manufacturing — and highlight acquisition targets for firms seeking faster capability gains.
Our full timeline maps these events to commercial triggers, showing when buyers, formulators and corporate development teams need to act to capture upside or mitigate downside.
Actionable Strategic Levers for 2026
-
Procurement diversification: establish dual‑sourcing or long‑term supply agreements with graded performance SLAs; prioritize partners offering tolling and substitution flexibility for specialty ingredients.
-
Price risk management: develop layered hedging and contract structures that combine fixed‑price windows with index‑linked components to balance certainty and competitiveness.
-
Regulatory resourcing: align commercial launches to the compliance calendar; invest in residue testing partnerships and label‑to‑market readiness to reduce time lost in registrational bottlenecks.
-
Product and channel differentiation: for formulators, accelerate value‑added services (application advisory, stewardship, digital use monitoring) to defend margin; for seed and trait firms, integrate herbicide strategy into product roadmaps.
-
M&A and capacity plays: evaluate bolt‑on technical production and tolling assets in low‑cost jurisdictions, prioritizing those with export‑compliant certifications and environmental compliance records.
Scenario Planning: Three Paths to 2032
-
Base Case — Steady Scale: adoption follows modeled CAGR driven by trait integration, regulatory clarity, and managed supply growth — producing predictable capacity utilization and profitable rollouts for well‑positioned suppliers.
-
Supply‑Constrained Case — Policy & Cost Shock: trade‑policy shifts and upstream cost spikes compress available technical supply, generating short‑term price stress and advantaging vertically integrated producers and tolling partners.
-
Demand‑Accelerated Case — Rapid Trait Uptake: accelerated adoption for resistance management and broader registration acceptance propel above‑trend growth in selected crop systems, creating procurement shortages and premium pricing for compliant high‑concentration material.
PW Consulting’s interactive models quantify financial, margin and working capital outcomes for each scenario; these tools are included in the full report to support board‑level stress testing and capital allocation decisions.
How Executives Should Use This Analysis Today
-
CEOs and boards: use our scenario suite to test acquisition targets and capex plans against regulatory and trade permutations before committing capital.
-
Commercial leaders: leverage supplier scorecards and channel playbooks to lock in supply and defend pricing across key markets and customer segments.
-
Procurement teams: apply the supply‑chain maps and counterparty risk scores to redesign contracts and inventory strategies for 2026 procurement cycles.
-
R&D and regulatory functions: adopt the compliance calendar and residue modeling to prioritize registration dossiers and label updates aligned with commercial launches.
Next Steps — Where to Find the Full Intelligence
This briefing highlights the decision‑critical takeaways. The full PW Consulting Worldwide High Concentration Glufosinate Ammonium Market report contains the detailed segmentation, per‑plant capacity tables, supplier supply‑and‑demand curves, and the downloadable scenario models that corporations and investors need to move from insight to action. To preserve the commercial value of those datasets, we have purposely kept sub‑segment allocations and granular regional splits out of this public summary.
For governance teams, transaction advisors and commercial leaders preparing 2026 plans: the time to act is now. The combination of regulatory momentum, supplier repositioning and trait evolution is creating both tactical risks and strategic windows of opportunity. PW Consulting’s full report furnishes the models, checklist and playbooks you need to quantify those opportunities and to execute with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide High Concentration Glufosinate Ammonium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com