

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Piriformis Syndrome Market Poised to Top USD 320.96 Million by 2032 with 5.51% CAGR

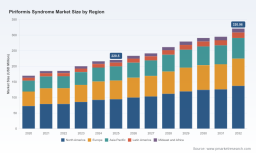
Worldwide Piriformis Syndrome Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting’s latest market intelligence brief on the Worldwide Piriformis Syndrome market delivers a concise, decision-grade view tailored for executive teams planning moves in 2026. Built on a calibrated historical series (2020–2025, base year 2025) and a seven‑year forecast window (2026–2032), the research frames evolution in treatment modalities, reimbursement posture, competitive positioning and technology convergence. At a macro level, the market expanded from roughly USD 170 million in 2020 to USD 220.5 million in 2025 and is projected to continue growing through the forecast, reaching about USD 321.0 million by 2032 — a compound annual growth rate (CAGR) of 5.51% for 2026–2032. These headline metrics are the foundation for scenario planning, deal assessment and product positioning in the year ahead.
Worldwide Piriformis Syndrome Market
Why this matters for 2026 corporate strategy
-
Predictable, mid-single-digit growth creates a low‑volatility environment that is attractive for targeted R&D investments and roll‑out pilots. The consistent growth trajectory gives market entrants and incumbents room to test differentiated therapies without requiring a rapid scale gamble.
Worldwide Piriformis Syndrome Market -
Market concentration is moderate. The top three players account for roughly one‑third of market value while the top five approach half the market, indicating clear leadership but ample space for niche innovation and localized competitors to capture share.
Worldwide Piriformis Syndrome Market -
Payer and coding clarity — especially recent guidance around injection billing and Medicare LCDs addressing botulinum toxin use — reduces uncertainty for commercialization plans that rely on interventional treatments or developer reimbursement strategies.
-
The evidence base is strengthening. Randomized trials and ongoing clinical studies are refining the comparative effectiveness picture across corticosteroid injections, shockwave therapy, manual techniques and minimally invasive procedures. This creates opportunities for evidence‑led market access plays.
-
Convergence across device, pharmaceutical and digital therapy vendors is accelerating. Wearable TENS, injectable biologics/toxins and minimally invasive surgical options are competing on the same value dimension — durable pain relief with low throughput cost and outpatient delivery.
What the PW Consulting report delivers (practical contents)
-
Executive summary with scenario maps keyed to regulatory and payer trajectories for 2026–2032.
-
Full historical market model (2020–2025) and forward projections by treatment pathway and channel, presented with sensitivity runs and high/medium/low adoption cases.
-
Actionable go‑to‑market playbooks for pharmaceutical firms, device manufacturers, specialty clinics and health systems (including recommended pilot geographies and KPI templates).
-
Regulatory & reimbursement navigator covering coding, Medicare LCDs and payer decision triggers that materially affect access and pricing.
-
Competitive landscape deep dives: strategy, pipeline and capability appraisal for established and emerging players — with acquisition and partnership targets prioritized by strategic fit.
-
Investor brief with valuation scenarios and M&A heat‑map informed by concentration metrics and growth drivers.
-
Data annex featuring the complete time‑series market model, assumptions workbook and a reproducible methodology for clients to run bespoke sensitivity analyses.
Competitive landscape — who matters and why
-
Deuk Spine Institute (United States) — A case study in procedural innovation. The institute’s promoted minimally invasive piriformis release procedure highlights how a proprietary, outpatient surgical intervention with a strong safety narrative can shift care pathways. For strategic buyers and partners, the key questions are scaleability, reproducibility outside the origin center and the potential to license the technique or instruments to specialty networks.
-
Allergan (AbbVie) — A mainstream pharmaceutical competitor with established onabotulinumtoxinA assets. The product’s off‑label and adjunctive use for targeted muscle injections positions a large pharma incumbent to influence adoption through clinical sponsorship, payer engagement and integrated care bundles.
-
King Brand Healthcare Products — An example of targeted physical‑modal therapy products (cold/heat wraps) that capitalize on non‑pharmacologic demand. These simple, consumable items underscore revenue diversification opportunities for clinics and retail channels.
-
Bayer, Novartis, Sanofi, Teva, Endo — Large pharma and generic houses maintain market relevance by supplying analgesics, NSAIDs and muscle relaxants. Their strategic choices are typically around labeling, guideline engagement and distribution leverage rather than high‑risk clinical innovation.
-
Omron Healthcare and digital/wearable vendors — Represent the non‑invasive device cohort. Promotion of wearable TENS devices by digital health players demonstrates a route to recurring revenue and direct‑to‑consumer adoption that bypasses some traditional provider bottlenecks.
-
Market implications — The mix of specialty innovators (procedural developers), large pharma and device/digital entrants suggests a multi‑modal competitive set. Partnerships (e.g., pharma + device + clinic networks) are likely to be the most effective route to scale given payer preferences for demonstrable outcomes and cost offsets.
Regulatory, reimbursement and clinical signals shaping 2026
-
Coding and billing guidance from major payers is converging on clearer rules for injections and interventional coding — reducing friction for outpatient procedures where needle guidance imaging has unclear marginal benefit.
-
Medicare local coverage determinations recognize the reasonable necessity of botulinum toxins for certain refractory indications when criteria are met — a favorable precedent for payer coverage pathways that companies can leverage.
-
FDA approvals for several botulinum toxin products create a predictable regulatory backdrop for toxin‑based interventions, although off‑label use and evidence generation remain important for piriformis‑specific claims.
-
Clinical practice conservatism: surgery is still predominantly reserved for refractory cases after conservative and interventional therapies fail. This slows rapid uptake of invasive options but rewards minimally invasive outpatient approaches that demonstrate durable outcomes.
Recent developments that matter for near‑term strategy
-
April 2026 — Promotion of a patented minimally invasive piriformis release procedure (as an outpatient technique) underlines how procedural IP can be commercialized via center‑of‑excellence models before broader rollout.
-
April 2026 — Publication of a randomized controlled trial comparing corticosteroid injection vs extracorporeal shockwave therapy adds comparative evidence that payers and guideline committees will scrutinize when defining coverage criteria.
-
March 2026 — Active promotion of wearable TENS devices highlights a parallel adoption pathway that could erode some demand for clinic‑delivered interventions if robust real‑world effectiveness is demonstrated.
-
Ongoing — Multiple clinical trials listed on clinical registries continue to explore manual techniques, shockwave therapy and procedural options; readouts over the next 12–24 months will be pivotal to market share assumptions.
Strategic playbook for 2026 — six executable moves
-
Prioritize evidence generation: sponsor pragmatic trials that demonstrate real‑world comparative effectiveness and health economic benefits (QALYs, reduction in downstream opioid use, decreased throughput costs).
-
Secure coding & reimbursement readiness: prepare LCD dossiers and engage early with payer medical directors to expedite favorable coverage determinations for new procedures or device‑drug bundles.
-
Pursue asymmetric partnerships: device makers should seek pharma collaborations to combine procedural and pharmacologic approaches into bundled offerings; specialty clinics can partner on commercial pilots to validate outpatient pathways.
-
Test direct channels for low‑touch solutions: scale wearable and OTC pain relief offerings via digital marketing pilots to ascertain incremental market capture without heavy provider dependence.
-
Adopt a staged geographic expansion: use outcome data from centers of excellence to support payer negotiations in successive jurisdictions rather than broad simultaneous launches.
-
Model M&A with concentration context: given the market’s moderate concentration, small‑to‑mid size strategic acquisitions (clinical networks, specialized device firms, or proprietary procedural platforms) are likely to be accretive without triggering large antitrust hurdles.
Signals to monitor closely through 2026
-
Key trial readouts and meta‑analyses that shift comparative effectiveness rankings.
-
Payer LCD updates or national coverage decisions affecting interventional and toxin‑based therapies.
-
Scaling metrics from early procedural adopters (complication rates, time‑to‑discharge, repeat intervention rates).
-
Device adoption curves for wearables and clinic‑based TENS units, and their demonstrated impact on clinic visit volumes.
-
Regulatory moves or guideline endorsements that alter the point at which surgery is recommended.
PW Consulting’s Worldwide Piriformis Syndrome market brief is designed to be immediately operational for leadership teams grooming product roadmaps, payer strategies, and M&A pipelines in 2026. This preview outlines the strategic signals we believe will shape the year ahead — but the full report contains the granular segmentation tables, regional and channel split models, company market shares and the scenario workbooks you will need to build executable plans.
To access the complete dataset, detailed company profiles, and our tailored recommendations for your organization, please download the full report or contact PW Consulting for a customized briefing and model walk‑through.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com