

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Thoracic Drainage Devices Market to Reach USD 1,459.38 Million by 2032

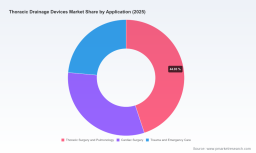
Worldwide Thoracic Drainage Devices Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide Thoracic Drainage Devices presents a forward‑looking, action‑oriented analysis designed to inform executive decisions in 2026. Anchored on a 2025 base year and projecting through 2032, the study quantifies a resilient market trajectory — from a 2025 market size of approximately USD 940 million to a pathway that surpasses USD 1.45 billion by 2032 under the base forecast, reflecting a compound annual growth rate of 6.48% across the 2026–2032 horizon. This press release summarizes the study’s strategic value, highlights critical industry dynamics, and outlines the practical tools executives can use immediately — while reserving the detailed segment tables and scenario spreadsheets for the full report.
Worldwide Thoracic Drainage Devices Market
Why this report matters for 2026
- Translate macro growth into portfolio prioritization: use the report to decide which thoracic drainage investments should be accelerated versus rationalized.
- Align R&D and regulatory timelines: understand how FDA 510(k) dynamics and electrical safety expectations for digital systems affect time‑to‑market.
- Mitigate short‑term supply and competitive shocks: learn which vendor changes and recalls create near‑term openings for market share capture or partnership.
- Target commercial models and contracting: use reimbursement and procedure coding intelligence to optimize hospital procurement and value‑based purchasing plays.
Market trajectory and strategic implications
The thoracic drainage devices market has demonstrated steady recovery and modernization over the past five years. After navigating pandemic‑era elective procedure fluctuations, market value reached around USD 940 million in 2025. PW Consulting’s base forecast projects a continuation of demand expansion, with the market exceeding USD 1.0 billion in 2026 and growing at a mid‑single‑digit CAGR (6.48%) to reach approximately USD 1.46 billion by 2032 under central assumptions.
Worldwide Thoracic Drainage Devices Market
Several structural drivers underpin this outlook:
Worldwide Thoracic Drainage Devices Market
- Persistent demand from post‑operative thoracic and cardiothoracic procedures and trauma care — procedural volumes and clinical practice patterns remain the primary demand anchors.
- Rapid adoption of digital chest drainage solutions that offer objective air‑leak monitoring, mobility benefits, and data capture for patient pathways; these product innovations command premium pricing and create upgrade cycles.
- Increasing focus on shortening length of stay and facilitating early ambulation, which favors compact, wearable and digital drainage systems with robust clinical evidence supporting safety and cost offsets.
- Regulatory and reimbursement environments that reward demonstrated outcomes and interoperability with hospital information systems, shaping procurement choices in high‑volume centres.
Competitive landscape — strategic reads on the leading players
The market’s competitive structure is moderately consolidated; the three largest players control a meaningful share, while the top five capture a majority of revenue. This mix creates both stability and opportunity for challenger brands.
- Becton, Dickinson and Company (BD) — As an entrenched supplier of chest tubes and drainage catheters, BD remains a strategic partner for health systems focused on procurement scale and trusted clinical familiarity. For executives: evaluate BD primarily as a platform partner for broad clinical adoption and bundled supply strategies.
- Getinge AB (Atrium) — Atrium’s product breadth across dry‑seal and water‑seal solutions positions Getinge well in hospitals looking for versatile portfolios. Their presence in both adult and pediatric niches implies opportunities for differentiated product placements and OR/ICU cross‑sell.
- Cardinal Health — Recent strategic moves have materially changed Cardinal’s role: the announced US commercial discontinuation of select chest drainage lines (effective late 2025) followed by a Class II device recall in early 2026 have created near‑term distribution and inventory dislocations. For competitors and customers, this is both a supply risk and an addressable opportunity. Tactical recommendations include contingency sourcing, short‑cycle contracting, and targeted promotional programs to capture reallocated volume.
- Teleflex, Cook Medical, Vygon, Utah Medical — These companies compete on product range and catheter design. Their strengths are in direct clinician relationships and procedural familiarity; they are natural partners for incremental product upgrades and procedure‑specific solutions.
- Medtronic, Medela, ATMOS, Centese — These firms are at the forefront of digital thoracic drainage. Medela’s Thopaz+ and ATMOS C 051 exemplify the trend toward objective air‑leak monitoring and enhanced patient mobility. Centese’s Thoraguard brings automation (clog clearance and quantitative drainage measurement) into the clinical conversation. For strategy teams, digital capability and data services are now differentiating features that justify premium pricing and new procurement categories.
- Regional and emerging manufacturers (Redax, Sinapi Biomedical, Sterimed, Angiplast) — These players provide localized manufacturing, cost‑competitive products, and increasing technical sophistication. They are critical partners for volume deployments in price‑sensitive markets or for OEM/contract manufacturing strategies.
Recent industry developments that affect 2026 planning
- Regulatory event: Cardinal Health’s device recall (Class II) announced in early 2026 creates short‑term clinical and procurement disruption. Hospitals and group purchasing organizations should reassess inventory and vendor continuity plans immediately.
- Commercial exit: Cardinal’s prior announcement to discontinue certain chest drainage units in the US (effective November 2025) has already shifted the competitive landscape; expect competitors to accelerate field campaigns for dislocated accounts.
- Technology and regulatory clearance: New entrants and adjacent‑tech firms (e.g., FluidAI Medical’s 510(k) clearance in 2025) are expanding monitoring capabilities around surgical drainage, signaling an influx of software‑enabled adjuncts and new data monetization vectors.
- Clinical engagement and visibility: Regional innovators such as Sinapi Biomedical actively participating in cardiothoracic forums show the importance of trade show presence and surgeon engagement in adoption pathways.
Regulatory and reimbursement dynamics executives must internalize
Thoracic drainage devices in the U.S. are predominantly regulated as Class II devices via the FDA 510(k) pathway. Digital and electrically powered drainage systems must also meet consensus standards for electrical safety and performance, extending product development and validation timelines. On the reimbursement side, thoracic procedures involving chest tube insertion are coded under established CPT listings (e.g., CPT 32551) and linked to APCs and MS‑DRG payments that consider case severity and CC/MCC status — a nuance that materially affects hospital economic modeling for product adoption.
Strategic playbook for 2026 (practical actions)
- Prioritize digital drainage investments where clinical evidence can be generated within 12–18 months: pilot programs that produce LOS and readmission data accelerate contracting wins.
- Execute immediate supply continuity plans: identify alternative suppliers, build buffer inventories for high‑volume accounts, and negotiate flexible restocking terms to mitigate recall/discontinuation risk.
- Reassess pricing and contracting frameworks: structure value‑based agreements that link device fees to measurable outcomes (e.g., days to chest tube removal, LOS reduction).
- Pursue tuck‑in M&A or distribution agreements to capture reallocated volumes in markets affected by recent commercial exits; focus on companies with digital capability or unique catheter technologies.
- Invest in regulatory engineering for digital systems early: compliance with electrical and interoperability standards should be designed into hardware and software roadmaps to avoid late‑stage rework.
- Localize manufacturing and service models for price‑sensitive geographies via licensing or contract manufacturing partnerships to improve margin resilience and procurement flexibility.
What’s in the PW Consulting report (practical deliverables)
The full report blends market intelligence with executable toolkits tailored for deal teams, commercial leaders, and R&D heads. Highlights include:
- Market sizing and scenario forecasts (2020–2032) with upside/downside scenarios and sensitivity analyses for procedure volumes, pricing, and adoption curves.
- Competitive landscaping: detailed profiles, product maps, and go‑to‑market playbooks for the leading incumbents and emerging challengers.
- Regulatory and reimbursement playbooks: step‑by‑step guidance on 510(k) strategy, electrical safety requirements, and hospital coding/revenue impact modeling.
- Commercial tools: sample tender language, value‑story slides for hospital committees, and contracting templates tied to outcomes metrics.
- Innovation scouting and M&A pipeline: prioritized targets and integration risk checklists, plus a 90‑day capture plan for displaced volumes after vendor exits.
- Operational risk matrix and supplier continuity model that quantify exposure from recalls, single‑source components, and regional manufacturing constraints.
Conclusion — how to use this insight in 2026
For C‑suite executives, the strategic question for 2026 is not whether the thoracic drainage market will grow — it will — but how to position the organization to capture premium growth driven by digital adoption, clinical outcomes, and supply resilience. The market’s mid‑single‑digit CAGR and the expected uplift to well over USD 1.4 billion through 2032 create opportunities for companies that combine product innovation with pragmatic commercialization and regulatory execution.
PW Consulting’s full report contains the underlying segment models, scenario spreadsheets, and competitive scorecards necessary to convert these insights into boardroom decisions. To access the complete dataset, segmentation tables, and step‑by‑step playbooks that support M&A, product investment, and market entry strategies, please consult the full report on the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com