

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Complicated UTI Treatment Market Poised to Expand at a 6.5% CAGR Through 2032

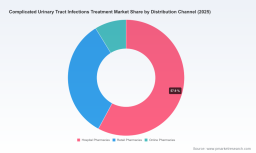
Worldwide Complicated Urinary Tract Infections (cUTI) Treatment Market — A Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Complicated Urinary Tract Infections Treatment Market is calibrated to the needs of senior executives, corporate strategists, portfolio managers, and policy-makers preparing for the decisive planning cycle of 2026. The report converts a complex and rapidly evolving therapeutic space into pragmatic, decision-ready intelligence — showing where value will be created, who will capture it, and which operational choices will most materially affect outcomes over the 2026–2032 forecast window.
Worldwide Complicated Urinary Tract Infections Treatment Market
Why this report matters for 2026 strategy
-
Clear macro trajectory: The cUTI treatment market demonstrates steady expansion, underpinned by both demand-side clinical pressures and supply-side innovation. Our analysis uses a 2025 base year and models the market forward to 2032, incorporating historical trends (2020–2025) and scenario-adjusted assumptions for the 2026–2032 forecast period, projecting a compound annual growth rate of roughly 6.5% through 2032.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Investment timing: The timing of late-stage clinical readouts, regulatory decisions, and patent cliffs in the 2026–2028 window will reshape competitive dynamics. Our report highlights the inflection points that should guide R&D budgets, licensing decisions, and M&A prioritization for the 2026 planning round.
Worldwide Complicated Urinary Tract Infections Treatment Market -
Actionable implications: Rather than offer only descriptive market sizing, the study emphasizes operational playbooks — from supply-chain mitigation to formulary positioning — so that leadership teams can translate market signals into executable plans in 2026.
Market trajectory in context
Between 2023 and 2025 the market expanded materially from the low- to mid-thousand-million dollar range and continues on a steady upward path into the forecast period. Our base-year 2025 calibration anchors a forward projection that reaches northward over the next seven years, driven by a mix of novel antibacterial approvals, expanded indication use, and persistent clinical need for effective empiric and directed therapies in complex inpatient and complicated outpatient settings. The modeled 6.5% CAGR for 2026–2032 embodies both conservative uptake assumptions for newer agents and upside from improved stewardship and reimbursement alignment.
What’s included — practical, executable sections
-
Market sizing & forecast: A transparent, reproducible financial model with topline projections, sensitivity tables, and scenario variants calibrated to different adoption curves and pricing trajectories.
-
Clinical and pipeline review: Deep, agent-level dossiers covering approved products, late-stage candidates, mechanism-of-action overlays, and probability-adjusted launch timelines.
-
Regulatory & reimbursement intelligence: Country- and region-specific regulatory milestones, QIDP impacts, exclusivity windows, and payer positioning analysis that directly inform launch sequencing and pricing strategies.
-
Competitive benchmarking: A strategic matrix mapping capability, commercial reach, clinical differentiation, and vulnerability to generic threats for key players.
-
Supply-chain risk assessment: Identification of critical API dependencies, shortage scenarios, and recommended mitigation constructs — from dual-sourcing to long-term supplier contracts.
-
Go-to-market playbooks: Tactical roadmaps for hospital formulary access, outpatient stewardship engagement, and digital/remote distribution models, including online pharmacy dynamics.
-
M&A and partnership targets: A prioritized list of tuck-in candidates, licensing archetypes, and collaboration structures optimized for mid-sized and large pharma buyers.
Competitive landscape — who matters and why
The cUTI market is contested across several fronts: novel chemical entities and combinations addressing resistant Gram-negative pathogens; extended-spectrum beta-lactamase and carbapenemase-active agents; and oral agents that enable early transition of care. Key industry participants covered in our report include long-standing large-cap antimicrobial franchises and agile specialty biotechs that have advanced novel pathways to market. The strategic roles of those players are summarized below (profiles and deeper competitive analysis are included in the full report).
-
Merck & Co., Inc. — leverages a marketed cephalosporin-beta-lactamase inhibitor combination with established hospital positioning and formulary presence. Its commercial footprint and clinical evidence base make it a baseline comparator for new entrants.
-
GlaxoSmithKline plc — markets a cephalosporin/β-lactamase inhibitor that has received regulatory approvals in major jurisdictions for limited-option patients; regulatory precedent in Europe strengthens its specialty hospital access.
-
Pfizer Inc. — maintains broad distribution and lifecycle strategies around approved ceftazidime-avibactam therapy, with a strong hospital sales force and existing payer relationships that support utilization in complicated cases.
-
Allergan (AbbVie Inc.) — while better known in other therapeutic areas, it participates in the cUTI arena via agents that have both labeled and off-label hospital use; portfolio integration and hospital access are its strategic levers.
-
Basilea Pharmaceutica Ltd. — a smaller innovator with complementary assets and partnership models focused on resistant infections; its positioning demonstrates how mid-sized players can influence niche resistant strains through targeted collaborations.
-
Spero Therapeutics, Inc. — represents a textbook late-stage disruptor: an oral carbapenem prodrug with QIDP signaling and positive Phase 3 topline results that could materially alter outpatient and early-discharge pathways if approved and commercialized efficiently.
-
VenatoRx (formerly Entasis) — the recent approvals for agents active against Acinetobacter highlight the market’s shift toward addressing highly resistant hospital pathogens and the commercial opportunities tied to acute-care stewardship and infection control budgets.
Recent regulatory and market events that shape 2026 choices
-
Regulatory incentives and exclusivity matter. QIDP designations and associated review accelerations materially shorten time-to-revenue for qualifying molecules and create five-year exclusivity windows in the U.S.; these factors should be central to portfolio cadence planning.
-
Approvals and paradigm shifts. Recent FDA approvals for agents targeting resistant Gram-negative pathogens have created both clinical precedent and commercial pathways for similarly positioned launches — but each approval also raises the bar for comparative-effectiveness evidence demanded by hospitals and payers.
-
Patent timelines. Approaching patent expirations on core agents (notably mid-decade cliffs for certain beta-lactam/beta-lactamase inhibitor combinations) will reshape pricing dynamics and generic entry strategies; companies need to model erosion curves and bundling strategies for 2026 budgeting.
-
Supply-side fragility. Documented API shortages for legacy penicillin-derived combinations have already disrupted hospital ordering patterns; as utilization rebounds post-pandemic, resilience investments (dual sourcing, strategic inventories) will command board-level attention.
-
Reimbursement nuances. Inclusion on public formularies and tiering decisions materially influence hospital and outpatient uptake. The interplay of copay tiers, hospital DRG incentives, and stewardship policies creates both obstacles and leverage points for commercialization.
Strategic recommendations for 2026 planning
-
Prioritize launch sequencing based on regulatory runway and formulary friction. For companies with late-stage assets, allocate concentrated commercial resources to territories where regulatory precedence and reimbursement mechanics reduce time-to-adoption.
-
Embed supply-chain resiliency into go-to-market budgets. Allocate capital for redundant API sourcing and contingency inventories, and negotiate contractual protections (price collars, force majeure clauses) to hedge against recurrence of shortages.
-
Differentiate through stewardship-aligned evidence. New agents should be launched with protocols and real-world evidence programs that demonstrate reductions in length of stay, need for escalation to intensive care, or readmission rates — financial endpoints that payers and hospital CFOs value most.
-
Use selective partnerships to de-risk commercialization. For mid-sized innovators, co-promotion agreements or regional licensing can unlock commercialization scale while preserving upside; for big pharma, targeted bolt-on acquisitions can rapidly fill pipeline gaps where internal programs are late or uncertain.
-
Prepare for generic/differentiated competition. Model the financial impact of patent expirations and construct tiered defense plans — lifecycle management, clinical differentiation, and indication expansion — to preserve value into the late-2020s.
-
Reassess distribution strategy in light of digitization. Online pharmacy channels and outpatient infusion/transition-of-care models are rising; companies should pilot hybrid distribution and remote-support models to maximize patient access while maintaining stewardship oversight.
How PW Consulting’s report supports boardroom decisions in 2026
Our study is intentionally engineered as a “strategy-to-execution” toolkit. Beyond headline market trajectories, it delivers executable inputs for 2026 budgeting and scenario planning: probability-weighted revenue paths for candidate launches, prioritized lists of M&A targets and partnership archetypes, a negotiable playbook for hospital access negotiations, and a suite of metrics to track early-launch health. The result is a single reference that reduces strategic uncertainty and expedites decision cycles.
Next steps — a discreet preview offer
This executive brief demonstrates the analytical scaffolding and strategic outcomes you can expect from the full PW Consulting report. To access the complete dataset, agent-level dossiers, and the reproducible financial model (including all sensitivity analyses and scenario outputs), please visit our report landing page. The full report contains the precise segmentation tables, region- and channel-level forecasts, and the granular competitive benchmarks omitted here as part of our “trailer” approach to preserve the actionable premium contained in the complete deliverable.
For a tailored briefing or to commission a bespoke extension (e.g., country-level forecasts, payer-value dossiers, or bespoke M&A target screens tied to your portfolio), PW Consulting’s life sciences practice is available for immediate engagement as firms finalize 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com