

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Food Encapsulating Technology Market to Reach USD 19.93 Billion by 2032, Growing at an 8.12% CAGR

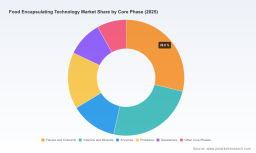
Worldwide Food Encapsulating Technology Market — Strategic Outlook for 2026 Decision-Makers
As food manufacturers, ingredient suppliers, and strategic investors prepare plans for 2026, the global market for food encapsulating technologies has reached an inflection point. Our newest market study from PW Consulting establishes a clear macro trajectory: the market expanded markedly through the early 2020s and, with robust fundamentals, is projected to continue growing into the early 2030s at a compound annual growth rate of 8.12%. With a 2025 base-year close to USD 11.6 billion and an anticipated rise toward the high‑single‑digit‑billion range by 2032, the sector offers both scale opportunities for incumbents and fertile ground for differentiated entrants.
Worldwide Food Encapsulating Technology Market
Why this market matters for 2026 decision cycles
-
From ingredient stability to label claims, encapsulation is now an enabling technology that translates scientific advantage into commercial differentiation across an expanding set of food and beverage categories.
Worldwide Food Encapsulating Technology Market -
Macro drivers — demographic demand for fortified and convenient nutrition, sustainability pressures on formulation and packaging, and regulatory attention to fortification and food safety — align to make encapsulation a strategic lever rather than a niche R&D line item.
Worldwide Food Encapsulating Technology Market -
Capital allocation decisions made in 2026 (R&D budgets, pilot lines, M&A/partnerships, and manufacturing expansions) will determine market positioning for the remainder of the decade. Timing matters: capacity and validated IP invested now will compound value as adoption accelerates.
What PW Consulting’s report delivers — practical, actionable intelligence
Beyond headline numbers, the report is structured to turn market insight into executable choices for 2026 planning. Key deliverables include:
-
Macro forecast and scenario analysis with upside/downside paths tied to ingredient‑level adoption rates and regulatory shifts.
-
Technology performance matrix comparing spray drying, spray chilling, fluid‑bed coating, extrusion and emergent plant‑protein microcapsules across stability, sensory impact, release profile, and scale economics.
-
Commercialization playbooks — from pilot to full production — with CAPEX benchmarking, typical scale‑up failure modes, and go/no‑go criteria for plant investment.
-
Supplier and partner maps that pair formulation needs (e.g., fat‑soluble vitamins, probiotics, flavors) with wall‑material expertise and toll‑manufacturing capacity.
-
Regulatory and compliance checklist tailored to fortified foods, probiotic claims, and novel ingredient delivery systems, including food safety measures for bacteriocin/antimicrobial encapsulation.
-
Commercial insights: pricing dynamics, tender and volume pricing playbooks, and recommendations for structuring long‑term offtake and raw‑material hedging contracts.
To preserve commercial intent and to respect client confidentiality in this pre-release narrative, granular regional and application breakdowns—our most sensitive segmentation tables—are intentionally omitted here. The full report provides those tables and interactive models for subscribers and corporate clients.
Strategic imperatives for 2026
-
Prioritize capability, not just capacity. Investments should pair production scale with targeted formulation expertise (e.g., enteric release for probiotics, stability for fat‑soluble vitamins). A new high‑capacity facility creates value only if paired with validated process‑ingredient know‑how.
-
Portfolio segmentation by value‑capture, not only by application. Differentiate product lines by customer willingness‑to‑pay: premium functional ingredients with controlled release versus low‑margin commodity flavor encapsulates.
-
Lock in wall‑material supply chains. Polysaccharides (starches, maltodextrins, gum arabic) and proteins (whey, soy, pea) remain core inputs; securing feedstocks and contingency suppliers is a near‑term priority.
-
Design for regulatory alignment and label‑friendly claims. Encapsulation can enable compliance with tightening fortification and labeling requirements while supporting clean‑label narratives; incorporate regulatory teams early in product development.
-
Use partnership and licensing to accelerate capability buildout. The market concentration profile shows leading players hold meaningful share but not complete dominance, creating openings for co‑development, licensing, and framed acquisitions.
Competitive landscape: who to watch and how they shape strategy
The competitive field combines global ingredient majors, flavor houses, and specialist encapsulation firms. Understanding each archetype helps firms pick the right competitive or partnership posture:
-
Large ingredient integrators (examples: global agribusiness and starch specialists) bring scale manufacturing, carbohydrate science, and route‑to‑market strength. Their advantage is rapid scale and wide distribution networks — an essential partner for commoditized encapsulates and beverage systems.
-
Flavor and premix multinationals offer integrated taste and delivery systems. Their R&D footprints and application labs let them bundle sensory optimization with delivery performance — a compelling proposition for finished‑goods customers seeking simplified supplier relationships.
-
Specialist microencapsulation firms focus on technical performance and niche release profiles. They are sources of disruptive IP and frequently become targets for licensing or acquisition by larger players aiming to fill capability gaps.
-
New‑wave entrants and bio‑based innovators are introducing sustainable wall materials and plant‑protein based capsules, targeting clean‑label and environmental narratives crucial to many consumer categories.
Two recent industry developments illustrate distinct strategic playbooks. First, a major microencapsulation supplier announced a capacity expansion, signaling confidence in long‑term demand and a move to secure industrial‑scale supply for bakery, confectionery, and meat applications. Second, a plant‑protein microcapsule developer published peer‑reviewed validation showing protection of fat‑soluble nutrients through processing and enteric release, underscoring both the technical maturity of alternative wall materials and the commercial appeal of sustainability‑based differentiation.
These moves show parallel trends: incumbent consolidation around scale and emergent technology validation that lowers entry barriers for sustainable alternatives. Both trends demand active response from market participants.
Operational playbook for near‑term execution
-
R&D: Run 6–12 month de‑risking sprints focused on the top three delivery challenges: oxidative protection, taste masking, and targeted release. Use accelerated shelf‑life protocols and simulated digestion studies to validate claims.
-
Piloting: Establish modular pilot lines capable of spray drying and fluid‑bed coatings. Prioritize flexible lines that can run multiple wall materials to respond quickly to customer demand.
-
Supplier strategy: Qualify at least two suppliers for each critical wall material and negotiate supply‑chain resilience clauses. Consider toll‑manufacturing partnerships to meet near‑term demand spikes while longer‑term CAPEX is evaluated.
-
Commercial: Reframe sales teams to sell benefits (stability, label claims, sensory) rather than unit costs. Build case studies showing reduced restitution, extended shelf life, and consistent dosing as the basis for premium pricing.
Risk map and mitigation
-
Raw material volatility: Lock in indexed contracts and create reformulation contingencies for key polysaccharides and proteins.
-
Regulatory uncertainty: Invest in regulatory foresight and scenario planning for regional labeling changes and novel‑ingredient pathways.
-
Scale failure: De‑risk scale up with staged investments—pilot → semi‑works → full plant—and use contract manufacturing to bridge capacity gaps.
-
Competition and margin compression: Use IP, co‑development agreements, and branded ingredient programs to protect margins.
How PW Consulting’s data supports 2026 capital and commercial choices
The report’s integrated forecast and scenario modules translate the macro CAGR and market size trajectory into discrete capacity and revenue build models for the next six years. It couples these projections with vendor benchmarking, process KPIs, and a regulatory compliance roadmap — the inputs that CFOs and strategic planners need to build defensible five‑year CAPEX proposals and commercial rollout plans.
Importantly, we have intentionally withheld the full granular regional and application‑level tables in this summary to preserve the strategic value of the complete dataset. Those detailed breakdowns—critical for deciding where to invest production capacity, which applications to prioritize, and which customers to target—are available in the full report and our interactive subscription portal.
Final recommendation
For leaders setting 2026 priorities: treat food encapsulation as a strategic capability that combines material science, process engineering, and regulatory navigation. If you are a manufacturer, accelerate pilots and secure partnerships to ensure you can translate ingredient innovation into marketable, label‑compliant products. If you are an investor or acquirer, focus on validated IP, proven scale‑up pathways, and firms that bridge sustainability claims with demonstrable performance.
PW Consulting’s Worldwide Food Encapsulating Technology Market report provides the detailed forecasting, vendor intelligence, and operational playbooks needed to act with confidence in 2026. Access the full dossier for the complete segment and regional tables, vendor scorecards, and interactive scenario tools that we use with our corporate clients to convert market insight into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Food Encapsulating Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com