

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Wearable Injectors Market Poised to Grow at 13.5% CAGR Over 2026–2032

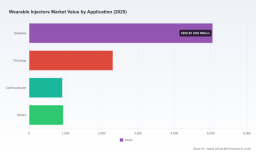
Worldwide Wearable Injectors Market — Strategic Outlook for 2026: Key Imperatives from PW Consulting
PW Consulting’s new market study, Worldwide Wearable Injectors Market (base year 2025, forecast 2026–2032), translates the rapid commercial maturation of wearable drug delivery into an actionable corporate playbook for 2026 decision‑makers. The market has moved from an early-adopter phase into sustained commercial scale: global revenue expanded from the mid‑single billions in 2020 to approximately USD 9.2 billion in 2025, and our base forecast—anchored to observed commercialization, regulatory milestones and technology adoption curves—projects a compound annual growth rate (CAGR) of 13.5% across 2026–2032, driving the market into the low‑double‑decade billions by the end of the forecast horizon. This study is designed to be the operational blueprint for executives needing to convert strategic intent into executable programs in 2026.
Worldwide Wearable Injectors Market
Why 2026 is the pivotal year
-
Commercial inflection. Several platform vendors converted development pipelines into commercial agreements and regulatory clearances in 2024–2025, creating tangible go‑to‑market paths for pharma partners and payers. These moves accelerate adoption timelines for large‑volume subcutaneous biologics and broaden therapy areas beyond diabetes into oncology, immunology and chronic disease management.
Worldwide Wearable Injectors Market -
Regulatory and reimbursement clarity. Evolving device standards and clearer reimbursement codes are shortening commercialization risk cycles. Compliance requirements such as ISO 11608‑01:2012 for needle‑based systems and IEC 60601‑1 for electrical safety are now front‑and‑center in product development roadmaps, and the availability of HCPCS codes for wearable injector supplies has materially improved Medicare coverage predictability in the U.S.
Worldwide Wearable Injectors Market -
Platform consolidation and partnership momentum. Strategic alliances and supply agreements announced in 2024–2025 indicate a market shifting from point solutions to integrated platform/pharma models. The pattern we observe will determine licensing, revenue share and service‑bundle strategies that corporate leaders must decide in 2026.
What the report delivers — practical, transaction‑ready content
-
Comprehensive market sizing and methodology. A reproducible top‑down and bottom‑up approach covering historical (2020–2025) and scenario‑based forecasts (2026–2032), with sensitivity runs that map revenue outcomes to key adoption variables.
-
Go‑to‑market playbooks. Market entry templates by therapy cluster, payer engagement roadmaps, and commercial contracting examples designed for pharma/device co‑development and commercialization.
-
Regulatory pathway maps and checklists. Stepwise requirements for device classification, safety testing, clinical comparators and post‑market surveillance aligned to major jurisdictions.
-
Manufacturing, sourcing and cost levers. Bill‑of‑materials benchmarking, low‑cost material strategies, and supplier selection filters—grounded in current inputs such as medical‑grade polymer pricing and production scale curves.
-
Competitive and partnership landscape. Operator profiles, strategic positioning matrices, technology readiness assessments and partnership diligence templates for licensing, supply and commercialization agreements.
-
Investment, M&A and valuation guidance. Playbook for buy, build or partner choices, with deal comparators and integration risk checklists tailored to wearable injectors.
-
Risk matrices and mitigation plans. Practical contingencies for regulatory delays, component shortages, and reimbursement revisions—each paired with execution checklists.
Competitive landscape — what leading vendors signal to the market
The sector is characterized by a mix of specialised device firms, incumbent pharmaceutical partners, and regional low‑cost entrants. Rather than enumerate sensitive segment shares here, PW Consulting’s report provides detailed benchmarking; below we summarize strategic positioning and implications for 2026 strategy:
-
Ypsomed (Switzerland — https://www.ypsomed.com): A mature on‑body platform vendor with strong product heritage and recent investments in connectivity. Its next‑generation platform emphasizes real‑time dose monitoring and integration with digital therapeutics — a clear signal that clinical and adherence data will increasingly be negotiated as part of commercial contracts.
-
West Pharmaceutical Services (USA — https://www.westpharma.com): A device incumbent translating component supply strength into system‑level offerings. Recent commercial supply agreements highlight a route to co‑development that leverages legacy pharma relationships; companies considering scale should evaluate supply security and partner IP control when negotiating licensing terms.
-
Enable Injections (USA — https://enableinjections.com): A regulatorily validated entrant with 510(k) clearances that shortens the time to market for partners. The availability of FDA‑cleared variants reduces clinical and regulatory execution risk for therapeutics seeking subcutaneous large‑volume delivery.
-
Stevanda (India — https://www.stevanda.com): Focused on cost‑competitive platforms for emerging markets. Their presence underscores geographic segmentation strategies: low‑cost offerings can expand addressable markets if paired with appropriate regulatory and distribution models.
-
Medipim (Belgium — https://www.medipim.com) and Nexus Pharmaceuticals (USA — https://www.nexuspharma.com): Both illustrate differentiated approaches — multi‑day delivery and partnership distribution models respectively — that expand use‑cases beyond single‑dose self‑administration.
Regulatory and reimbursement dynamics — actionable implications
-
Standards compliance is non‑negotiable. Device programs must demonstrate adherence to ISO 11608‑01:2012 and relevant electrical safety standards like IEC 60601‑1 early in development. Incorporate standardized test plans into vendor RFQs to avoid late‑stage redesigns.
-
Reimbursement tractability accelerates commercial uptake. The presence of specific HCPCS identifiers for wearable injector supplies has created a pragmatic pathway for Medicare coverage in the U.S.; payer dossiers should anticipate and document real‑world adherence and cost‑offset evidence to secure favorable reimbursement.
Operational levers — cost, sourcing and supply‑chain resilience
Device economics are sensitive to materials and assembly costs, with medical‑grade polymers forming a significant portion of the bill of materials. Current sector benchmarks for common housing resins point to bulk pricing in the low‑double digits per kilogram; design decisions that reduce polymer mass, enable modular assembly, or substitute higher‑cost components with qualified alternatives can yield meaningful margin upside at scale.
Actionable steps for 2026:
-
Lock strategic supply agreements for critical polymers and electronics subassemblies with indexation clauses to manage volatility.
-
Qualify multiple injection‑moulding partners across geographies to reduce single‑site risk.
-
Implement design‑for‑assembly and design‑for‑recycling principles early to lower unit costs and support ESG commitments.
M&A, partnerships and the build vs. buy decision
2024–2025 deal activity shows three pragmatic motifs: (1) pharma looking to de‑risk launch timelines by partnering with device specialists, (2) device vendors securing commercial supply contracts to guarantee scale economics, and (3) regional entrants addressing affordability in emerging markets. For 2026 strategy, PW Consulting recommends a decision framework built on three criteria: time‑to‑market tolerance, control over IP/data, and total economic return. For therapies where adherence data is a core value driver, acquisition or exclusive licensing of platform technology may be justified. For therapies requiring rapid launch with constrained internal device capability, non‑exclusive supply and co‑commercial partnerships will often be superior.
Signals from recent market moves
-
New product launches with enhanced connectivity (e.g., platforms enabling real‑time dose monitoring) indicate that clinical evidence packages will increasingly include digital adherence and PK/PD correlation data.
-
Regulatory clearances of variant device forms reduce clinical risk and shorten commercialization lead times for partnering therapeutics.
-
Commercial supply agreements between device vendors and major pharma demonstrate that contract terms around data ownership, service levels and revenue sharing are now central negotiation points.
How to use the full PW Consulting report
This press note highlights the strategic takeaways you need to act in 2026; the full PW Consulting study contains the granular tools that will convert these insights into executable plans. Subscribers gain access to:
-
Interactive financial models with scenario toggles for adoption speed, pricing, and reimbursement outcomes.
-
Negotiation playbooks and sample contract clauses for platform licensing and supply agreements.
-
Detailed segment breakdowns, region and therapy‑specific adoption curves and channel models — intentionally withheld here to maintain this preview’s trailer role and to drive acquisition of the full dataset.
Conclusion — the strategic mandate for 2026
Wearable injectors are no longer a speculative adjunct to biologic delivery; they are a strategic lever for therapeutic differentiation, patient adherence, and new reimbursement value pools. The market’s strong growth trajectory and recent vendor and regulatory activity create both opportunity and execution risk. PW Consulting’s Worldwide Wearable Injectors Market report supplies the quantitative foundation, operational checklists and contract‑level playbooks necessary to convert 2026 strategic decisions into sustainable commercial outcomes. For executives planning portfolio prioritization, partnership negotiations or M&A targeting, this study is intended to be the reference document for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com