

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Automotive Torsional Vibrational Damper Market to Grow at 3.5% CAGR to USD 3,362.02 Million by 2032 — Asia Pacific Commands USD 1,162 Million in 2025
By pmarketresearch, 2026-07-15
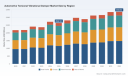
Worldwide Automotive Torsional Vibrational Damper Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market study on the Worldwide Automotive Torsional Vibrational Damper (TVD) market synthesizes a multi‑year empirical dataset, supplier intelligence, technology roadmaps and scenario analysis to create an operationally actionable playbook for executives planning through 2026 and beyond. Built on a 2025 base and projecting across 2026–2032, the report captures the maturation of a niche yet strategically vital component market that sits at the intersection of emissions regulation, powertrain electrification pathways and noise‑vibration‑harshness (NVH) engineering.
Worldwide Automotive Torsional Vibrational Damper Market
Market trajectory at a glance
The global TVD market has shown measurable recovery and structural growth since 2020, reflecting shifting demand patterns tied to engine downsizing, proliferation of belt‑start systems, and increasing hybridization. In absolute terms (USD, Million), the market rose from approximately 2,180.45 in 2020 and registered a higher baseline by 2025 (2,642.54), with short‑term year‑to‑year volatility evident during 2020–2025. Under PW Consulting’s central forecast, the market is expected to expand at a compound annual growth rate (CAGR) of approximately 3.5% through the 2026–2032 horizon, reaching an estimated 3,362.02 by 2032.
Worldwide Automotive Torsional Vibrational Damper Market
These headline numbers mask important structural transitions: product design is moving from elastomeric, purely mechanical solutions toward multi‑material and sensor‑enabled hybrid architectures; commercial vehicle and light vehicle demand drivers differ in tempo and technical specification; and aftermarket dynamics remain a crucial profit pool for several incumbent suppliers. The remainder of this briefing outlines what executives need to know in Q1–Q2 2026 to make high‑confidence decisions.
Worldwide Automotive Torsional Vibrational Damper Market
Why torsional dampers matter for 2026 corporate strategy
-
Regulatory push meets technical necessity: Stricter fleet CO2 and fuel economy standards in major markets are accelerating engine downsizing and turbocharging. Those powertrain choices produce higher torsional excitation, elevating the importance of precisely tuned TVDs to protect crankshafts, reduce NVH and preserve drivability.
-
Electrification adds complexity: The growing penetration of 48‑volt mild‑hybrid systems and belt‑starter‑generator architectures changes the technical spec for damper modules, encouraging integrated solutions that combine damping, pulley and starter functions while meeting packaging and thermal constraints.
-
Materials and smartness are adoption levers: Our industry survey and product scans show a rapid shift toward lightweight composites in new dampers and an early but accelerating adoption of sensor‑enabled hybrid dampers for torque management and predictive maintenance — technologies that will shape procurement and validation cycles in 2026.
What PW Consulting’s report delivers — an operator’s toolkit
-
Actionable market sizing and demand scenarios: Top‑line market trajectory by year (2020–2032) with base, downside and technology acceleration scenarios tied to 48‑V adoption and EV penetration assumptions.
-
Technology roadmaps and materials cost curves: Comparative performance maps for viscous, elastomeric and hybrid dampers; lifecycle cost profiles; and sensitivity to raw‑material and composite adoption rates.
-
Buy‑side decision playbook: OEM integration checklists, supplier selection scorecards, performance specification templates, and bench validation protocols tailored to passenger car, light commercial and heavy commercial applications.
-
Supply chain and manufacturing impact: Componentization and assembly options, tolerance and durability risk matrices, sourcing strategies for elastomers, viscous media and composite housings, and factory footprint implications for just‑in‑time programs.
-
Commercial benchmarking and M&A intelligence: Strategic profiles of incumbents and challengers, pricing archetypes by technology family, and prioritized M&A/partnership target lists based on capability gaps and geographic reach.
-
Regulatory and standards overlay: How near‑term regulatory milestones (CO2/CAFE) and mild‑hybrid penetration trajectories translate into part‑level requirements and timing for design freezes.
Competitive landscape — capability themes and selected player analysis
The TVD market remains populated by engineering‑intensive suppliers with deep OEM relationships. Rather than a winner‑takes‑all dynamic, the market rewards focused technical differentiation — material science, thermal management, hybridization and packaging integration. Below we summarize the capabilities and strategic posture of core competitors covered in the report.
-
Vibracoustic SE (Germany — https://vibracoustic.com): A leading specialist in pressed, vulcanized and fluid damper solutions for light vehicles. Vibracoustic emphasizes integrated damping modules that work well with decoupled pulleys and start‑stop systems — a valuable profile for OEMs pursuing packaging consolidation in downsized gasoline engines.
-
Vibratech TVD (United States — https://www.vibratechtvd.com): Known for pioneering viscous TVDs, Vibratech positions itself where high‑temperature durability and continuous high‑load performance are critical. Recent product documentation highlights dual‑viscous designs optimized for heat dissipation — a competitive edge in heavy‑duty and hybridized high‑load applications.
-
ZF Friedrichshafen AG (Germany — https://www.zf.com): ZF leverages dual mass flywheel and DynaDamp technology for commercial and hybrid powertrains, addressing high‑torque use cases with integrated decoupling architectures up to very high torque ratings. Their systems‑level capabilities make them a preferred partner where integration across driveline subsystems is required.
-
Continental AG (Germany — https://www.continental.com): With a broad offering spanning aftermarket and OEM lines, Continental’s strategy is modular integration. The company has recently rolled out combined damper/pulley/crank modules for 48‑V mild‑hybrid engines — an example of productization that shortens OEM development cycles.
-
Schaeffler AG (LuK/INA) (Germany — https://www.schaeffler.com): Schaeffler’s focus on crankshaft dampers, spoke dampers, and pulley decouplers positions it well for mixed portfolios where combustion and hybrid engines coexist. Their strength lies in NVH optimization and high‑volume manufacturing consistency.
-
Hasse & Wrede GmbH (Germany — https://www.hassewrede.com): A specialist in viscous or visco‑dampers with depth in passenger car and commercial vehicle applications. Hasse & Wrede competes on customization and thermal performance under sustained loads.
-
Gates Corporation (United States — https://www.gates.com): Gates offers system solutions combining drive belts and damper modules for passenger and light commercial vehicles. Their commercial play is oriented at integrated subsystem reliability and aftermarket compatibility.
Collectively, these players demonstrate three persistent strategic plays in 2026: (1) deeper functional integration (damper + pulley + starter), (2) hybridization (mech‑viscous + electronics) for predictive maintenance, and (3) material innovation to reduce mass and thermal sensitivity.
Recent industry moves — signals for near‑term strategy
-
Vibratech’s late‑2024 technical documentation emphasized dual viscous designs aimed at higher heat loads and durability — signposting product maturity that shortens validation cycles for fleet customers.
-
Continental’s mid‑2024 launch of an integrated module for 48‑V mild‑hybrids illustrates OEM demand for packaging consolidation and simplified supplier interfaces; similar modules are likely to displace multi‑supplier architectures in some vehicle programs.
Five strategic imperatives for 2026
-
Reprioritize integration capability: OEMs and Tier‑1s should move earlier to qualify integrated damper modules for 48‑V lines to avoid late engineering rework and supplier lock‑in.
-
Invest in materials and thermal R&D: Lightweight composites and improved viscous carrier materials materially affect NVH and durability — prioritize supplier partnerships that can demonstrate validated gains under thermal cycling.
-
Bias procurement toward flexible suppliers: Short‑run customization and multi‑variant production will be a source of competitive advantage as hybrid architectures proliferate.
-
Use sensorized dampers as an upsell and data source: Hybrid dampers with embedded sensing enable torque trending and predictive maintenance, opening new recurring revenue opportunities for suppliers and fleet telematics integration for OEMs.
-
Align product roadmaps with regulatory timelines: Map damper design freezes to regional CO2/CAFE milestones to ensure compliance without costly redesigns.
Methodology and forecast assumptions
The report’s baseline uses 2025 as the reference year and integrates historical datapoints from 2020–2025 to calibrate demand drivers. Forecasts for 2026–2032 are built on a bottom‑up approach that combines vehicle production projections, powertrain mix scenarios, technology adoption curves (including 48‑V penetration and hybrid damper adoption), and supplier capacity constraints. Sensitivity analysis explores outcomes around ±1.5 percentage points on the central CAGR, driven primarily by regional hybridization rates and material cost inflation. The headline projection — a 3.5% CAGR across the forecast window — represents the central case where 48‑V adoption and composite integration progress in line with current industry guidance.
Next steps — how to use PW Consulting’s intelligence in 2026
-
For OEM strategy teams: Use the report’s integration checklists and supplier scorecards to accelerate module qualification and lock down sourcing before program freeze.
-
For Tier‑1 suppliers: Leverage the cost curve and material matrices to prioritize investments in composite tooling and viscous media testing that will win design‑in contracts.
-
For investors and M&A teams: Employ the commercial benchmarking and target shortlists to identify bolt‑on acquisitions that provide either thermal management capability or software/data augmentation for sensorized dampers.
Conclusion
The Worldwide Automotive Torsional Vibrational Damper market is no longer a purely mechanical component market; it is evolving into a systems and data play that touches regulatory compliance, vehicle architecture and aftersales economics. PW Consulting’s report equips decision‑makers with the quantitative baseline, practical tools and supplier insights required to convert this evolution into commercial advantage through 2026 and across the 2026–2032 planning window.
To access the full dataset, detailed segmentation, supplier market shares, and interactive scenario dashboards, please consult the full PW Consulting report and accompanying executive tools available on our website. The public brief above is designed to convey the strategic contours while reserving the full granular intelligence for licensed report access.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Torsional Vibrational Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Customs Brokerage Services Market to Expand at 6.4% CAGR, Reaching USD 25,086.77 Million by 2032
By pmarketresearch, 2026-07-15
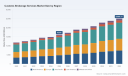
Worldwide Customs Brokerage Services Market — Strategic Imperatives for 2026 (PW Consulting Insight)
PW Consulting's new in-depth study of the Worldwide Customs Brokerage Services Market (base year 2025) delivers a practitioner-focused roadmap for commercial, operational and M&A decision‑making in 2026. The market has expanded meaningfully over the past half‑decade — rising from roughly USD 11.85 billion in 2020 to approximately USD 16.25 billion in 2025 — and our forecast calls for continued expansion at a compound annual growth rate of about 6.4% through 2032, when the market is expected to surpass USD 25 billion. This release summarises the strategic value of that research for executives and investment committees while intentionally leaving detailed segment tables and model outputs for subscribers and the report portal.
Worldwide Customs Brokerage Services Market
Why this market matters for 2026 planning
-
Trade complexity is the new baseline. Tariff regimes, origin rules, preferential programs and growing regulatory variation have made customs brokerage more than a transaction — it is a control point for landed cost, time-to-market and regulatory risk. Against that backdrop, sustained mid-single digit market expansion reflects firms’ willingness to invest in capabilities that reduce friction and preserve margins.
Worldwide Customs Brokerage Services Market -
Digitisation and compliance automation are accelerating ROI timeframes. Across our primary interviews and systems analysis, we find AI-enabled document verification, rules engines and automated filing workflows materially compress cycle times and error rates. Early adopters are already internalising efficiency gains into commercial offers and pricing models.
Worldwide Customs Brokerage Services Market -
Platform convergence is reshaping how brokerage is bought and embedded. Large logistics integrators and freight platforms are folding brokerage into end-to-end offerings while point‑solution vendors seek to attach customs functionality via APIs or acquisitions. Recent market activity confirms this trend: strategic buys and platform partnerships are becoming the fastest route to scale for software-first entrants.
-
Regulation and fee volatility are now planning variables. Government modernization programs and revised filing frameworks are changing operating processes for brokers and importers. Regulatory updates — including national system modernization efforts and new broker process rules — are increasing the operational premium on compliance capabilities and control frameworks.
What PW Consulting’s research offers — practical content for 2026 decisions
Our report was designed for operators and investors who need executable guidance rather than descriptive summaries. Key practitioner deliverables include:
-
A forward-looking demand model: scenario-based forecasts (base, downside, upside) that map trade-volume sensitivities, policy shocks and e‑commerce adoption curves to service demand and pricing pressure.
-
Vendor capability scorecards: a reproducible framework for assessing market participants on four dimensions — coverage, technology integration, compliance depth and commercial model — enabling rapid shortlisting under different strategic objectives (cost-out, quality-of-service, growth).
-
Tactical playbooks: step-by-step protocols for implementing AI-enabled compliance, migrating from paper to electronic proofs, and integrating customs workflows into ERP/OMS systems without disrupting operating cycles.
-
M&A and partnership heatmaps: prioritized target archetypes and partnership structures mapped to buyer profiles (global integrators, regional specialists, software platforms), plus valuation sensitivity models that account for synergies in clearance volumes, data capture and customer retention.
-
Regulatory tracker and impact assessments: continuous monitoring templates for government program changes and source documentation requirements, including practical checklists for customs broker permit management and audit readiness.
Competitive landscape — who matters and what their strategies imply
The brokerage market is composed of both global integrators and focused specialists. Large logistics and parcel integrators offer embedded brokerage as part of broader supply‑chain suites, using their global networks and digital platforms to win integrated flows. At the same time, dedicated brokerage players retain advantages on regulatory nuance, local filings and dispute resolution. Our analysis profiles leading firms across those archetypes and distils the strategic moves shaping competitive dynamics:
-
Integrated logistics leaders (examples profiled in the report) leverage scale to bundle clearance with transport and customs visibility. Integration provides cross-sell opportunities and a defensible route to manage customer stickiness, particularly for large shippers seeking a single vendor to manage border complexity.
-
Global forwarders and freight integrators maintain large land‑and‑sea networks and are increasingly adding brokerage to the bundled offering, using digital platforms to standardise data capture and reduce manual touchpoints.
-
Specialist brokers and regionally focused firms continue to win on granular compliance expertise and service for high-risk or high-complexity product flows. Their deep local knowledge remains critical for niche verticals or high-value product categories.
-
Software and platform entrants are pursuing acquisitions and API partnerships to embed brokerage into commerce stacks — a clear example of this strategic vector occurred when a cross‑border platform expanded into customs functionality through acquisition earlier in 2026, illustrating the strategic value of combining platform reach with regulatory capability.
Implications for corporate strategy and procurement
For business leaders making allocation choices in 2026, the report translates market patterns into decision criteria:
-
Make architecture choices explicit: decide whether customs capability should be a core, vertically integrated function or a sourced service. Our TCO model compares total cost and control trade-offs over a three‑ to five‑year horizon under realistic adoption and compliance scenarios.
-
Invest in compliance automation now: deploying AI‑assisted classification and automated documentation reduces variability and dispute costs. Expect payback through error reduction and lower detention-related charges — our implementation playbook outlines milestone KPIs and governance roles.
-
Hedge regulatory risk: maintain continuous regulatory monitoring and build rapid-response protocols for government system changes (e.g., new electronic filing capabilities and account ownership processes). The report provides an operational checklist for permit renewals, ACE/CAPE readiness and stakeholder communication templates.
-
Use M&A and partnerships to accelerate last‑mile capability: for firms seeking scale and instant regulatory competence, partnership with regional specialists or tuck‑ins of compliance software vendors provides faster market access than greenfield builds.
-
Price and service segmentation: re-evaluate commercial terms for border‑intensive flows. Our commercial playbook includes negotiation levers and modular service offering templates to protect margin while preserving customer experience.
Regulatory and operational watch‑items for 2026
-
System modernisation. Customs agencies across major trading jurisdictions continue to enhance automated entry and payment systems. Brokers and importers should prioritise readiness for evolving electronic filing capabilities and expanded refund scenarios under new platforms.
-
Permit and fee administration. Keep active permit-management rhythms and budget for administrative updates (including national permit user fees and associated filing timelines) as recurring P&L line items and compliance obligations.
-
Labour and compliance overheads. Expect ongoing pressure on operating budgets driven by compliance staffing and technology amortisation; our operating-cost benchmarks and staffing models help firms size required investments without eroding profitability.
-
Consolidation and platform plays. Watch for continued consolidation where platform owners seek to own more of the compliance stack — early strategic decisions about alliance models will determine scale-up speed and cost synergies.
Methodology, scope and how to use the full report
PW Consulting’s study combines granular customs filing analysis, proprietary demand models, a vendor diligence program, and more than 60 executive interviews across shippers, brokers, regulators and technology providers. The base year is 2025, the historical window covers 2020–2025, and the forecast window spans 2026–2032. Subscribers receive the full forecasting model, downloadable vendor scorecards, negotiation playbooks and implementation checklists.
Consistent with our “trailer” approach, this release highlights the strategic implications and the practical value of the research while reserving detailed segment tables, regional splits and contractor-level figures for the full report and interactive dashboards. That richer dataset is the operational asset finance teams, procurement and CIOs will use directly in budgeting, vendor selection and M&A diligence.
Next steps for executives
-
Schedule a custom briefing: PW Consulting offers executive workshops that map our models to your flows and quantify the benefits of build vs. buy scenarios for 2026.
-
Run a rapid readiness assessment: use our compliance maturity checklist to identify immediate gaps in systems, staffing and audit controls that could manifest as cost or timing risks at the border.
-
Identify priority targets for partnership or tuck‑in M&A: apply our vendor scorecard to create a short list of candidates aligned to your strategic objective.
Customs brokerage is no longer a back‑office function; it is a strategic lever for cost, speed and compliance. PW Consulting’s Worldwide Customs Brokerage Services Market report provides the models, tools and on-the-ground insight that leaders need to convert regulatory complexity into competitive advantage in 2026. Access to the full dataset, vendor scorecards and implementation playbooks is available through our report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Customs Brokerage Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts D&O Insurance Market to Expand at 7.64% CAGR Through 2032
By pmarketresearch, 2026-07-15
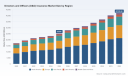
Directors and Officers (D&O) Insurance Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As boards, risk officers, insurers, and brokers enter 2026, the Directors and Officers (D&O) insurance landscape has moved from episodic volatility to a new, structurally nuanced phase. Our latest PW Consulting Directors and Officers Insurance Market report — with a 2025 base year and a 2026–2032 forecast horizon — synthesizes five years of market evolution (2020–2025) and delivers the decision-grade intelligence leaders need to set underwriting strategy, capital allocation, and governance priorities for the next strategic cycle.
Directors and Officers (D&O) Insurance Market
Why this report matters for 2026 decision-making
-
Market scale and trajectory. The global D&O market stood at USD 25,200 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 7.64% through the forecast window. By 2032, our baseline projection places the market in excess of USD 42 billion, underscoring continued commercial opportunity alongside rising exposure complexity.
Directors and Officers (D&O) Insurance Market -
Claims inflation and cost pressure. Legal-services inflation and growing claim severity are shifting loss-cost curves. Our analysis quantifies the downstream impact on defense erosion, retention economics, and insurer working layers — forces that will shape renewals, capacity deployment, and product design in 2026.
Directors and Officers (D&O) Insurance Market -
Emerging liabilities are reshaping underwriting. AI governance, ESG-related disclosure risks, cyber-linked director exposures, and geopolitical trade friction have transitioned from perimeter concerns to central underwriting criteria. Boards and insurers who align governance frameworks with updated coverage architecture will gain first-mover advantage.
-
Stabilizing but selective pricing environment. Market intelligence from multiple sources indicates premium stabilization in 2026 with selective upward pressure in higher-severity lines and sectors exposed to insolvency and securities litigation. That selective repricing creates both threat and opportunity across client segments.
Report at a glance — practical, actionable deliverables
PW Consulting’s market study is structured as a working playbook for commercial and strategic decisions in 2026. Key deliverables include:
-
Market sizing and trajectory modeling — multi-scenario forecasts calibrated to macro and micro drivers, enabling stress-testing of premium and loss scenarios under different economic and litigation environments.
-
Claims- and defense-cost heat maps — qualitative and quantitative drivers of severity by risk vector, with implications for attachment points, aggregate buying patterns, and policy wordings.
-
Underwriting playbooks — sector-specific risk checklists, enhanced submission templates, and recommended covenants for governance, cyber hygiene, and AI oversight.
-
Product and pricing architecture options — design templates for layered covers, bespoke Side A enhancements, and modular add-ons that respond to insolvency, cyber contagion, and regulatory inquiry risk.
-
Distribution and broker strategies — go-to-market recommendations for cross-sell, capacity allocation, and incentive alignment with placement partners.
-
Regulatory and litigation scenario toolbox — mapped pathways for regulatory shifts, securities-class action dynamics, and cross-border enforcement that could materially affect D&O exposures.
-
Insurer benchmarking and competitive scorecards — forward-looking capability assessments across underwriting, claims handling, and product innovation to inform partner selection and M&A diligence.
Competitive landscape — how incumbents are positioning for 2026
The market’s center of gravity remains with well-capitalized insurers that combine global placement capabilities with specialized product engineering. Our competitive analysis synthesizes public positioning, capability signals, and product emphasis across incumbents to reveal strategic vectors for 2026.
-
Chubb — Leverages multinational distribution and local policy footprints to serve complex, cross-border placements. Their focus on tailored Side A enhancements and governance-driven underwriting makes them a lead partner for multinational boards seeking continuity of coverage across jurisdictions.
-
AIG — Continues to emphasize comprehensive management-liability suites for public, private, and nonprofit clients, with product breadth calibrated to securities and regulatory claims. Their scale positions them to underwrite layered placements and participate in larger excess placements.
-
Travelers Insurance — Concentrates on disciplined underwriting and claims protection for middle-market clients, with product simplicity and distribution reach that resonate with sector-focused risk managers.
-
Liberty Mutual / Ironshore — Known for underwriting complex risks, Liberty’s specialty platforms are tilting toward bespoke solutions for emergent exposures, including insolvency and professional-liability cross-overs.
-
Allianz — Public thought leadership on geopolitics, insolvency trends, and cyber contagion has positioned Allianz as a go-to provider for global boards navigating macro risk amplification.
-
Zurich Insurance Group — Focuses on integrated solutions for multinational and mid-sized enterprises, emphasizing management and professional liability alignment coupled with risk mitigation advisory.
-
AXA XL — Offers targeted financial-lines innovations; their willingness to enhance coverage for emerging exposures (e.g., AI oversight clauses) is a differentiator in competitive placements.
-
Beazley — Strong in specialty and cyber-convergent risks, with product agility and claims advocacy that appeal to digitally exposed boards and smaller-cap public entities.
-
Hiscox — Targets small-to-mid-sized enterprises with streamlined offerings and sector-oriented distribution, capturing scale in a price-sensitive segment.
-
Berkshire Hathaway Specialty Insurance — Competes on balance-sheet strength and willingness to support high-limit, complex risk placements — an important capacity partner in layered towers.
Across the competitive set, the differentiators for 2026 will include: product modularity tied to governance controls; speed and transparency of claims response; redistribution of capacity across reinsurers; and data-driven underwriting for AI and cyber-related director exposures.
Industry dynamics and recent development signals
-
Rising insolvency pressure: Industry research signals a near-term uptick in global business insolvencies. This trend materially amplifies D&O exposure in sectors with capital-cycle stress (notably automotive, construction, and retail) and should inform sector-specific underwriting stress tests.
-
Securities litigation backdrop: Public filings and industry reports indicate a step-up in settlement sizes for securities class actions, a factor that sustains high attachment energy in public-company placements.
-
Legal cost inflation: Cumulative legal-services inflation has materially increased defense costs since 2020. That rise is eroding traditional working layers and pushing reinsurers and primary underwriters to reassess retention policy economics.
-
Emergent liability vectors: AI governance, ESG reporting, and geopolitical risk are now principal considerations when underwriting the fiduciary and oversight exposures of executives and boards.
-
Market sentiment: Multiple market commentators and rating agencies have signaled stabilization in premium trajectories for 2026 but with selective tightening where loss frequency or severity is increasing.
Strategic imperatives for boards, insurers, and brokers in 2026
-
Boards and senior management: Integrate insurance-aware governance. Enhance disclosure discipline, adopt board-level AI oversight frameworks, and coordinate with CFOs and risk officers to model D&O contingent liabilities under bankruptcy and securities-litigation scenarios.
-
Insurers and underwriters: Re-calibrate product architecture toward modular, governance-linked covers and introduce clearer triggers for cyber-related director exposures. Embed legal-cost inflation assumptions into loss-model scenarios and reassess working-layer economics.
-
Brokers and distribution partners: Develop solution bundles that pair preventive advisory (governance, cyber hygiene, AI policy) with placement strategies that reduce attach risk and lower total cost of risk for clients.
-
Reinsurers and capital providers: Prioritize capacity allocations to segments with predictable underwriting tail and develop products that flex capacity in response to litigation cycles and insolvency waves.
-
Investors and M&A teams: Include D&O exposure mapping in diligence playbooks, focusing on historical governance incidents, litigation pipelines, and cross-border enforcement risks that can materially affect post-closing liability profiles.
How PW Consulting translates analysis into advantage
Our D&O market study is intentionally structured as a decision instrument: not just descriptive market intelligence, but prescriptive playbooks and scenario toolkits that teams can operationalize during renewals, budgeting cycles, and strategic planning. Core capabilities we deploy for clients include bespoke scenario modeling, underwriting optimization workshops, claims-readiness diagnostics, and M&A D&O due-diligence packages.
In keeping with our "trailer" principle, this press summary surfaces the macro trajectory, competitive themes, and strategic imperatives — while preserving the detailed, segment-level data and dynamic matrices that make the full report uniquely actionable. If your strategic plan for 2026 depends on precise regional supply-demand balances, coverage-level elasticity, competitor share dynamics, or modeled loss-cost ladders, the full PW Consulting report provides that calibrated intelligence and downloadable analytical assets.
Next steps
-
Download or request the full Directors and Officers Insurance Market report to access the comprehensive data annex, segment-level forecasts, insurer scorecards, and implementation templates.
-
Contact PW Consulting for a tailored briefing: we offer executive summaries, board-ready slide decks, and scenario workshops that translate the report’s insights into executable 90–180 day plans.
-
Engage in a rapid diagnostic if you are preparing for a major renewal, capacity negotiation, or M&A transaction — our team will align the report’s findings to your specific exposures and strategic objectives.
The D&O market in 2026 presents a dual narrative: expanding commercial scale alongside intensifying exposure complexity. Boards and insurers who combine forward-looking governance with disciplined underwriting, targeted product innovation, and scenario-based capital planning will capture disproportionate value. PW Consulting’s report equips decision-makers with the framework and the data to act confidently — and to act early.
For detailed analysis of this topic, please visit the official page: Directors and Officers (D&O) Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cooling Apparel Market Set to Expand at 8.99% CAGR from 2026–2032, Fueling Global Opportunity
By pmarketresearch, 2026-07-15
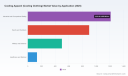
Worldwide Cooling Apparel Market: Strategic Outlook for Corporate Decision‑Makers — PW Consulting Report Preview
Executive summary
The global market for cooling apparel has entered a sustained growth phase as heat-stress risk moves from an episodic safety concern to a permanent planning variable for enterprises across apparel, industrial safety, sports performance and institutional procurement. PW Consulting’s new market study, with a 2025 base year and a 2026–2032 forecast horizon, tracks this transformation with firm-level implications for portfolio strategy, sourcing, and go‑to‑market execution. Our top‑line model quantifies market expansion from an estimated USD 1,840.6 million in 2020 to USD 2,745.5 million in 2025, and projects continued growth to about USD 5,018.9 million by 2032. The forecast is underpinned by a compound annual growth rate of 8.99% through the 2026–2032 period (values in USD Million).
Worldwide Cooling Apparel (Cooling Clothing) Market
Why 2026 is an inflection year for corporate strategy
- Demand environment: Increased frequency and intensity of heatwaves has dramatically increased end‑user demand for active cooling solutions. Independent consumer research shows double‑digit year‑over‑year spikes in expressed purchase intent for cooling apparel segments, pushing product adoption beyond traditional athlete and outdoor niches into occupational safety and healthcare settings.
- Regulatory shock: Recent chemical and materials rules in major markets have tightened the compliance bar for certain cooling agents and encapsulation approaches. Companies relying on microencapsulated phase‑change materials (PCMs) must now reconcile product performance goals with new nanoparticle‑safety provisions.
- Cost pressure and supply risk: Upstream inflation in synthetic fibers and labour cost increases across key producing geographies are compressing gross margins for vendors who cannot operationally hedge or redesign for lower material intensity.
- Consolidation opportunity: Market concentration remains low compared with adjacent apparel subsectors, creating windows for brand leaders and industrial suppliers to scale through targeted M&A, licensing and channel playbooks rather than broadscale price competition.
What this report delivers (practical, operational outputs)
- Proprietary market sizing and scenario models (base year 2025; forecast 2026–2032) delivered in Excel for boardroom scenario planning and rapid re‑run with client assumptions.
- Technology deep dives that map functional performance (evaporative, PCM, air‑cooled, liquid‑based systems) to use cases, lifecycle costs and regulatory risk matrices—highlighting where to invest R&D dollars versus buy/licence technology.
- Supply‑chain stress tests that quantify the P&L impact of raw material shocks, labour rate increases and logistics delays under three demand scenarios.
- Commercial playbooks: channel segmentation, pricing strategies, pilot templates for enterprise procurement (industrial safety, healthcare, defense) and GTM choreographies for DTC/wholesale hybrid models.
- Competitive benchmarking and M&A screen: strategic fit scores for potential targets across IP, manufacturing, regulatory compliance and customer channel access.
- Implementation toolkits: product roadmaps, KPIs, and 12–18 month pilot checklists to move from concept to volume commercialization quickly and with measured risk.
Key dynamics shaping strategic choices in 2026
- Material cost and sourcing: Polyester staple and other synthetic fiber inputs have experienced meaningful price moves that raise variable costs and change the math of low‑margin, high‑volume plays. Firms must redesign BOMs or negotiate long‑term purchase agreements to protect margin.
- Regulatory compliance as product architecture constraint: New restrictions on some cooling agents require manufacturers to revalidate formulations and potentially retool finishing lines—creating both near‑term CAPEX needs and medium‑term competitive differentiation for compliant solutions.
- Labor and geographic arbitrage: Wage inflation in certain Southeast Asian hubs is eroding the labor cost advantage those regions historically offered. Expect greater interest in nearshoring, automation investment, and conditional dual‑sourcing for critical SKUs.
- Consumerization of occupational needs: Features once reserved for athletes—lightweight moisture management, quick‑dry coatings, thermal regulation—are becoming procurement criteria for industrial and healthcare buyers, elevating product complexity requirements.
Competitive landscape — what the market structure means for 2026 tactics
The cooling apparel space is characterized by a mix of legacy sportswear majors, innovative specialty brands, and a long tail of regional manufacturers. Market concentration metrics indicate that the top three and top five players capture a modest share of overall revenue—evidence of a fragmented market with strong room for differentiated brand plays and technology licensing.
Worldwide Cooling Apparel (Cooling Clothing) Market
- Large sports apparel brands (e.g., Columbia Sportswear, Under Armour, Nike, Adidas): These incumbents bring scale in distribution, brand equity in performance apparel, and ongoing R&D investments. Their playbooks focus on integrating cooling features into broader seasonal collections and leveraging retail/athlete channels to accelerate trial.
- Specialist cooling brands (e.g., Mission Cooling, Coolibar, Icebreaker): Niche firms concentrate on category‑specific performance claims—instant wet‑activation cooling, UPF protection, natural fiber thermoregulation—and often lead in product ergonomics and targeted use cases.
- Workwear and defense suppliers (e.g., Kuchofuku and other industrial providers): These operators anchor demand in regulated procurement processes and can drive long‑lifecycle contracts that de‑risk revenue streams for innovators who can meet technical and compliance standards.
Recent industry moves—product launches, trade show rollouts and sustainable SKU extensions—illustrate two strategic paths: incremental feature integration by mainstream brands and focused innovation plus sustainability positioning by specialists. Both approaches are viable but require different investment, partnership and supply strategies.
Worldwide Cooling Apparel (Cooling Clothing) Market
Recommendations for corporate decision‑makers in 2026
- Prioritize regulatory‑compliant PCMs and coatings: If your product roadmap includes encapsulated cooling agents, fast‑track compliance validation and consider partnerships with compliant PCM manufacturers. The cost of delayed certification will exceed near‑term R&D expense over a multi‑year horizon.
- Adopt a bifurcated sourcing strategy: Secure core materials through long‑term contracts or vertical integration while maintaining flexible secondary suppliers for volatility management. Integrate early warning indicators (fiber spot price, labour rate indices) into procurement dashboards.
- Segment GTM by buyer economics: Treat industrial/occupational and institutional buyers differently from impulse retail buyers—longer sales cycles, higher technical documentation requirements and service level agreements call for dedicated commercial teams.
- Invest in rapid‑test pilot programs: Run 6–12 month pilots with enterprise customers that pair product pilots with thermal‑performance measurement and total‑cost‑of‑ownership analyses to accelerate procurement conversions.
- Evaluate M&A and licensing for fast capability scale: Consider acquiring niche IP or licensing cooling technologies that remove long lead times from your roadmap—especially if you lack in‑house materials science capability.
Supply‑chain resilience playbook
- Model margin sensitivity to input price shocks and labour wage inflation; prioritize SKUs where design changes can materially reduce fiber intensity without sacrificing performance.
- Leverage nearshore manufacturing for high‑complexity, low‑volume SKUs and low‑cost offshore capacity for commoditized items.
- Build traceability requirements into supplier contracts to manage regulatory audits and claims substantiation.
Use cases where 2026 investment yields the highest ROI
- Industrial safety apparel sold via long‑term enterprise contracts—lower churn and clear TCO comparisons.
- Performance‑driven sports lines that leverage athlete endorsements and measurable sport science claims to command premium pricing.
- Institutional procurement in healthcare and defense where durability, documented performance and compliance offer pricing power.
Methodology and what’s in the numbers
The analysis uses a 2025 base year with historical tracking from 2020–2025 and a forecast window from 2026–2032. All revenue figures are expressed in USD Million. Our baseline assumes continued acceleration of demand driven by climatic and occupational pressures, tempered by material cost escalation and regulatory constraints. The study also includes market concentration indicators that show a fragmented competitive field with significant niche opportunities.
Next steps — how to use this intelligence
This preview highlights the strategic levers companies must consider when setting 2026 priorities. PW Consulting’s full report provides the complete datasets, segment and regional models, downloadable scenario workbooks, and an implementation appendix including pilot templates and supplier scorecards. If your board or executive committee is preparing 2026 capital allocation, R&D sequencing or a buy‑side M&A agenda, the full intelligence package will accelerate decision cycles and reduce execution risk.
Accessing the full report
PW Consulting has prepared a client portal with the full Worldwide Cooling Apparel Market study, including the models and playbooks referenced above. For access and a tailored briefing on implications specific to your enterprise, contact your PW Consulting account lead or request a briefing through our corporate channels.
For detailed analysis of this topic, please visit the official page: Worldwide Cooling Apparel (Cooling Clothing) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pearls Market Valued at USD 4.15 Billion in 2025 — Poised for Continued Growth
By pmarketresearch, 2026-07-15
Pearls Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
Executive snapshot
PW Consulting’s Pearls Market report (base year 2025; forecast period 2026–2032) synthesizes market dynamics that should shape executive choices in 2026. The global pearls market has moved from roughly USD 3.3 billion in 2020 to about USD 4.15 billion by 2025, and our models show it expanding at a 5.25% CAGR through the 2026–2032 forecast window. By the early 2030s the market approaches the USD 6.0 billion threshold under our central case. All figures reported herein are in USD (Million).
Pearls Market
Why this matters for 2026 decision‑making
Pearls are re-emerging as a strategic category for luxury houses, specialty jewelers, and vertically integrated farm‑to‑retail players. The sustained mid‑single digit growth profile reflects a mix of premium channel stability, emerging middle‑market demand, and an inflection toward provenance‑driven purchasing. For 2026, leaders must balance three near‑term priorities: protecting margin under price and tariff pressure; capturing value from traceability and sustainability narratives; and realigning routes‑to‑market for an increasingly digital luxury consumer.
Pearls Market
What the report delivers (practical tools for strategists)
- Granular market sizing and trend narratives calibrated to 2020–2025 historicals and 2026–2032 forecasts, including alternative scenarios to stress test growth under trade and demand shocks.
- A decision‑grade competitive playbook mapping 7+ global players (profiles, headquarter locations, capabilities, selected strategic moves) and implications for partnerships, co‑branding, and M&A.
- Actionable go‑to‑market frameworks: channel prioritization guides for luxury vs. accessible segments, omnichannel merchandising blueprints, and digital conversion levers proven in high‑value jewelry categories.
- Supply‑chain resilience and sourcing protocols: risk heat maps, supplier due‑diligence checklists, and a playbook for integrating traceability technologies (blockchain, DNA tagging, independent third‑party verification).
- ESG and provenance toolkits: audit templates aligned with the expanded industry classification standards, guidance for claims substantiation, and templates for sustainability reporting tailored to pearl producers and retailers.
- Commercial levers: pricing architecture experiments, promotion and markdown frameworks, and elasticity diagnostics adapted for premium pearl assortments and broader jewelry sets.
- M&A and portfolio optimization templates: valuation cushions for farmed vs. manufactured inventory, integration checklists, and priority target profiles for roll‑up plays in a fragmented supplier base.
Market structure and competitive dynamics
The market remains fragmented at scale: the top three players account for under one‑fifth of global market value while the top five capture roughly a quarter. These concentration metrics highlight two strategic realities. First, there is room for value creation through consolidation and brand‑led aggregation. Second, market access and distribution are as critical as primary production — control over channels and storytelling amplifies value capture more than pure raw‑material ownership in many cases.
Pearls Market
Key incumbents are executing materially different strategies that offer templates and cautionary tales for 2026 planning:
- Mikimoto (Tokyo, Japan; https://www.mikimoto.com) remains the archetypal heritage brand. Its emphasis on premium Akoya innovation and luxury verticals underlines the durable power of provenance, craftsmanship narratives, and selective channel management.
- Tasaki (Kobe, Japan; https://www.tasaki-global.com) represents a vertically integrated luxury playbook combining farming control with design and retail. Tasaki’s model demonstrates how integration can protect margins and accelerate product innovation, but demands capital intensity and operational expertise.
- Paspaley (Darwin, Australia; https://www.paspaley.com) and Jewelmer (Makati, Philippines; https://us.jewelmer.com) illustrate the premium South Sea segment’s premiumization strategy: heavy emphasis on sustainability credentials, provenance storytelling, and direct relationships with luxury houses and collectors.
- Atlas Pearls (Subiaco, Australia; https://atlaspearls.com.au) exemplifies production‑to‑distribution scale in white and silver South Sea segments, highlighting the importance of diversified sourcing footprints to manage environmental and regulatory risk.
- Chow Tai Fook (Hong Kong; https://www.chowtaifook.com) demonstrates how mass luxury retailers can use broad Asian distribution reach to scale pearl jewelry assortments, making pearls a volume category as well as a prestige subcategory in specific markets.
- Zhejiang Grace Pearl Jewelry Co., Ltd (Zhuji, China) is indicative of the freshwater production base and manufacturing depth in China — an operational powerhouse that faces distinct regulatory and trade headwinds but offers cost and scale advantages for fast‑moving assortments.
Regulatory, industry and geopolitical drivers
The industry is experiencing a wave of institutionalization and standardization. In 2025 the international pearl community expanded its technical and classification resources, and the launch of an industry development body has begun to shift the operating baseline toward verifiable sustainability and standardized grading. These developments matter commercially: classification and traceability can justify price premiums in discerning luxury channels but will raise compliance and audit costs, particularly for smaller farms and manufacturers.
Geopolitical and trade tensions are non‑trivial. Trade discussions in 2025 referenced tariffs that, if enacted at the upper ranges discussed, could materially alter relative cost positions for key origin markets and compress margins across certain freshwater supply chains. Executives should therefore treat tariff volatility as a first‑order risk in sourcing, pricing, and inventory planning for 2026.
Strategic implications and recommended moves for 2026
- Prioritize provenance and traceability investments. Short‑term audit and certification costs will pay back through brand trust and higher realized prices in premium channels. Engage with industry bodies and the new development community to shape standards and gain early adopter advantage.
- Build flexible sourcing hubs. Hedge tariff and biological risks by diversifying suppliers across saltwater and freshwater origins and by developing contingency inventories that can be channeled to different markets.
- Design premium experiences around verified sustainability. Packaging, storytelling, and digital trace narratives that can be independently verified are becoming core purchase drivers for affluent consumers and institutional buyers alike.
- Explore roll‑up opportunities where scale brings immediate synergies — particularly in downstream manufacturing and retail distribution. The fragmented nature of the market creates attractive windows for consolidation with clear value‑creation roadmaps.
- Adapt pricing architectures to protect margin while stimulating volume: consider tiered provenance premiums, limited‑edition runs tied to documented sustainability events, and partnership lines with high‑profile designers to stretch brand equity.
- Invest in direct digital engagement. A differentiated online luxury experience (interactive provenance journeys, high‑fidelity product visualization, virtual try‑on) reduces dependence on physical retail and improves lifetime value economics.
What we intentionally withheld — and why
To preserve the report’s role as a decision‑grade subscription asset, we have deliberately presented the strategic narrative and tools while withholding the full segmented datapacks and proprietary regional/application breakdowns in this release. Readers seeking the granular revenue splits, fine‑grained regional movements, SKU‑level pricing matrices, and the full model workbook should consult the Pearls Market report page on the PW Consulting site. The withheld data are essential for transactional decisions (pricing, sourcing contracts, target valuation) and are provided to subscribers alongside scenario models and editable financial templates.
Conclusion — a 2026 lens
Pearls as a category presents a compelling strategic mix for 2026: resilient growth, meaningful premiumization potential, and an operating environment being reshaped by standards and trade risk. Executives who treat 2026 as a year to invest in provenance, build flexible supply chains, and selectively pursue scale will materially improve their odds of capturing disproportionate value as the market matures toward the early 2030s. PW Consulting’s Pearls Market report equips leadership teams with the frameworks, risk scenarios, and playbooks needed to translate these macro trends into executable plans.
Next steps
For the complete dataset, segmentation matrices, editable models, and subscriber‑only scenario planning tools, visit the Pearls Market report page on PW Consulting’s website or contact our market analytics desk. Our team can also arrange tailored briefings to translate the findings into a 90‑day strategic roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide WiFi-as-a-Service Market Poised for 19.52% CAGR, Surging to USD 29,106.4 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide WiFi as a Service Market: Strategic Briefing for 2026 Decision‑Makers
Introduction — why this matters in 2026
PW Consulting’s new market study on Worldwide WiFi as a Service (WaaS) provides a focused, decision‑grade view for executives planning network investments in 2026. The market reached USD 8,354.2 Million in our base year (2025) and is forecast to expand at a compound annual growth rate (CAGR) of 19.52% through our forecast window (2026–2032), reaching an estimated USD 29,106.4 Million by 2032. That trajectory reflects a fundamental shift in how organizations procure, operate and monetize wireless connectivity — from capital-intensive projects to subscription centric, cloud‑managed services that blur lines between networking, security and application platforms.
Worldwide WiFi as a Service Market
What this briefing delivers — strategic value for enterprise decision makers
This briefing highlights the elements of the full report that are most valuable to C‑suite, IT leadership, procurement and strategy teams preparing budgets and roadmaps for 2026:
Worldwide WiFi as a Service Market
- Actionable sizing and scenario analysis that quantifies growth under alternative technology, regulatory and economic assumptions — supporting capital allocation and sensitivity testing.
- Vendor positioning and competitive dynamics that identify category leaders, fast followers and challengers — enabling shortlist creation and negotiation tactics.
- Operational playbooks and procurement templates that reduce deployment risk and accelerate time‑to‑value for managed WiFi and cloud management subscriptions.
- Financial models (TCO/ROI) calibrated for subscription economics, allowing finance teams to compare opex vs capex outcomes across realistic lifecycle assumptions.
- Regulatory and data governance impact maps that translate regional compliance constraints into concrete contract language and architecture choices.
Report contents — practical, usable deliverables
The full PW Consulting report is organized to move teams from strategy to execution. Key deliverables include:
Worldwide WiFi as a Service Market
- Executive synthesis with three investment scenarios and decision triggers for 2026 procurement cycles.
- Methodology appendix documenting market and revenue assumptions, data sources and sensitivity bounds used to derive the USD 8.35B base and projected CAGR.
- Vendor scorecards and go‑to‑market (GTM) playbooks that rank suppliers across capability, scale, security posture, integration readiness and commercial flexibility.
- Deployment playbooks tailored to common verticals and multi‑site footprints — from single campus rollouts to national retail and hospitality estates.
- Contract and commercial negotiation templates, including recommended SLA constructs, data portability clauses and escalation pathways.
- ROI/TCO calculators for multi‑year budgeting under both subscription and hybrid procurement models.
- Risk register and regulatory compliance checklist (including data residency and portability implications) to support procurement and legal teams.
To preserve the report’s commercial value and follow the “trailer” principle, this release presents the strategic conclusions and tooling highlights while withholding the granular segment tables and vendor rank matrices — those are available in full on the source page.
Competitive landscape — how the vendor field shapes choices in 2026
The WaaS market is evolving into a multi‑tier competitive structure: cloud‑centric platform providers, integrated networking/security incumbents, specialist managed providers and regional telcos. Our market concentration analysis shows a moderately consolidated market dynamic: the top three vendors account for approximately 41.4% of measured revenues, while the top five account for roughly 57.8%. That mix creates opportunity for scale players to drive platform consolidation while leaving room for niche specialists that bundle analytics, marketing and vertical‑specific services.
- Cisco Meraki — Positioned as a cloud‑native leader with strong enterprise and SMB lines. Meraki’s subscription model and recent product refreshes emphasize simplified operations and rapid onboarding, making it a frequent default for organizations prioritizing operational simplicity and ecosystem integration.
- Hewlett Packard Enterprise (Aruba) — Competes on hybrid cloud architecture and enterprise features tied to edge compute. Recent partnerships that integrate Aruba Central with large cloud hyperscalers underline an enterprise strategy focused on extensible edge services and platform partnerships.
- Extreme Networks — Focuses on analytics and unified cloud management. Certification for the latest wireless standards and enhanced cloud tools position it as a strong choice for organizations that value advanced telemetry and lifecycle management.
- Ruckus Networks (CommScope) — Differentiates on high‑density environments and service models targeted at hospitality and education, with recent multi‑site deployments demonstrating operational scalability for large distributed estates.
- Fortinet — Integrates secure networking and SD‑WAN with wireless services, appealing to security‑first buyers who want a consolidated security stack across wired and wireless domains.
- Ubiquiti — Offers low‑friction cloud management and attractive economics for SMBs and distributed branches, competing strongly on simplicity and cost‑efficient subscription options.
- Rogers Communications — Represents telco‑led managed WiFi offerings in regional markets, bringing operator grade delivery and local support for enterprise customers.
- Purple — Specializes in guest analytics and marketing overlays, adding customer experience and monetization hooks that are especially attractive to retail and hospitality chains.
Recent vendor activity in 2025–2026 reinforces two themes: platform differentiation via standards support (WiFi 6E/7), and strategic integrations with cloud/edge ecosystems. Examples include product launches for WiFi 6E, hyperscaler partnerships for edge services, and certification for next‑generation WiFi standards — all of which materially impact procurement criteria for 2026.
Market dynamics and adoption drivers
Several interlocking dynamics accelerate WaaS adoption and shape vendor selection:
- Technology cadence: The opening of new unlicensed spectrum (notably in the 6 GHz band) and advancing standards (WiFi 6E/7) materially increase capacity and enable latency‑sensitive use cases. Early adopters stand to benefit from headroom in dense environments but must manage upgrade cycles.
- Commercial model shift: A broad move to opEx procurement is underway — our analysis shows subscription models account for a substantial portion of enterprise WiFi purchases, with a recent survey indicating approximately a 25% share attributable to subscription buys. This alters cashflow, vendor lock‑in risk and vendor evaluation criteria.
- Regulatory and data governance pressure: New rules on data portability and regional data residency (for instance, EU and Chinese market constraints) mandate architectural and contractual controls. Enterprises must embed data governance clauses and design for localized data handling where required.
- Unit economics and deployment cost structure: Typical managed subscription bundles embed hardware amortization and cloud management. Industry pricing studies indicate per‑unit subscription pricing and embedded access point economics that materially affect multi‑site cost forecasts — these should be modeled at the outset of any rollout.
- Value beyond connectivity: WiFi is being purchased as a platform for analytics, CX and operational automation. Suppliers that offer tight integration of guest analytics, location services and marketing automation create additional ROI pathways for retail and hospitality customers.
Five strategic moves for 2026
Enterprises preparing WiFi investments in 2026 should consider the following high‑probability plays:
- Adopt a platform evaluation rubric that weights security integration, standard support (6E/7 readiness), cloud management maturity and commercial flexibility equally — not just feature checklists.
- Pilot on spectrum‑rich sites to capture early performance gains of WiFi 6E/7, then use measured KPIs to negotiate volume economics for broader rollouts.
- Insert contractual clauses that enforce data portability and local processing where regulatory frameworks require; require vendors to demonstrate technical controls and auditability.
- Model total cost across subscription horizons (3–7 years) and stress test the model for changes in AP refresh cycles and rising spectrum/edge computing demands.
- Consider hybrid sourcing: combine hyperscaler‑integrated platforms for edge applications, specialist vendors for CX/analytics, and regional managed providers for localized operations and compliance.
How to access the full intelligence
This briefing outlines the strategic conclusions and recommended actions based on PW Consulting’s rigorous market work. The full report contains the granular segmentations, vendor scorecards, downloadable ROI models and the confidential appendices that procurement teams use to run RFPs and vendor due diligence exercises. We intentionally withhold the detailed numeric splits and full vendor scoring from this release to preserve actionable insight for subscribers.
Decision‑makers gearing up for procurement and deployment cycles in 2026 are encouraged to consult the full report to obtain the segment tables, interactive financial models and playbooks required to operationalize the strategies summarized here.
Closing — preparing for a subscription‑first network era
WiFi as a Service is no longer a niche managed‑service option; it is a foundational platform for digital experience, edge compute and secure connectivity. With an 19.52% CAGR and market expansion from the USD 8.35 billion base in 2025 to a projected USD 29.11 billion by 2032, the choices organizations make in 2026 will determine cost efficiency, security posture and application enablement over the next enterprise refresh cycle. PW Consulting’s full report equips leaders with the frameworks, comparative intelligence and executable playbooks to turn network connectivity into a strategic asset — not just infrastructure. For procurement teams ready to move, the detailed models and vendor assessments in the full report provide the immediate next steps.
For detailed analysis of this topic, please visit the official page: Worldwide WiFi as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pet Veterinary Diets Market to Surpass USD 20.22 Billion by 2032, Expanding at a 5.81% CAGR
By pmarketresearch, 2026-07-15
Worldwide Pet Veterinary Diets Market: Strategic Preview for 2026 Decision-Makers
PW Consulting — Executive Snapshot
As animal health continues to professionalize, veterinary diets have evolved from niche therapeutic lines into a strategic growth pillar for both specialty animal health firms and large consumer-oriented pet food manufacturers. Our new Worldwide Pet Veterinary Diets Market study (base year 2025) synthesizes historical performance, near-term inflection points and a forward-looking scenario set for 2026–2032. At the macro level the market is sizable and growing: the global market was above USD 13.6 billion in 2025 and, with a compound annual growth rate of approximately 5.8% through the forecast horizon, is projected to move materially higher by the early 2030s.
Worldwide Pet Veterinary Diets Market
Why this matters for 2026 corporate strategy
- Strategic priority: Veterinary diets are simultaneously a clinical offering and a commercial differentiator — they build practitioner trust, create recurring revenue through prescription follow-up, and act as a margin-enhancing portfolio lever.
- Timing: 2026 is a decision year for product pipelines and capacity investments initiated in 2023–2025. The gap between clinical evidence development and manufacturing scale-up means choices now determine market positioning for at least the next five years.
- Value trade-offs: Companies must balance investment in clinical trials and palatability with channel control (veterinarian-exclusive vs. retail) and compliance overhead. Those trade-offs are fundamentally commercial decisions with technical inputs; our report maps them end-to-end.
High-level market dynamics
Three dynamics will influence corporate outcomes in 2026 and beyond:
Worldwide Pet Veterinary Diets Market
- Demand sophistication: Veterinarians and informed pet owners increasingly expect therapeutic claims to be backed by clinical evidence, leading to longer product development cycles but stronger pricing power for validated solutions.
- Cost pressure and margin management: Raw material volatility — exemplified by commodity movements such as corn price cycles — places renewed emphasis on formulation flexibility and supplier diversification. Manufacturers that can de-risk ingredient sourcing without degrading palatability will preserve margins.
- Regulatory and trade complexity: Feed labeling and therapeutic claims are regulated differently across jurisdictions. Compliance frameworks require stronger documentation and, in many cases, vet-supervised distribution. Import controls and periodic alerts further complicate global supply chains.
Supply-side and operational considerations
- Manufacturing quality and certifications are table stakes. Recent site certifications demonstrate the premium placed on consistent, auditable production. For manufacturers, achieving and communicating recognized food-safety and quality accreditations will be essential to sustain vet channel trust.
- Channel economics favor vertically integrated models and strong veterinarian partnerships. The prescription-only distribution model protects therapeutic positioning but requires investment in professional education and compliance systems.
- Formulation innovation must reconcile clinical efficacy with palatability and cost. Hydration-focused wet formats, tailored renal and dermatology compositions, and nutraceutical integrations are areas of product-level differentiation.
Competitive landscape — what to watch
The market structure displays a high degree of concentration among established veterinary nutrition specialists and large integrated pet-care companies. Top competitors combine clinical investments, vet-channel distribution, and brand equity to maintain privileged access to prescribers. Our analysis identifies a pattern of strategy archetypes rather than a single dominant playbook:
Worldwide Pet Veterinary Diets Market
- Vet-specialist incumbents: Companies built on prescription-based therapeutics focus on deep clinical evidence, veterinarian relationships, and product portfolios targeted at specific pathologies. Their competitive moat is clinical trust and distribution control.
- Consumer-oriented multinationals: Large pet-food manufacturers leverage scale in manufacturing, global supply chains and brand recognition to expand into therapeutic lines while maintaining professional distribution through partnerships and dedicated business units.
- Mid-sized diversified animal health firms: These players often combine targeted nutrition offerings with adjacent pharmaceutical or diagnostics portfolios, enabling integrated clinical pathways for complex conditions.
Representative recent moves illustrate tactical priorities: selective product launches for sensitive-skin and renal formulas, portfolio sizing adjustments to improve palatability and hydration, and investments in manufacturing certifications. Collectively these actions signal three persistent bets—clinical differentiation, palatability engineering, and operational assurance—that will shape competitive positioning in 2026.
Regulatory and quality guardrails
- Labeling and therapeutic claims are tightly regulated; firms must align product positioning with jurisdictional requirements and maintain documentation supporting nutritional adequacy statements.
- Registration and establishment compliance pose non-trivial market-entry hurdles in many regions; regulatory strategy should be integrated into product development timelines to avoid launch delays.
- Trade and import controls mean source-country risk must be assessed as part of supplier selection and contingency planning.
What the PW Consulting report contains — practical outputs
This study is structured as a practitioner’s toolkit for commercial, R&D and corporate development teams. Key deliverables include:
- Top-line market sizing and demand scenarios (historical and forecast through 2032), with sensitivity runs for alternative macroeconomic and commodity assumptions.
- Go-to-market frameworks tailored to distribution models: vet-exclusive, hybrid (vet + retail), and direct-to-consumer approaches, with channel economics and margin overlays.
- Product innovation playbooks covering indication prioritization, palatability testing protocols, real-world evidence generation, and regulatory pathway mapping.
- Supply chain stress-testing tools, including an ingredient-cost sensitivity model and recommended hedging and supplier diversification strategies.
- Competitive benchmarking and M&A scoping tools: capability matrices, acquisition screening criteria, and integration checklists for nutrition-technology assets.
- Risk and compliance heatmaps covering labeling, import/export controls, and recall mitigation strategies.
- Commercialization checklists and 100-day launch plans for veterinary diet introductions, designed for launch-readiness and rapid practitioner adoption.
Actionable recommendations for 2026 planning
Below are priority actions we recommend executives adopt when defining 2026 strategies:
- Prioritize clinical evidence investment for at least one high-return indication. A single, well-evidenced product can unlock veterinarian prescribing and support premium pricing.
- Strengthen channel partnerships through co-developed education programs and outcomes tracking that demonstrate real-world benefit to practitioners.
- Implement a raw-material hedge and dual-sourcing strategy for key carbohydrate and protein inputs to limit exposure to commodity swings.
- Accelerate manufacturing quality programs and seek recognized third-party certifications to facilitate market access and reassure professional buyers.
- Design portfolio roadmaps that balance wet and dry formats with palatability as a non-negotiable metric for clinical acceptance.
- Explore bolt-on acquisitions that add clinical trial capability, veterinary CRM platforms, or regional distribution strength rather than purely revenue-focused targets.
- Operationalize regulatory readiness: pre-clear labeling claims, align documentation with jurisdictional standards, and build a rapid response protocol for import or recall events.
How to use this “trailer” and where to get the full intelligence
This article is deliberately designed as a strategic preview. It outlines the most material forces shaping the veterinary-diets market and provides tactical signposts for 2026 planning. The full PW Consulting report contains the granular datasets, regional and product segmentation, and scenario-modeled outcomes that corporate strategy, M&A teams, and commercial leaders require to execute decisively.
For access to the complete analysis — including segment-level revenue forecasts, regional splits, product-type dynamics, animal-type and indication breakdowns, and downloadable modeling tools — please consult the PW Consulting report landing page or contact your PW Consulting account lead. The full dataset will enable precise portfolio optimization, resource allocation and execution roadmaps that are calibrated to your organization’s risk appetite and growth objectives.
Closing perspective
Veterinary diets represent a unique intersection of science, commerce and regulation. For firms that align evidence-generation, manufacturing excellence and channel economics, the coming windows of opportunity in 2026 are substantial. For those that delay, cost volatility and regulatory complexity will raise the barrier to entry. PW Consulting’s report is built to convert market-level intelligence into boardroom-ready decisions — a necessary input for any growth plan in this maturing but still dynamic segment of the pet-care ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Veterinary Diets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Medications for Cutaneous Mastocytosis Market to Reach USD 170.6 Million by 2032, Expanding at a 5.15% CAGR
By pmarketresearch, 2026-07-15
Worldwide Medications for Cutaneous Mastocytosis Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study, Worldwide Medications for Cutaneous Mastocytosis Market (base year 2025; historical 2020–2025; forecast 2026–2032), provides an action-oriented roadmap for biopharma, generics manufacturers, payers and specialty service providers navigating a small but strategically important rare‑disease segment. The global market for medications addressing cutaneous mastocytosis has expanded from approximately USD 89.24 million in 2020 to USD 120.0 million in 2025 and, under our central scenario, is projected to reach roughly USD 170.6 million by 2032 — a compound annual growth rate (CAGR) of 5.15% across the 2026–2032 forecast window. These headline numbers understate the real strategic value: innovation in targeted therapies, evolving clinical guidance, and durable symptomatic-care demand together create multiple adjacent value pools for innovators and service partners.
Worldwide Medications for Cutaneous Mastocytosis Market
Why this briefing matters to 2026 strategic planning
- Clear growth trajectory. Modest but steady market expansion offers predictable tails for specialty franchises and attractive returns for focused portfolio investments, especially where clinical differentiation can be demonstrated.
- Regulatory inflection points. Recent targeted approvals and guideline updates are reshaping treatment pathways and payer expectations, altering the commercial calculus for new and repurposed assets.
- Consolidation and competition dynamics. Market concentration is moderate and leaving space for mid‑sized entrants to scale via differentiated clinical data, regional execution or manufacturing advantages.
- Operational fragilities. Supply‑chain constraints for specialized ingredients and active pharmaceutical ingredients (APIs) are a recurring risk that can determine time‑to‑market and margin profiles.
Key market dynamics shaping 2026 decisions
The landscape for medications addressing cutaneous mastocytosis is being redefined along three mutually reinforcing axes:
Worldwide Medications for Cutaneous Mastocytosis Market
- Therapeutic innovation and clinical evidence: The arrival of targeted therapies with demonstrated effects on cutaneous involvement has elevated the clinical conversation beyond symptomatic control. That shift is driving demand for real‑world evidence (RWE) programs, biomarker‑linked study designs and differentiated label claims that extend beyond traditional mediator‑release symptom management.
- Guideline and guideline‑adjacent momentum: Updated national and specialty guidelines — including recent expert consensus publications — are clarifying management pathways for non‑advanced and indolent disease forms, creating windows for formulary placement and standardized care bundles across outpatient specialty settings.
- Commercial and reimbursement mechanics: Symptom‑directed generics and established symptomatic therapies have entrenched reimbursement routes in major markets; however, payers are increasingly seeking outcomes‑linked justifications for higher‑cost targeted agents. Manufacturers must marry clinical value dossiers with pragmatic contracting strategies.
Competitive landscape — players to monitor
Our competitive analysis profiles innovators, multispecialty oncology players, and generics suppliers that together shape clinical access and care economics.
Worldwide Medications for Cutaneous Mastocytosis Market
- Blueprint Medicines (now part of Sanofi) — With a marketed KIT D816V‑selective therapy that has shown benefit for systemic disease and cutaneous manifestations, the combined entity brings development expertise and global commercialization reach. Strategic priorities include expanding label claims, generating RWE on cutaneous endpoints and leveraging global Sanofi commercial channels for specialty distribution and payer contracting.
- Novartis — A multikinase agent with indications for advanced systemic presentations remains an important therapeutic reference. Novartis’s portfolio and experience in oncology and rare diseases enable bundled approaches to physician education and durable managed‑care engagement, particularly for severe cases where multidisciplinary care is required.
- Viatris — As a supplier of generic mast cell stabilizers, Viatris plays a critical role in the symptomatic care backbone. Generics players are pivotal to ensuring treatment affordability and can act as acquisition or partnership targets for companies seeking to round out a full‑pathway offering.
- Teva — A major supplier of generic antihistamines and symptomatic agents, Teva’s broad supply and manufacturing footprint is a competitive advantage in securing stable access for patients and payers. Their role in volume markets can also influence pricing benchmarks and tender outcomes.
Recent regulatory, clinical and guideline signals
- Targeted therapy approvals in recent years have legitimized disease‑modifying approaches and elevated the importance of cutaneous endpoints in clinical and payer discussions.
- Presentation and expert discussions through 2025–2026 have emphasized the complementary roles of systemic agents and optimized symptomatic regimens for cutaneous disease management.
- National guideline releases have clarified pathways for non‑advanced disease and strengthened the case for standardized approaches in specialty clinics and ambulatory care settings.
Operational and market risks to factor into 2026 plans
Decision‑makers should incorporate the following risk vectors into near‑term planning:
- Supply‑chain and API constraints: Specialized raw materials pose intermittent availability issues; contingency sourcing and dual‑sourcing strategies are essential, particularly for small‑volume niche products.
- Payer scrutiny on value: High‑cost targeted agents face evolving HTA and payer assessment criteria; manufacturers must invest in robust health‑economic models and outcomes measurement plans prelaunch.
- Clinical evidence gaps: Cutaneous outcomes are not uniformly captured in legacy datasets. Companies that proactively design registries and pragmatic trials to capture skin‑specific endpoints gain a sizable competitive edge.
- Commercial footprint and channel complexity: Specialty clinics, hospital systems and homecare modalities each require tailored go‑to‑market approaches; misalignment across channels can erode uptake and create access bottlenecks.
What PW Consulting’s report delivers (practical, decision‑ready content)
Our report is deliberately structured to be immediately executable for 2026 strategy cycles. Key deliverables include:
- A granular, auditable market model (historical 2020–2025; forecast 2026–2032) with scenario toggles and sensitivity analysis supporting alternate price, uptake and access assumptions.
- Segmented market constructs (by therapeutic class, channel and geography) with interactive dashboards — the public brief hides granular cells to preserve exclusivity; full datasets are included in the licensed deliverable.
- Competitive dossiers for the leading innovators and generics suppliers, including SWOT profiles, product life‑cycle timelines, and likely strategic moves through 2028.
- Regulatory and reimbursement playbooks mapped to major markets, including prelaunch evidence plans, HTA submission checklists and contracting levers for outcomes‑based agreements.
- Supply‑chain risk assessment and mitigation frameworks with practical sourcing maps and contingency playbooks tailored to low‑volume, high‑specialty APIs.
- A commercial launch and lifecycle toolkit: pricing guidance, clinical education priorities, channel segmentation strategies and digital patient‑support program templates.
- An M&A and partnership heatmap highlighting likely targets, valuation benchmarks and integration considerations for bolt‑on acquisitions or strategic alliances.
How to use these insights to set 2026 priorities
Below are the near‑term actions we recommend for different stakeholders based on the market dynamics and modeled scenarios:
- For innovators and biotech: Prioritize generation of cutaneous‑specific efficacy and QoL data early in development; develop HTA‑grade health economic models; plan managed‑entry agreements in parallel with pivotal trials.
- For established pharma: Leverage integrated commercialization channels to bundle targeted therapies with patient support services and diagnostics; evaluate licensing or M&A to secure symptomatic care portfolios that provide comprehensive pathway coverage.
- For generics and specialty manufacturers: Invest in supply‑chain resilience and ensure capacity for stable supply; explore value‑added services to differentiate commoditized product lines (e.g., adherence support, specialty packaging).
- For payers and health systems: Consider outcome‑based contracting pilots where targeted therapies are used for clearly defined subpopulations; invest in registries that capture skin‑specific outcomes to inform coverage policy.
- For investors and advisors: Target opportunities that combine clinical differentiation with clear commercial pathways — companies that can de‑risk supply and demonstrate payer‑relevant outcomes will command premium valuations.
Why PW Consulting’s intelligence is strategic for 2026
Unlike descriptive market snapshots, our study embeds the tactical elements that convert insight to action: auditable forecasting mechanics, payer playbooks tied to clinical evidence thresholds, and commercially pragmatic mitigations for supply and channel risk. The market’s steady growth profile creates predictable revenue trajectories, but value capture will be determined by evidence strategy, manufacturing foresight and early payer engagement — not just product efficacy.
Next steps — obtain the full intelligence
This press brief intentionally surfaces the strategic contours and high‑impact recommendations while preserving the granular segmentation and proprietary datasets that underpin our forecasts. For access to the full report — including the interactive model, detailed segmentation tables, competitor scorecards and downloadable decision tools — visit PW Consulting’s official market research page or contact our advisory team to arrange a tailored briefing and dataset license. Early licensees will receive priority access to our custom scenario support for 2026 tactical planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Medications for Cutaneous Mastocytosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com