

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
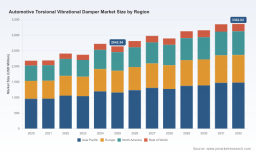
PW Consulting: Global Automotive Torsional Vibrational Damper Market to Grow at 3.5% CAGR to USD 3,362.02 Million by 2032 — Asia Pacific Commands USD 1,162 Million in 2025

Worldwide Automotive Torsional Vibrational Damper Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market study on the Worldwide Automotive Torsional Vibrational Damper (TVD) market synthesizes a multi‑year empirical dataset, supplier intelligence, technology roadmaps and scenario analysis to create an operationally actionable playbook for executives planning through 2026 and beyond. Built on a 2025 base and projecting across 2026–2032, the report captures the maturation of a niche yet strategically vital component market that sits at the intersection of emissions regulation, powertrain electrification pathways and noise‑vibration‑harshness (NVH) engineering.
Worldwide Automotive Torsional Vibrational Damper Market
Market trajectory at a glance
The global TVD market has shown measurable recovery and structural growth since 2020, reflecting shifting demand patterns tied to engine downsizing, proliferation of belt‑start systems, and increasing hybridization. In absolute terms (USD, Million), the market rose from approximately 2,180.45 in 2020 and registered a higher baseline by 2025 (2,642.54), with short‑term year‑to‑year volatility evident during 2020–2025. Under PW Consulting’s central forecast, the market is expected to expand at a compound annual growth rate (CAGR) of approximately 3.5% through the 2026–2032 horizon, reaching an estimated 3,362.02 by 2032.
Worldwide Automotive Torsional Vibrational Damper Market
These headline numbers mask important structural transitions: product design is moving from elastomeric, purely mechanical solutions toward multi‑material and sensor‑enabled hybrid architectures; commercial vehicle and light vehicle demand drivers differ in tempo and technical specification; and aftermarket dynamics remain a crucial profit pool for several incumbent suppliers. The remainder of this briefing outlines what executives need to know in Q1–Q2 2026 to make high‑confidence decisions.
Worldwide Automotive Torsional Vibrational Damper Market
Why torsional dampers matter for 2026 corporate strategy
-
Regulatory push meets technical necessity: Stricter fleet CO2 and fuel economy standards in major markets are accelerating engine downsizing and turbocharging. Those powertrain choices produce higher torsional excitation, elevating the importance of precisely tuned TVDs to protect crankshafts, reduce NVH and preserve drivability.
-
Electrification adds complexity: The growing penetration of 48‑volt mild‑hybrid systems and belt‑starter‑generator architectures changes the technical spec for damper modules, encouraging integrated solutions that combine damping, pulley and starter functions while meeting packaging and thermal constraints.
-
Materials and smartness are adoption levers: Our industry survey and product scans show a rapid shift toward lightweight composites in new dampers and an early but accelerating adoption of sensor‑enabled hybrid dampers for torque management and predictive maintenance — technologies that will shape procurement and validation cycles in 2026.
What PW Consulting’s report delivers — an operator’s toolkit
-
Actionable market sizing and demand scenarios: Top‑line market trajectory by year (2020–2032) with base, downside and technology acceleration scenarios tied to 48‑V adoption and EV penetration assumptions.
-
Technology roadmaps and materials cost curves: Comparative performance maps for viscous, elastomeric and hybrid dampers; lifecycle cost profiles; and sensitivity to raw‑material and composite adoption rates.
-
Buy‑side decision playbook: OEM integration checklists, supplier selection scorecards, performance specification templates, and bench validation protocols tailored to passenger car, light commercial and heavy commercial applications.
-
Supply chain and manufacturing impact: Componentization and assembly options, tolerance and durability risk matrices, sourcing strategies for elastomers, viscous media and composite housings, and factory footprint implications for just‑in‑time programs.
-
Commercial benchmarking and M&A intelligence: Strategic profiles of incumbents and challengers, pricing archetypes by technology family, and prioritized M&A/partnership target lists based on capability gaps and geographic reach.
-
Regulatory and standards overlay: How near‑term regulatory milestones (CO2/CAFE) and mild‑hybrid penetration trajectories translate into part‑level requirements and timing for design freezes.
Competitive landscape — capability themes and selected player analysis
The TVD market remains populated by engineering‑intensive suppliers with deep OEM relationships. Rather than a winner‑takes‑all dynamic, the market rewards focused technical differentiation — material science, thermal management, hybridization and packaging integration. Below we summarize the capabilities and strategic posture of core competitors covered in the report.
-
Vibracoustic SE (Germany — https://vibracoustic.com): A leading specialist in pressed, vulcanized and fluid damper solutions for light vehicles. Vibracoustic emphasizes integrated damping modules that work well with decoupled pulleys and start‑stop systems — a valuable profile for OEMs pursuing packaging consolidation in downsized gasoline engines.
-
Vibratech TVD (United States — https://www.vibratechtvd.com): Known for pioneering viscous TVDs, Vibratech positions itself where high‑temperature durability and continuous high‑load performance are critical. Recent product documentation highlights dual‑viscous designs optimized for heat dissipation — a competitive edge in heavy‑duty and hybridized high‑load applications.
-
ZF Friedrichshafen AG (Germany — https://www.zf.com): ZF leverages dual mass flywheel and DynaDamp technology for commercial and hybrid powertrains, addressing high‑torque use cases with integrated decoupling architectures up to very high torque ratings. Their systems‑level capabilities make them a preferred partner where integration across driveline subsystems is required.
-
Continental AG (Germany — https://www.continental.com): With a broad offering spanning aftermarket and OEM lines, Continental’s strategy is modular integration. The company has recently rolled out combined damper/pulley/crank modules for 48‑V mild‑hybrid engines — an example of productization that shortens OEM development cycles.
-
Schaeffler AG (LuK/INA) (Germany — https://www.schaeffler.com): Schaeffler’s focus on crankshaft dampers, spoke dampers, and pulley decouplers positions it well for mixed portfolios where combustion and hybrid engines coexist. Their strength lies in NVH optimization and high‑volume manufacturing consistency.
-
Hasse & Wrede GmbH (Germany — https://www.hassewrede.com): A specialist in viscous or visco‑dampers with depth in passenger car and commercial vehicle applications. Hasse & Wrede competes on customization and thermal performance under sustained loads.
-
Gates Corporation (United States — https://www.gates.com): Gates offers system solutions combining drive belts and damper modules for passenger and light commercial vehicles. Their commercial play is oriented at integrated subsystem reliability and aftermarket compatibility.
Collectively, these players demonstrate three persistent strategic plays in 2026: (1) deeper functional integration (damper + pulley + starter), (2) hybridization (mech‑viscous + electronics) for predictive maintenance, and (3) material innovation to reduce mass and thermal sensitivity.
Recent industry moves — signals for near‑term strategy
-
Vibratech’s late‑2024 technical documentation emphasized dual viscous designs aimed at higher heat loads and durability — signposting product maturity that shortens validation cycles for fleet customers.
-
Continental’s mid‑2024 launch of an integrated module for 48‑V mild‑hybrids illustrates OEM demand for packaging consolidation and simplified supplier interfaces; similar modules are likely to displace multi‑supplier architectures in some vehicle programs.
Five strategic imperatives for 2026
-
Reprioritize integration capability: OEMs and Tier‑1s should move earlier to qualify integrated damper modules for 48‑V lines to avoid late engineering rework and supplier lock‑in.
-
Invest in materials and thermal R&D: Lightweight composites and improved viscous carrier materials materially affect NVH and durability — prioritize supplier partnerships that can demonstrate validated gains under thermal cycling.
-
Bias procurement toward flexible suppliers: Short‑run customization and multi‑variant production will be a source of competitive advantage as hybrid architectures proliferate.
-
Use sensorized dampers as an upsell and data source: Hybrid dampers with embedded sensing enable torque trending and predictive maintenance, opening new recurring revenue opportunities for suppliers and fleet telematics integration for OEMs.
-
Align product roadmaps with regulatory timelines: Map damper design freezes to regional CO2/CAFE milestones to ensure compliance without costly redesigns.
Methodology and forecast assumptions
The report’s baseline uses 2025 as the reference year and integrates historical datapoints from 2020–2025 to calibrate demand drivers. Forecasts for 2026–2032 are built on a bottom‑up approach that combines vehicle production projections, powertrain mix scenarios, technology adoption curves (including 48‑V penetration and hybrid damper adoption), and supplier capacity constraints. Sensitivity analysis explores outcomes around ±1.5 percentage points on the central CAGR, driven primarily by regional hybridization rates and material cost inflation. The headline projection — a 3.5% CAGR across the forecast window — represents the central case where 48‑V adoption and composite integration progress in line with current industry guidance.
Next steps — how to use PW Consulting’s intelligence in 2026
-
For OEM strategy teams: Use the report’s integration checklists and supplier scorecards to accelerate module qualification and lock down sourcing before program freeze.
-
For Tier‑1 suppliers: Leverage the cost curve and material matrices to prioritize investments in composite tooling and viscous media testing that will win design‑in contracts.
-
For investors and M&A teams: Employ the commercial benchmarking and target shortlists to identify bolt‑on acquisitions that provide either thermal management capability or software/data augmentation for sensorized dampers.
Conclusion
The Worldwide Automotive Torsional Vibrational Damper market is no longer a purely mechanical component market; it is evolving into a systems and data play that touches regulatory compliance, vehicle architecture and aftersales economics. PW Consulting’s report equips decision‑makers with the quantitative baseline, practical tools and supplier insights required to convert this evolution into commercial advantage through 2026 and across the 2026–2032 planning window.
To access the full dataset, detailed segmentation, supplier market shares, and interactive scenario dashboards, please consult the full PW Consulting report and accompanying executive tools available on our website. The public brief above is designed to convey the strategic contours while reserving the full granular intelligence for licensed report access.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Torsional Vibrational Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com