

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medications for Cutaneous Mastocytosis Market to Reach USD 170.6 Million by 2032, Expanding at a 5.15% CAGR

Worldwide Medications for Cutaneous Mastocytosis Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study, Worldwide Medications for Cutaneous Mastocytosis Market (base year 2025; historical 2020–2025; forecast 2026–2032), provides an action-oriented roadmap for biopharma, generics manufacturers, payers and specialty service providers navigating a small but strategically important rare‑disease segment. The global market for medications addressing cutaneous mastocytosis has expanded from approximately USD 89.24 million in 2020 to USD 120.0 million in 2025 and, under our central scenario, is projected to reach roughly USD 170.6 million by 2032 — a compound annual growth rate (CAGR) of 5.15% across the 2026–2032 forecast window. These headline numbers understate the real strategic value: innovation in targeted therapies, evolving clinical guidance, and durable symptomatic-care demand together create multiple adjacent value pools for innovators and service partners.
Worldwide Medications for Cutaneous Mastocytosis Market
Why this briefing matters to 2026 strategic planning
- Clear growth trajectory. Modest but steady market expansion offers predictable tails for specialty franchises and attractive returns for focused portfolio investments, especially where clinical differentiation can be demonstrated.
- Regulatory inflection points. Recent targeted approvals and guideline updates are reshaping treatment pathways and payer expectations, altering the commercial calculus for new and repurposed assets.
- Consolidation and competition dynamics. Market concentration is moderate and leaving space for mid‑sized entrants to scale via differentiated clinical data, regional execution or manufacturing advantages.
- Operational fragilities. Supply‑chain constraints for specialized ingredients and active pharmaceutical ingredients (APIs) are a recurring risk that can determine time‑to‑market and margin profiles.
Key market dynamics shaping 2026 decisions
The landscape for medications addressing cutaneous mastocytosis is being redefined along three mutually reinforcing axes:
Worldwide Medications for Cutaneous Mastocytosis Market
- Therapeutic innovation and clinical evidence: The arrival of targeted therapies with demonstrated effects on cutaneous involvement has elevated the clinical conversation beyond symptomatic control. That shift is driving demand for real‑world evidence (RWE) programs, biomarker‑linked study designs and differentiated label claims that extend beyond traditional mediator‑release symptom management.
- Guideline and guideline‑adjacent momentum: Updated national and specialty guidelines — including recent expert consensus publications — are clarifying management pathways for non‑advanced and indolent disease forms, creating windows for formulary placement and standardized care bundles across outpatient specialty settings.
- Commercial and reimbursement mechanics: Symptom‑directed generics and established symptomatic therapies have entrenched reimbursement routes in major markets; however, payers are increasingly seeking outcomes‑linked justifications for higher‑cost targeted agents. Manufacturers must marry clinical value dossiers with pragmatic contracting strategies.
Competitive landscape — players to monitor
Our competitive analysis profiles innovators, multispecialty oncology players, and generics suppliers that together shape clinical access and care economics.
Worldwide Medications for Cutaneous Mastocytosis Market
- Blueprint Medicines (now part of Sanofi) — With a marketed KIT D816V‑selective therapy that has shown benefit for systemic disease and cutaneous manifestations, the combined entity brings development expertise and global commercialization reach. Strategic priorities include expanding label claims, generating RWE on cutaneous endpoints and leveraging global Sanofi commercial channels for specialty distribution and payer contracting.
- Novartis — A multikinase agent with indications for advanced systemic presentations remains an important therapeutic reference. Novartis’s portfolio and experience in oncology and rare diseases enable bundled approaches to physician education and durable managed‑care engagement, particularly for severe cases where multidisciplinary care is required.
- Viatris — As a supplier of generic mast cell stabilizers, Viatris plays a critical role in the symptomatic care backbone. Generics players are pivotal to ensuring treatment affordability and can act as acquisition or partnership targets for companies seeking to round out a full‑pathway offering.
- Teva — A major supplier of generic antihistamines and symptomatic agents, Teva’s broad supply and manufacturing footprint is a competitive advantage in securing stable access for patients and payers. Their role in volume markets can also influence pricing benchmarks and tender outcomes.
Recent regulatory, clinical and guideline signals
- Targeted therapy approvals in recent years have legitimized disease‑modifying approaches and elevated the importance of cutaneous endpoints in clinical and payer discussions.
- Presentation and expert discussions through 2025–2026 have emphasized the complementary roles of systemic agents and optimized symptomatic regimens for cutaneous disease management.
- National guideline releases have clarified pathways for non‑advanced disease and strengthened the case for standardized approaches in specialty clinics and ambulatory care settings.
Operational and market risks to factor into 2026 plans
Decision‑makers should incorporate the following risk vectors into near‑term planning:
- Supply‑chain and API constraints: Specialized raw materials pose intermittent availability issues; contingency sourcing and dual‑sourcing strategies are essential, particularly for small‑volume niche products.
- Payer scrutiny on value: High‑cost targeted agents face evolving HTA and payer assessment criteria; manufacturers must invest in robust health‑economic models and outcomes measurement plans prelaunch.
- Clinical evidence gaps: Cutaneous outcomes are not uniformly captured in legacy datasets. Companies that proactively design registries and pragmatic trials to capture skin‑specific endpoints gain a sizable competitive edge.
- Commercial footprint and channel complexity: Specialty clinics, hospital systems and homecare modalities each require tailored go‑to‑market approaches; misalignment across channels can erode uptake and create access bottlenecks.
What PW Consulting’s report delivers (practical, decision‑ready content)
Our report is deliberately structured to be immediately executable for 2026 strategy cycles. Key deliverables include:
- A granular, auditable market model (historical 2020–2025; forecast 2026–2032) with scenario toggles and sensitivity analysis supporting alternate price, uptake and access assumptions.
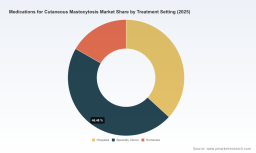
- Segmented market constructs (by therapeutic class, channel and geography) with interactive dashboards — the public brief hides granular cells to preserve exclusivity; full datasets are included in the licensed deliverable.
- Competitive dossiers for the leading innovators and generics suppliers, including SWOT profiles, product life‑cycle timelines, and likely strategic moves through 2028.
- Regulatory and reimbursement playbooks mapped to major markets, including prelaunch evidence plans, HTA submission checklists and contracting levers for outcomes‑based agreements.
- Supply‑chain risk assessment and mitigation frameworks with practical sourcing maps and contingency playbooks tailored to low‑volume, high‑specialty APIs.
- A commercial launch and lifecycle toolkit: pricing guidance, clinical education priorities, channel segmentation strategies and digital patient‑support program templates.
- An M&A and partnership heatmap highlighting likely targets, valuation benchmarks and integration considerations for bolt‑on acquisitions or strategic alliances.
How to use these insights to set 2026 priorities
Below are the near‑term actions we recommend for different stakeholders based on the market dynamics and modeled scenarios:
- For innovators and biotech: Prioritize generation of cutaneous‑specific efficacy and QoL data early in development; develop HTA‑grade health economic models; plan managed‑entry agreements in parallel with pivotal trials.
- For established pharma: Leverage integrated commercialization channels to bundle targeted therapies with patient support services and diagnostics; evaluate licensing or M&A to secure symptomatic care portfolios that provide comprehensive pathway coverage.
- For generics and specialty manufacturers: Invest in supply‑chain resilience and ensure capacity for stable supply; explore value‑added services to differentiate commoditized product lines (e.g., adherence support, specialty packaging).
- For payers and health systems: Consider outcome‑based contracting pilots where targeted therapies are used for clearly defined subpopulations; invest in registries that capture skin‑specific outcomes to inform coverage policy.
- For investors and advisors: Target opportunities that combine clinical differentiation with clear commercial pathways — companies that can de‑risk supply and demonstrate payer‑relevant outcomes will command premium valuations.
Why PW Consulting’s intelligence is strategic for 2026
Unlike descriptive market snapshots, our study embeds the tactical elements that convert insight to action: auditable forecasting mechanics, payer playbooks tied to clinical evidence thresholds, and commercially pragmatic mitigations for supply and channel risk. The market’s steady growth profile creates predictable revenue trajectories, but value capture will be determined by evidence strategy, manufacturing foresight and early payer engagement — not just product efficacy.
Next steps — obtain the full intelligence
This press brief intentionally surfaces the strategic contours and high‑impact recommendations while preserving the granular segmentation and proprietary datasets that underpin our forecasts. For access to the full report — including the interactive model, detailed segmentation tables, competitor scorecards and downloadable decision tools — visit PW Consulting’s official market research page or contact our advisory team to arrange a tailored briefing and dataset license. Early licensees will receive priority access to our custom scenario support for 2026 tactical planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Medications for Cutaneous Mastocytosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com