

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pearls Market Valued at USD 4.15 Billion in 2025 — Poised for Continued Growth

Pearls Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
Executive snapshot
PW Consulting’s Pearls Market report (base year 2025; forecast period 2026–2032) synthesizes market dynamics that should shape executive choices in 2026. The global pearls market has moved from roughly USD 3.3 billion in 2020 to about USD 4.15 billion by 2025, and our models show it expanding at a 5.25% CAGR through the 2026–2032 forecast window. By the early 2030s the market approaches the USD 6.0 billion threshold under our central case. All figures reported herein are in USD (Million).
Pearls Market
Why this matters for 2026 decision‑making
Pearls are re-emerging as a strategic category for luxury houses, specialty jewelers, and vertically integrated farm‑to‑retail players. The sustained mid‑single digit growth profile reflects a mix of premium channel stability, emerging middle‑market demand, and an inflection toward provenance‑driven purchasing. For 2026, leaders must balance three near‑term priorities: protecting margin under price and tariff pressure; capturing value from traceability and sustainability narratives; and realigning routes‑to‑market for an increasingly digital luxury consumer.
Pearls Market
What the report delivers (practical tools for strategists)
- Granular market sizing and trend narratives calibrated to 2020–2025 historicals and 2026–2032 forecasts, including alternative scenarios to stress test growth under trade and demand shocks.
- A decision‑grade competitive playbook mapping 7+ global players (profiles, headquarter locations, capabilities, selected strategic moves) and implications for partnerships, co‑branding, and M&A.
- Actionable go‑to‑market frameworks: channel prioritization guides for luxury vs. accessible segments, omnichannel merchandising blueprints, and digital conversion levers proven in high‑value jewelry categories.
- Supply‑chain resilience and sourcing protocols: risk heat maps, supplier due‑diligence checklists, and a playbook for integrating traceability technologies (blockchain, DNA tagging, independent third‑party verification).
- ESG and provenance toolkits: audit templates aligned with the expanded industry classification standards, guidance for claims substantiation, and templates for sustainability reporting tailored to pearl producers and retailers.
- Commercial levers: pricing architecture experiments, promotion and markdown frameworks, and elasticity diagnostics adapted for premium pearl assortments and broader jewelry sets.
- M&A and portfolio optimization templates: valuation cushions for farmed vs. manufactured inventory, integration checklists, and priority target profiles for roll‑up plays in a fragmented supplier base.
Market structure and competitive dynamics
The market remains fragmented at scale: the top three players account for under one‑fifth of global market value while the top five capture roughly a quarter. These concentration metrics highlight two strategic realities. First, there is room for value creation through consolidation and brand‑led aggregation. Second, market access and distribution are as critical as primary production — control over channels and storytelling amplifies value capture more than pure raw‑material ownership in many cases.
Pearls Market
Key incumbents are executing materially different strategies that offer templates and cautionary tales for 2026 planning:
- Mikimoto (Tokyo, Japan; https://www.mikimoto.com) remains the archetypal heritage brand. Its emphasis on premium Akoya innovation and luxury verticals underlines the durable power of provenance, craftsmanship narratives, and selective channel management.
- Tasaki (Kobe, Japan; https://www.tasaki-global.com) represents a vertically integrated luxury playbook combining farming control with design and retail. Tasaki’s model demonstrates how integration can protect margins and accelerate product innovation, but demands capital intensity and operational expertise.
- Paspaley (Darwin, Australia; https://www.paspaley.com) and Jewelmer (Makati, Philippines; https://us.jewelmer.com) illustrate the premium South Sea segment’s premiumization strategy: heavy emphasis on sustainability credentials, provenance storytelling, and direct relationships with luxury houses and collectors.
- Atlas Pearls (Subiaco, Australia; https://atlaspearls.com.au) exemplifies production‑to‑distribution scale in white and silver South Sea segments, highlighting the importance of diversified sourcing footprints to manage environmental and regulatory risk.
- Chow Tai Fook (Hong Kong; https://www.chowtaifook.com) demonstrates how mass luxury retailers can use broad Asian distribution reach to scale pearl jewelry assortments, making pearls a volume category as well as a prestige subcategory in specific markets.
- Zhejiang Grace Pearl Jewelry Co., Ltd (Zhuji, China) is indicative of the freshwater production base and manufacturing depth in China — an operational powerhouse that faces distinct regulatory and trade headwinds but offers cost and scale advantages for fast‑moving assortments.
Regulatory, industry and geopolitical drivers
The industry is experiencing a wave of institutionalization and standardization. In 2025 the international pearl community expanded its technical and classification resources, and the launch of an industry development body has begun to shift the operating baseline toward verifiable sustainability and standardized grading. These developments matter commercially: classification and traceability can justify price premiums in discerning luxury channels but will raise compliance and audit costs, particularly for smaller farms and manufacturers.
Geopolitical and trade tensions are non‑trivial. Trade discussions in 2025 referenced tariffs that, if enacted at the upper ranges discussed, could materially alter relative cost positions for key origin markets and compress margins across certain freshwater supply chains. Executives should therefore treat tariff volatility as a first‑order risk in sourcing, pricing, and inventory planning for 2026.
Strategic implications and recommended moves for 2026
- Prioritize provenance and traceability investments. Short‑term audit and certification costs will pay back through brand trust and higher realized prices in premium channels. Engage with industry bodies and the new development community to shape standards and gain early adopter advantage.
- Build flexible sourcing hubs. Hedge tariff and biological risks by diversifying suppliers across saltwater and freshwater origins and by developing contingency inventories that can be channeled to different markets.
- Design premium experiences around verified sustainability. Packaging, storytelling, and digital trace narratives that can be independently verified are becoming core purchase drivers for affluent consumers and institutional buyers alike.
- Explore roll‑up opportunities where scale brings immediate synergies — particularly in downstream manufacturing and retail distribution. The fragmented nature of the market creates attractive windows for consolidation with clear value‑creation roadmaps.
- Adapt pricing architectures to protect margin while stimulating volume: consider tiered provenance premiums, limited‑edition runs tied to documented sustainability events, and partnership lines with high‑profile designers to stretch brand equity.
- Invest in direct digital engagement. A differentiated online luxury experience (interactive provenance journeys, high‑fidelity product visualization, virtual try‑on) reduces dependence on physical retail and improves lifetime value economics.
What we intentionally withheld — and why
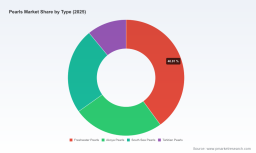
To preserve the report’s role as a decision‑grade subscription asset, we have deliberately presented the strategic narrative and tools while withholding the full segmented datapacks and proprietary regional/application breakdowns in this release. Readers seeking the granular revenue splits, fine‑grained regional movements, SKU‑level pricing matrices, and the full model workbook should consult the Pearls Market report page on the PW Consulting site. The withheld data are essential for transactional decisions (pricing, sourcing contracts, target valuation) and are provided to subscribers alongside scenario models and editable financial templates.
Conclusion — a 2026 lens
Pearls as a category presents a compelling strategic mix for 2026: resilient growth, meaningful premiumization potential, and an operating environment being reshaped by standards and trade risk. Executives who treat 2026 as a year to invest in provenance, build flexible supply chains, and selectively pursue scale will materially improve their odds of capturing disproportionate value as the market matures toward the early 2030s. PW Consulting’s Pearls Market report equips leadership teams with the frameworks, risk scenarios, and playbooks needed to translate these macro trends into executable plans.
Next steps
For the complete dataset, segmentation matrices, editable models, and subscriber‑only scenario planning tools, visit the Pearls Market report page on PW Consulting’s website or contact our market analytics desk. Our team can also arrange tailored briefings to translate the findings into a 90‑day strategic roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com