

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pet Veterinary Diets Market to Surpass USD 20.22 Billion by 2032, Expanding at a 5.81% CAGR

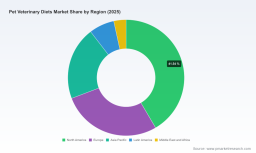
Worldwide Pet Veterinary Diets Market: Strategic Preview for 2026 Decision-Makers
PW Consulting — Executive Snapshot
As animal health continues to professionalize, veterinary diets have evolved from niche therapeutic lines into a strategic growth pillar for both specialty animal health firms and large consumer-oriented pet food manufacturers. Our new Worldwide Pet Veterinary Diets Market study (base year 2025) synthesizes historical performance, near-term inflection points and a forward-looking scenario set for 2026–2032. At the macro level the market is sizable and growing: the global market was above USD 13.6 billion in 2025 and, with a compound annual growth rate of approximately 5.8% through the forecast horizon, is projected to move materially higher by the early 2030s.
Worldwide Pet Veterinary Diets Market
Why this matters for 2026 corporate strategy
- Strategic priority: Veterinary diets are simultaneously a clinical offering and a commercial differentiator — they build practitioner trust, create recurring revenue through prescription follow-up, and act as a margin-enhancing portfolio lever.
- Timing: 2026 is a decision year for product pipelines and capacity investments initiated in 2023–2025. The gap between clinical evidence development and manufacturing scale-up means choices now determine market positioning for at least the next five years.
- Value trade-offs: Companies must balance investment in clinical trials and palatability with channel control (veterinarian-exclusive vs. retail) and compliance overhead. Those trade-offs are fundamentally commercial decisions with technical inputs; our report maps them end-to-end.
High-level market dynamics
Three dynamics will influence corporate outcomes in 2026 and beyond:
Worldwide Pet Veterinary Diets Market
- Demand sophistication: Veterinarians and informed pet owners increasingly expect therapeutic claims to be backed by clinical evidence, leading to longer product development cycles but stronger pricing power for validated solutions.
- Cost pressure and margin management: Raw material volatility — exemplified by commodity movements such as corn price cycles — places renewed emphasis on formulation flexibility and supplier diversification. Manufacturers that can de-risk ingredient sourcing without degrading palatability will preserve margins.
- Regulatory and trade complexity: Feed labeling and therapeutic claims are regulated differently across jurisdictions. Compliance frameworks require stronger documentation and, in many cases, vet-supervised distribution. Import controls and periodic alerts further complicate global supply chains.
Supply-side and operational considerations
- Manufacturing quality and certifications are table stakes. Recent site certifications demonstrate the premium placed on consistent, auditable production. For manufacturers, achieving and communicating recognized food-safety and quality accreditations will be essential to sustain vet channel trust.
- Channel economics favor vertically integrated models and strong veterinarian partnerships. The prescription-only distribution model protects therapeutic positioning but requires investment in professional education and compliance systems.
- Formulation innovation must reconcile clinical efficacy with palatability and cost. Hydration-focused wet formats, tailored renal and dermatology compositions, and nutraceutical integrations are areas of product-level differentiation.
Competitive landscape — what to watch
The market structure displays a high degree of concentration among established veterinary nutrition specialists and large integrated pet-care companies. Top competitors combine clinical investments, vet-channel distribution, and brand equity to maintain privileged access to prescribers. Our analysis identifies a pattern of strategy archetypes rather than a single dominant playbook:
Worldwide Pet Veterinary Diets Market
- Vet-specialist incumbents: Companies built on prescription-based therapeutics focus on deep clinical evidence, veterinarian relationships, and product portfolios targeted at specific pathologies. Their competitive moat is clinical trust and distribution control.
- Consumer-oriented multinationals: Large pet-food manufacturers leverage scale in manufacturing, global supply chains and brand recognition to expand into therapeutic lines while maintaining professional distribution through partnerships and dedicated business units.
- Mid-sized diversified animal health firms: These players often combine targeted nutrition offerings with adjacent pharmaceutical or diagnostics portfolios, enabling integrated clinical pathways for complex conditions.
Representative recent moves illustrate tactical priorities: selective product launches for sensitive-skin and renal formulas, portfolio sizing adjustments to improve palatability and hydration, and investments in manufacturing certifications. Collectively these actions signal three persistent bets—clinical differentiation, palatability engineering, and operational assurance—that will shape competitive positioning in 2026.
Regulatory and quality guardrails
- Labeling and therapeutic claims are tightly regulated; firms must align product positioning with jurisdictional requirements and maintain documentation supporting nutritional adequacy statements.
- Registration and establishment compliance pose non-trivial market-entry hurdles in many regions; regulatory strategy should be integrated into product development timelines to avoid launch delays.
- Trade and import controls mean source-country risk must be assessed as part of supplier selection and contingency planning.
What the PW Consulting report contains — practical outputs
This study is structured as a practitioner’s toolkit for commercial, R&D and corporate development teams. Key deliverables include:
- Top-line market sizing and demand scenarios (historical and forecast through 2032), with sensitivity runs for alternative macroeconomic and commodity assumptions.
- Go-to-market frameworks tailored to distribution models: vet-exclusive, hybrid (vet + retail), and direct-to-consumer approaches, with channel economics and margin overlays.
- Product innovation playbooks covering indication prioritization, palatability testing protocols, real-world evidence generation, and regulatory pathway mapping.
- Supply chain stress-testing tools, including an ingredient-cost sensitivity model and recommended hedging and supplier diversification strategies.
- Competitive benchmarking and M&A scoping tools: capability matrices, acquisition screening criteria, and integration checklists for nutrition-technology assets.
- Risk and compliance heatmaps covering labeling, import/export controls, and recall mitigation strategies.
- Commercialization checklists and 100-day launch plans for veterinary diet introductions, designed for launch-readiness and rapid practitioner adoption.
Actionable recommendations for 2026 planning
Below are priority actions we recommend executives adopt when defining 2026 strategies:
- Prioritize clinical evidence investment for at least one high-return indication. A single, well-evidenced product can unlock veterinarian prescribing and support premium pricing.
- Strengthen channel partnerships through co-developed education programs and outcomes tracking that demonstrate real-world benefit to practitioners.
- Implement a raw-material hedge and dual-sourcing strategy for key carbohydrate and protein inputs to limit exposure to commodity swings.
- Accelerate manufacturing quality programs and seek recognized third-party certifications to facilitate market access and reassure professional buyers.
- Design portfolio roadmaps that balance wet and dry formats with palatability as a non-negotiable metric for clinical acceptance.
- Explore bolt-on acquisitions that add clinical trial capability, veterinary CRM platforms, or regional distribution strength rather than purely revenue-focused targets.
- Operationalize regulatory readiness: pre-clear labeling claims, align documentation with jurisdictional standards, and build a rapid response protocol for import or recall events.
How to use this “trailer” and where to get the full intelligence
This article is deliberately designed as a strategic preview. It outlines the most material forces shaping the veterinary-diets market and provides tactical signposts for 2026 planning. The full PW Consulting report contains the granular datasets, regional and product segmentation, and scenario-modeled outcomes that corporate strategy, M&A teams, and commercial leaders require to execute decisively.
For access to the complete analysis — including segment-level revenue forecasts, regional splits, product-type dynamics, animal-type and indication breakdowns, and downloadable modeling tools — please consult the PW Consulting report landing page or contact your PW Consulting account lead. The full dataset will enable precise portfolio optimization, resource allocation and execution roadmaps that are calibrated to your organization’s risk appetite and growth objectives.
Closing perspective
Veterinary diets represent a unique intersection of science, commerce and regulation. For firms that align evidence-generation, manufacturing excellence and channel economics, the coming windows of opportunity in 2026 are substantial. For those that delay, cost volatility and regulatory complexity will raise the barrier to entry. PW Consulting’s report is built to convert market-level intelligence into boardroom-ready decisions — a necessary input for any growth plan in this maturing but still dynamic segment of the pet-care ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Veterinary Diets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com