

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Industrial Diaphragm Pump Market to Grow at 5.15% CAGR — From USD 6,860.7 Million in 2025 to USD 9,750.6 Million by 2032, Led by Asia Pacific (USD 2,770.5M)
By pmarketresearch, 2026-07-15
Worldwide Industrial Diaphragm Pump Market — Strategic Outlook for 2026
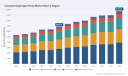
PW Consulting’s latest market intelligence brief — based on a comprehensive base year of 2025 and a validated historical series from 2020–2025 with forward-looking projections through 2032 — delivers a decision-grade perspective for executives shaping strategy in 2026. The global industrial diaphragm pump market reached approximately USD 6.86 billion in 2025 and, under our primary scenario, is expected to grow at a compound annual growth rate (CAGR) of 5.15%, reaching near USD 9.75 billion by 2032. These headline dynamics belie important inflection points that will determine winners and losers over the next business cycle; our report isolates those inflections and translates them into executable options for manufacturers, OEMs, investors, and procurement leaders.
Worldwide Industrial Diaphragm Pump Market
The strategic imperative for 2026
Industrial diaphragm pumps are no longer a commodity play defined only by flow and pressure curves. Regulatory tightening in wastewater and effluent control, increasing focus on lifecycle energy consumption, material-science driven durability improvements, and a wave of electrification and sensing integration are reconfiguring value pools across the industry. For organizations making 2026 capex, R&D, M&A, and supply-chain commitments, lagging on any one of these fronts risks obsolescence; conversely, targeted moves can secure outsized returns. This report is designed as an operating manual for that moment: it converts macro trends into board-room-ready options and tactical roll-outs.
Worldwide Industrial Diaphragm Pump Market
Key market dynamics shaping opportunity and risk
-
Regulatory acceleration: Stricter environmental standards for wastewater discharge and fugitive emissions are expanding demand for sealless and chemically compatible diaphragm solutions. Compliance requirements are elevating equipment selection from engineering preference to a mandatory procurement filter for many industrial end users.
Worldwide Industrial Diaphragm Pump Market -
Energy and electrification: Advances in electrically operated diaphragm pumps — including models reporting substantial energy reductions compared with legacy designs — are altering lifecycle cost calculations. Energy efficiency mandates and corporate decarbonization targets amplify the commercial advantage of low-power, electronically optimized units.
-
Material supply and cost volatility: PTFE remains the benchmark for chemical resistance in diaphragm materials, and demand for PTFE in pump components is meaningful. At the same time, fluctuations in stainless steel, aluminum, and high-grade elastomer pricing since 2024 have widened manufacturer cost dispersion and impacted average selling prices (ASPs). Manufacturers must model raw-material exposure with the same rigor applied to product performance.
-
Functional convergence and digitalization: Integrated sensing (flow, pressure, vacuum) and smart control are moving from aftermarket add-ons to design priorities. The first wave of pumps with factory-integrated sensing and dosing control is already in the market, changing service propositions and enabling new recurring revenue models.
-
Safety and hazardous-area compliance: Standards such as ATEX and ISO fugitive-emission limits are prompting wider adoption of explosion-proof and sealless diaphragm designs across petrochemical and oil & gas segments. Certification timelines are becoming a critical gating factor for market entry in hazardous environments.
What the report delivers — practical, operational content
-
Actionable market-size and scenario models: validated baseline (2025) and three consensus scenarios through 2032, with sensitivity levers for energy costs, raw-material shock, and regulation intensity.
-
Demand and application playbooks: granular use-case matrices mapping pump types to industrial processes, retrofit potential, and procurement cycles — prioritized by ROI for 12–36 month time horizons.
-
Cost-to-serve and ASP benchmarking: manufacturing cost-driver breakdowns, BOM exposure maps for PTFE and metals, and pricing playbooks for premium vs. value segments.
-
Supply-chain and sourcing risk toolkit: supplier maps, lead-time scenarios, single-source exposure analysis, and hedging strategies for critical materials including elasticities for 2026 procurement planning.
-
Technology and product roadmaps: comparative analysis of air-operated vs. electrically operated diaphragm technologies, integration pathways for sensors and controls, and recommended R&D sprints to capture energy- and compliance-driven market segments.
-
Commercial & service models: aftermarket economics, remote-monitoring subscription design, and case studies demonstrating payback profiles for electrified and digitally instrumented pumps.
-
M&A and partnership playbook: target profiles, valuation heuristics, integration checklists, and five hypothetical M&A scenarios calibrated to 2026 market dynamics.
Competitive landscape — strategic positioning and implications
The competitive field includes diversified fluid-handling conglomerates, specialized diaphragm innovators, and regional manufacturers pursuing cost and application niches. Rather than rehearse product lists, our analysis interprets strategic posture and near-term moves from leading participants to expose patterns and opportunities.
-
Global fluid-handling majors (examples include companies with wide industrial portfolios): these firms leverage scale and channel breadth to win large projects and aftermarket contracts. Their strategic advantage lies in cross-selling pump systems and integrating diaphragm technologies into broader fluid-motion offerings. For incumbents, the play is to accelerate electrified and certified product lines while embedding service contracts that monetize sensing upgrades.
-
Specialized diaphragm innovators (manufacturers focused on high-pressure or metering accuracy): their edge is material science and precision engineering. For this cohort, defending IP in hydraulically actuated and metering diaphragm technologies and commercializing precision dosing for pharmaceutical and chemical users is critical.
-
Air-operated AODD leaders (companies with deep portfolios in air-operated diaphragm pumps): they continue to dominate applications where volatility, flammability, or solids handling matter. Strategic actions include modular designs that ease conversions to sealless or sensor-enabled variants and partnerships with materials suppliers to secure availability of critical elastomers.
-
Emerging electric and smart entrants (suppliers launching electric diaphragm pumps with integrated controls): the early launches of sensor-integrated models and electric platforms signal a technology inflection. Organizations in this group should prioritize field trials that quantify lifecycle energy savings and transition from one-off sales to subscription service models.
Recent product introductions illustrate these dynamics in real time: manufacturers have debuted diaphragm pumps with integrated flow/pressure/vacuum sensing, high-flow plastic AODD models optimized for chemical transfer, electric diaphragm pumps with pressure-relief controllers tailored for environmental applications, and new electric models focused on efficiency and uptime. These launches validate the market’s direction toward energy-efficient, digitally enabled, and materials-specialized solutions.
Priority actions for executives in 2026
-
Re-evaluate R&D portfolios against two lenses — energy intensity and regulatory compliance. Shift at least one product platform roadmap toward electrification and sensor integration with defined payback thresholds.
-
Build raw-material resilience programs. Model exposure to PTFE and high-grade elastomers and secure dual-source arrangements or long-term purchase agreements where feasible.
-
Design aftermarket-as-a-service propositions tied to remote monitoring and predictive maintenance. Early pilots should target high-value wastewater and chemical customers where uptime and compliance yield clear willingness-to-pay.
-
Prioritize certification timelines for hazardous-area and fugitive-emission standards. Being first-to-certify in a major regional market can act as a durable entry barrier.
-
Assess targeted inorganic options: acquire complementary sensor, control, or material-compatibility capabilities rather than bolt-on capacity. Our M&A playbook identifies four archetypal targets aligned with these goals.
-
Implement dynamic pricing frameworks that factor in raw-material indices and energy performance premiums to protect margins while communicating lifecycle value to buyers.
Why PW Consulting’s report matters for your 2026 decisions
Beyond headline market numbers, our study provides the operational tools that enable confident execution. We combine bottom‑up demand modeling, equipment-level energy simulations, BOM-level material exposure, vendor capability mapping, and validated interviews across the supply chain and end-user base. Each analytical stream is translated into recommended tactical actions, lined with timelines and expected ROI ranges — not just “what” but “how” to capture value in 2026 and beyond.
We intentionally present the public-facing insight set in this release to establish the strategic frame and demonstrate analytical rigor. For companies that require executable metrics — e.g., product-level profit curves, geo-prioritization maps, supplier scorecards, and scenario-tested investment cases — the full report and supporting data pack provide the necessary granularity to operationalize strategy.
Next steps
For C-suite teams preparing capex plans, commercial leaders reshaping product portfolios, or investors assessing consolidation and growth plays, PW Consulting’s Worldwide Industrial Diaphragm Pump Market report is a practical toolkit for 2026. Visit our report page to request the full dataset, bespoke scenario runs, and an executive briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Livestock Diagnostics Kits Market Tops USD 1,845.5 Million in 2025 — Growth Momentum Ahead
By pmarketresearch, 2026-07-15
Worldwide Livestock Diagnostics Kits Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Livestock Diagnostics Kits Market is released as a targeted strategic briefing for executives who must take decisive action in 2026. This preview distills the report’s most actionable themes — the macro trajectory, regulatory inflections, technology vectors, and competitor behavior — while intentionally withholding full segmented tables and proprietary models to guide you to the full report for transaction-ready detail.
Worldwide Livestock Diagnostics Kits Market
Executive snapshot: Why this market matters in 2026
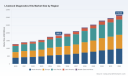
Livestock diagnostics are no longer a niche support function: they are a strategic layer in biosecurity, trade enablement, and sustainability for food systems. Our topline market sizing shows a clear expansion from a 2020 baseline to a materially larger industry by mid-decade. In 2025 the market size reached USD 1,845.5 Million (revenue, Million USD), and under the scenarios modeled in this study the market is projected to grow at an 8.0% compound annual growth rate across the 2026–2032 forecast window, reaching USD 3,162.86 Million by 2032. That trajectory creates a multi-year runway for product investment, channel development and consolidation activity — with very different implications for players depending on their technology focus and go-to-market model.
Worldwide Livestock Diagnostics Kits Market
What is changing beneath the headline growth?
- Regulatory harmonization and trade pressure: International standardization efforts (notably WOAH’s diagnostic register and validation frameworks) and tightened importer requirements are raising baseline expectations for test validation, traceability and lot-release controls. In parallel, national authorities (for example USDA APHIS guidance updates) are clarifying validation and expiry policies for immunodiagnostic kits — raising the bar for manufacturers and increasing the value of compliance-minded suppliers.
- Faster, smarter field diagnostics: The market is experiencing sustained technology intensification. Multiplex PCR panels and next-generation lateral flow formats are delivering step-change improvements in sensitivity and speed — industry data point to accuracy gains approaching the high‑90s for some panels and on-farm results in under 15 minutes for rapid assays. That performance compression redefines the buyer conversation around on-farm versus lab-based testing.
- Consolidation with pockets of specialization: Market concentration is moderate: the three largest firms account for a significant share of supply, and the top five approach 60% market share. This creates a dual environment where large incumbents set standards and distribution footprints, while specialist and regional players exploit niche platforms, species-specific expertise and local regulatory relationships.
- Supply-chain and raw material sensitivity: Manufacturers report ongoing constraints for critical reagents and proprietary consumables, with implications for time-to-market and margin resilience. Vertical integration, diversified sourcing and strategic inventory practices are emerging as defensive measures.
Implications for corporate strategy in 2026
For executives planning capital allocation, product roadmaps, or M&A in 2026, the full report translates the macro trend into three practical decision levers.
Worldwide Livestock Diagnostics Kits Market
- Prioritize validated, trade-compliant products: With cross-border trade protocols tightening, companies that can demonstrate WOAH-aligned validation and clear regulatory dossiers will unlock premium channels (export certifications, institutional procurement). Our validation checklist and country-specific compliance matrix in the full report show how to fast-track a regulatory submission program while preserving launch timelines.
- Refine platform strategy — speed vs. breadth: The market rewards both extremely fast, point-of-care devices and broad, multiplex lab platforms. Companies should map investments against three buyer archetypes we quantify in the report — large commercial farms, veterinary networks, and public-sector surveillance programs — and choose whether to specialize, partner or develop hybrid offerings. The report includes a decision framework to evaluate ROI under different adoption curves and reimbursement assumptions.
- Defend margins with channel and supply strategies: As reagent costs and validation expenses rise, margin management becomes strategic. We outline tactical levers including cartridge-based consumable economics, subscription/consumable bundles, and distributor incentive structures that preserve installed-base revenue while enabling competitive pricing for base kits.
Competitive landscape — who matters and why
The competitive map is a mix of global platform providers, diagnostic specialists and vertically integrated animal health firms. Key players profiled in our analysis include, among others, IDEXX Laboratories, Zoetis, Thermo Fisher Scientific, Neogen, bioMérieux, Virbac and Bio‑Rad — each with distinct strengths:
- IDEXX Laboratories, Inc. (Westbrook, Maine, USA) — Strength: broad portfolio spanning ELISA, PCR and rapid on-farm tests with deep lab and field channels. Strategic advantage: trusted brand in veterinary diagnostics and established distribution to veterinary practices.
- Zoetis Inc. (Parsippany, New Jersey, USA) — Strength: integrated product-plus-service model and point-of-care platforms (recent launches underscore a focus on AI-enabled hematology and rapid field diagnostics). Strategic advantage: strong farmer and veterinarian relationships that facilitate rapid rollout of new point-of-care systems.
- Thermo Fisher Scientific Inc. (Waltham, Massachusetts, USA) — Strength: robust molecular diagnostics capability and regulatory experience, with USDA-licensed solutions for surveillance. Strategic advantage: scale and laboratory channel penetration.
- Neogen Corporation (Lansing, Michigan, USA) — Strength: rapid and immunoassay solutions targeting food-safety and on-farm testing. Strategic advantage: cross-over into feed and food-testing channels.
- bioMérieux, Virbac, Bio‑Rad and others — Strengths vary from specialized ELISA and molecular offerings to regional market depth and veterinary services. Strategic advantage: niche expertise and tailored solutions for particular disease classes and markets.
Recent product activity corroborates the innovation dynamic: platform launches in 2024–2025 (for example AI-enhanced point-of-care hematology platforms and expanded diagnostic panels) indicate incumbents are investing in faster, integrated workflows that pair diagnostics with digital decision support.
What the full PW Consulting report delivers (operational, not theoretical)
This release is a strategic preview. The complete report goes far beyond high-level narrative to deliver tools executives can use immediately:
- Transparent market sizing methodology and downloadable model (TAM/SAM/SOM) that lets you rebase scenarios against your own product timelines.
- Regulatory playbook and validation action plan, including a country-by-country compliance heat map and sample dossier templates to shorten approval cycles.
- Channel and pricing models with break‑even analyses for cartridge, kit and service-based monetization strategies; distributor scorecards and suggested incentive structures.
- Technology adoption roadmaps and a buyer-segment matrix that connects product features to purchasing criteria across commercial farms, veterinary clinics and state surveillance programs.
- Competitive benchmarking dashboards and an M&A target shortlist with scoring on technology fit, regulatory readiness and cultural integration risk.
- Operational checklists for scaling production under reagent supply constraints and a supplier-risk mitigation appendix.
We intentionally withhold granular regional and application-level splits in this preview; those detailed tables — which are essential for precise launch-forecasting and valuation work — are available in the full report and interactive model.
Practical scenarios for 2026 planning
To convert growth into value in 2026, companies should evaluate three scenarios we model in the report:
- Fast-innovation incumbent: Invest in point-of-care platforms and consumable lock-in. Outcome: premium pricing and faster installed-base monetization, but higher R&D and regulatory expense.
- Focused specialist: Concentrate on niche disease panels, partnerships with regional labs and targeted export corridors. Outcome: lower capital intensity, high margin on specialty assays, but limited scale.
- Aggregator/Merger-driven consolidator: Acquire complementary technology or geographic reach to close the gap with top-tier providers. Outcome: rapid share gains and broader product portfolios, with integration and validation risk that must be managed carefully.
Regulatory and market risks — and mitigation
Key risks are regulatory non-alignment, supply-chain shocks and rapid obsolescence of legacy assays. Mitigations explored in the report include adopting WOAH-aligned validation practices early, diversifying reagent suppliers, and implementing phased rollouts that front-load regulatory-critical markets while using pilot programs to tune instruments and consumables.
Conclusion — how to use this preview
This briefing provides a senior-executive view of forces shaping the livestock diagnostics market as you set budgets, product roadmaps and M&A mandates in 2026. The topline numbers signal a healthy, investable market: a near‑doubling of industry value from early‑decade baselines to the end of our forecast horizon. But the real opportunities — and the risks — lie in product validation, channel design and supplier resilience. PW Consulting’s full report supplies the actionable models, regulatory templates and competitor dossiers to convert the macro trend into concrete growth and valuation outcomes.
Next steps
For procurement-ready competitive matrices, downloadable scenario models and the validation playbook that are necessary to execute in 2026, please consult the full Worldwide Livestock Diagnostics Kits Market report. This preview is designed to orient your strategy; the full deliverable will enable operationalization and transaction workstreams.
For detailed analysis of this topic, please visit the official page: Worldwide Livestock Diagnostics Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Optoelectronic Safety Laser Scanner Market Poised for 7.15% CAGR in 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Optoelectronic Safety Laser Scanner Market: Strategic Preview for 2026 Decisions
Executive summary
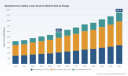
PW Consulting’s latest market study on the worldwide optoelectronic safety laser scanner market delivers a focused, decision‑centric view designed for executives planning product, procurement, and M&A moves in 2026. The market has expanded steadily from a base of approximately USD 420 million in 2020 to roughly USD 585 million in 2025, and our modelling shows continued momentum into the coming decade — with a compound annual growth rate of 7.15% across the 2026–2032 forecast window and an expected market size approaching USD 950 million by 2032. This briefing highlights the structural forces, competitive dynamics, and practical playbooks that will determine winners and laggards next year, while reserving the detailed segment-level datapoints to the full report to protect the value of our proprietary modelling.
Worldwide Optoelectronic Safety Laser Scanner Market
Why 2026 is a pivotal planning year
-
Technology transition: Component and sensor innovation is shifting the product set from classic 2D Type‑3 scanners to higher-capability 3D and multi‑echo LiDAR solutions that broaden safe‑perception envelopes for mobile and outdoor applications.
Worldwide Optoelectronic Safety Laser Scanner Market -
Standards and certification updates: Regulatory clarifications and standards revisions are reshaping installation practices and system architectures, prompting engineering teams to revalidate risk assessments and update safety calculators.
Worldwide Optoelectronic Safety Laser Scanner Market -
Supply‑chain stress: Concentration in upstream compound semiconductor supply and export policy shifts have increased lead times and price volatility for critical laser-diode wafers, forcing procurement and product‑planning tradeoffs that will reverberate through 2026.
Market trajectory in plain terms
Our historical time series shows steady, resilient growth: the global market rose from approximately USD 420 million in 2020 to about USD 585 million in 2025. Looking forward, the market is forecast to continue expanding at a mid‑single‑digit to high‑single‑digit pace (7.15% CAGR across 2026–2032), driven by accelerated adoption in automated material handling, expanded deployment in automotive and mobile robotics, and the increasing use of scanners as integrated perception elements in larger safety architectures.
Key structural dynamics
-
Consolidation and concentration: The market exhibits clear concentration at the top. The leading firms together hold a material share of the market, creating scale advantages in R&D, certification pathways, and global service footprints. This concentration favours firms that can pair product breadth with channel depth.
-
Component dependency risk: Laser diodes and compound semiconductor wafers remain critical bottlenecks. Prolonged lead times and price inflation in upstream materials — exacerbated by geopolitics and export controls — increase the value of supply diversification, contract hedging, and backward integration strategies.
-
Standards tightening: Updates to installation standards and safety distance calculations are raising the technical bar for compliant system design, making certified firmware, validated safety calculators, and interface flexibility (industrial safety protocols) decisive procurement criteria.
Competitive landscape — what to watch
The competitive field mixes longstanding safety specialists with automation and sensing incumbents. Across the vendor set, three strategic archetypes are emerging: platform incumbents with broad product portfolios and deep certification capabilities; focused sensor specialists targeting size, robustness, or cost niches; and system vendors integrating scanners into wider automation solutions.
-
SICK AG has broadened its roadmap into 3D perception for outdoor mobile applications, introducing high‑aperture, safety‑certified LiDAR systems aimed at cranes, AGVs and other outdoor mobile platforms. Their investments exemplify a move toward multi‑echo, high‑range devices with rugged housings — a direct play for higher‑duty, safety‑critical mobile use cases.
-
Leuze electronic is capitalizing on tight‑space integration and compact footprints with ultra‑small scanners tailored for AGVs and AMRs. The vendor’s focus on footprint, scan angle and integration-friendly form factors underscores a tactical approach to proliferating scanners into space‑constrained automation designs.
-
Pilz has advanced network integration and installer usability by adding industrial Ethernet interfaces and updating its safety‑calculation guidance to align with recent standards changes — a practical move that reduces system integration friction for plant engineering teams.
-
KEYENCE and several automation majors are differentiating on detection range, environmental resistance and network safety stacks, bundling device‑level perception with diagnostics and vision elements for premium applications.
-
North American and Japanese providers are leveraging strong machine‑tool and controls channel relationships to embed scanners into wider automation propositions, while European specialists continue to set pace on safety certification and functional‑safety documentation.
Recent product and regulatory signals that matter for 2026
-
New 3D LiDAR launches with PL‑level safety certifications are lowering the cost of adopting three‑dimensional perception in safety use cases, but they also introduce new validation and maintenance requirements for safety engineers.
-
Compact, high‑angle 2D scanners facilitate densification of perception on small stateful robots and constrained machinery, changing design rules for vehicle architects and machine builders.
At the same time, revisions to positioning standards (notably the 2024 update to device‑positioning guidance) materially affect how safety distances are calculated for orthogonal and parallel approaches and introduce new allowances for measurement uncertainty and wear. Procurement teams should insist on vendor documentation that is explicitly mapped to these updated standards.
Implications for buyer and vendor strategies in 2026
-
For buyers — resilience and specification clarity: Establish multi‑vendor sourcing lanes for critical sensor classes; require verifiable compliance artifacts mapped to the latest standards; and specify interface and diagnostics expectations (e.g., Profinet/Profisafe, CIP Safety, EtherNet/IP) to minimize integration rework. Adopt inventory and contractual hedges for laser diode supply to manage lead‑time and price volatility.
-
For vendors — differentiation through systemization: Prioritize product families that ease certification work for integrators (pre‑validated zone templates, safety calculation toolkits, and firmware update pathways). Consider software and services (remote diagnostics, lifecycle support) as margin levers. Targeted investment in ruggedized, outdoor‑rated LiDAR and compact form factors will unlock adjacent markets.
-
For investors and M&A strategists: The market’s measured concentration and technology bifurcation create opportunities for bolt‑on deals that expand sensing portfolios, accelerate time‑to‑market for 3D perception, or fill channel gaps in high‑growth end markets such as logistics mobility. Expect value creation from acquiring complementary software or systems capabilities rather than single‑product plays alone.
Operational playbooks — what PW Consulting recommends now
-
Run scenario planning that stress‑tests product roadmaps against 12–36 month upstream lead‑time shocks and price scenarios for compound semiconductor inputs.
-
Mandate standards traceability: require vendors to supply test reports, safety cases, and installation guidance explicitly referencing current editions of IEC 61496, ISO 13849 and related norms.
-
Quantify the total cost of ownership for sensor options by modelling installation, certification, downtime and maintenance costs — not just capex.
-
Accelerate firmware and field‑service capability development to reduce time‑to‑repair and improve in‑field safety compliance monitoring.
What the full PW Consulting report contains (select highlights)
Our flagship study provides a complete set of strategic deliverables for 2026 execution, including: multi‑year historicals and granular forecasts, competitive scorecards and capability maps, a vendor M&A matrix, product benchmarking across safety classes and environmental ratings, supply‑chain risk heatmaps, regulatory impact scenarios and practical go‑to‑market playbooks for suppliers and end‑users. Note: to preserve the proprietary value of our segment modelling and vendor scoring, detailed segment‑level revenues and regional breakdowns are reserved for report subscribers and are not published in this press preview.
Methodology and confidence
The report synthesizes primary interviews with industry leaders, certification bodies and integrators; bottom‑up product‑level bill‑of‑materials analysis; and supply‑chain mapping for semiconductor inputs. Our concentration metrics and market sizing reflect reconciled top‑down and bottom‑up approaches, and the analysis explicitly captures geopolitical and raw‑material tail risks that influence lead times and pricing. We judge the probability distribution around our base forecast to be moderate‑to‑high in the near term, with downside exposure concentrated in supply‑led scenarios and upside tied to accelerated adoption of 3D perception in outdoor and mobile segments.
Next steps for executives
-
Procurement chiefs should secure multi‑source contracts for laser‑diode dependent modules and revisit buffer policies now.
-
Product and R&D leaders should prioritize certification roadmaps and integration toolkits that reduce installer burden and time‑to‑compliance.
-
Strategy and corporate development leaders should evaluate bolt‑on acquisitions that add sensor modalities, ruggedization know‑how, or global service scale.
For a complete set of datasets, vendor profiles, actionable scenario analyses and the full segmentation model (range, end‑user, and regional splits), access the full Worldwide Optoelectronic Safety Laser Scanner Market report on the PW Consulting publications page. Our team is available to provide tailored briefings and bespoke scenario modelling to support 2026 decision cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Occlusion Spray Market Set to Grow at a 5.28% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Occlusion Spray Market — Strategic Outlook for 2026: PW Consulting Releases Actionable Intelligence for Executive Decision-Making
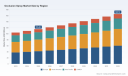
PW Consulting today publishes a new, in-depth market research briefing on the worldwide occlusion spray market, delivering a decision-ready assessment designed to inform corporate strategy and capital allocation for 2026. Built on a transparent methodology with a base year of 2025 and a historical window from 2020–2025, the report projects the market through 2032 (forecast period 2026–2032). Key topline metrics: the market is estimated at USD 115.45 Million (2025) and is modeled to grow at a compound annual growth rate (CAGR) of 5.28% over the forecast horizon, reaching USD 165.72 Million by 2032. These macro dynamics frame a period of steady, technology-enabled expansion that requires targeted plays rather than broad, undifferentiated investments.
Worldwide Occlusion Spray Market
Why This Report Matters for 2026 Strategic Planning
-
Timing and clarity: As companies finalize 2026 budgets and strategic roadmaps, the occlusion spray market presents a mix of steady demand from dental workflows and adjacent opportunities tied to digital scanning and industrial metrology. The report translates market momentum into concrete planning inputs—growth scenarios, sensitivity testing, and go-to-market implications calibrated to the 2026 planning cycle.
Worldwide Occlusion Spray Market -
Actionable market sizing: Our base- and forecast-year view provides executives with reliable topline figures (2023–2032) expressed in USD Million and a validated 5.28% CAGR. These data support revenue modeling, break-even analysis, and scenario-based investment cases without requiring firms to build independent market models from scratch.
Worldwide Occlusion Spray Market -
Regulatory and product risk clarity: The briefing synthesizes regulatory boundaries relevant to intra-oral use and medical-device compliance under key jurisdictions. This helps product and regulatory teams prioritize approvals and labeling strategies that materially affect market access in 2026.
Report Contents — What We Deliver
-
Comprehensive market architecture: A clear taxonomy covering product types, application streams, and distribution channels, with crisp definitions that eliminate ambiguity in cross-functional planning.
-
Topline and scenario forecasting: Base-case projections grounded in historical performance (2020–2025) and three scenario pathways for 2026–2032 to stress-test investment choices under varying demand, regulatory, and input-cost assumptions.
-
Competitor benchmarking: A structured assessment of incumbent and challenger suppliers across product breadth, regulatory approvals, channel footprint, and innovation orientation.
-
Commercial playbooks: Prioritized GTM tactics for market-entry, channel expansion, and commercial negotiations (including distributor vs. direct models), with tactical scorecards for 90–180 day execution.
-
Product and R&D tracker: Comparative feature matrix (colorants, solubility profile, scan-friendliness, propellant and environmental characteristics) that connects formulation choices to clinical and industrial use-cases.
-
Supply chain and manufacturing lens: Analysis of packaging formats, fill sizes, and procurement levers that influence COGS and service levels.
-
M&A and partnership playbook: Criteria and valuation heuristics for bolt-on acquisitions, joint ventures, and licensing arrangements—aligned with observed market concentration dynamics.
Competitive Landscape — Key Players and Strategic Positions
The occlusion spray market sits at the intersection of specialized dental consumables and adjunctive digital-scanning aids. Our competitive review highlights a mix of regional manufacturers and global niche suppliers that collectively shape product expectations and route-to-market norms.
-
Pascal International, Inc. (Bellevue, WA, USA): Positions itself on clinician safety and intra-oral approval. Its product portfolio includes formulations cleared for intra-oral use, allowing Pascal to appeal directly to dental practices seeking regulatory-compliant marking sprays for chairside procedures. This regulatory positioning is a durable advantage when selling into high-compliance channels.
-
Bausch (Dr. Jean Bausch GmbH & Co. KG, Cologne, Germany): A longstanding European supplier with a multi-color strategy and strong regulatory credentials. Bausch’s universal-indicator approach and emphasis on removable thin films supports both restorative labs and clinical fit-testing workflows.
-
Renfert GmbH (Hilzingen, Germany) and YETI Dentalprodukte GmbH (Engen, Germany): Both emphasize clear contrast marking and compatibility with prosthetic and model-making environments. Renfert focuses on detailed marking for model castings and restorations, while YETI promotes water-soluble variants useful in lab workflows.
-
DFS Diamon GmbH (Riedenburg, Germany): Differentiates on formulation stability—offering sprays that are insoluble in common solvents and resist discoloration on plaster models, which appeals to certain laboratory quality controls.
-
Vacalon (USA): Blends traditional contact-indicating functionality with digital-scan friendliness. Products that double as “scan sprays” create cross-selling opportunities with intraoral scanner workflows and industrial metrology users.
-
Indenco Dental Products (USA): A broad commercial supplier offering multiple colors and package sizes—well-suited to distributor channels serving both clinics and labs.
Collectively, market concentration metrics point to a moderately consolidated market: the top three and top five vendors capture material shares of aggregate industry revenue, leaving meaningful room for differentiated entrants and smaller specialists. This structure favors targeted consolidation and capability acquisitions rather than broad-scale horizontal expansion.
Regulatory and Product Dynamics to Watch in 2026
-
Medical-device clearance matters: Products permitted for intra-oral use under key regulatory frameworks command premium access to clinical channels. Compliance with established directives and guidelines materially shortens the adoption curve in higher-regulation markets.
-
Formulation trade-offs: Decision-makers must reconcile solubility (water-soluble vs. insoluble), color contrast needs, and residue behavior. These characteristics affect lab efficiency, fit accuracy, and downstream cleaning processes.
-
Packaging and format standardization: Common commercial package sizes (including typical aerosol volumes used in practice) shape inventory, distribution, and price-pack architecture across channels.
Strategic Imperatives — Priorities for C-Suites and Business Leaders in 2026
-
Prioritize product-market fit around digital workflows: Invest in formulations and marketing that explicitly support intraoral scanning and digital model capture. Partnerships with scanner OEMs or clinical digital workflow providers accelerate adoption.
-
Lock down regulatory pathways early: For companies seeking to move beyond distributor channels into direct clinical sales, securing relevant intra-oral approvals and CE/compliance documentation is a gating factor in 2026.
-
Optimize packaging and SKUs for distribution efficiency: Reduce SKU complexity where feasible and align fill sizes with distributor shelf economics to improve turnover and margins.
-
Targeted M&A: Seek bolt-on acquisitions that deliver formulation IP, regional manufacturing scale, or exclusive distribution rights. Given the measured degree of concentration, smart acquisitions can deliver step-change market access without prohibitive valuations.
-
Operational resilience: Diversify sourcing for propellants and colorants and plan for incremental environmental compliance costs tied to greener propellant options and waste-management requirements.
How Executives Should Use This Research in 2026
-
Corporate strategy teams can use the report’s scenario outputs to stress-test revenue targets and capital allocation plans for FY26.
-
Product teams should leverage the comparative formulation matrix to prioritize R&D investments that unlock premium clinical channels or enable industrial-scan adjacencies.
-
Commercial leaders can adopt the GTM playbooks to refine distributor agreements, map pricing tiers, and set promotional calendars aligned to dental buying cycles.
-
Investors and M&A teams will find the market concentration insights and valuation heuristics useful for identifying attractively positioned targets and quantifying synergies.
Next Steps and Accessing the Full Intelligence
This release is structured to preview the strategic value and practical takeaways of PW Consulting’s detailed report. The complete study includes granular segmentation, regional breakouts, product-level revenue tables, and supporting primary research appendices that are intentionally reserved for subscribers. Executives seeking to embed this intelligence in 2026 planning—across product development, regulatory roadmaps, commercial expansion, or M&A—should consult the full report to access the data tables and exhibits that drive tactical decisions.
To obtain the complete Worldwide Occlusion Spray Market report and the supporting decision tools, visit PW Consulting’s report portal or contact our commercial intelligence desk to request an executive briefing tailored to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Estate Agent Fees Market Poised to Expand at a 4.5% CAGR — Brokerage and Residential Services Drive Momentum
By pmarketresearch, 2026-07-15
Worldwide Estate Agent Fees Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a preview of our forthcoming market study, Worldwide Estate Agent Fees Market (base year 2025). This briefing is intended as an executive-level compass for boards, CFOs, corporate development teams and private-equity sponsors planning decisions for 2026. It highlights the high-level market trajectory, the structural forces reshaping fee economics, and the pragmatic playbook items that senior leaders must address — while reserving the full segment-level tables, pricing matrices and financial models for the complete report.
Worldwide Estate Agent Fees Market
Market trajectory at a glance
The estate agent fees market shows steady, predictable expansion across our forecast window. On a global basis the market grows from approximately USD 331.6 Billion in 2025 to USD 451.2 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 4.5% over 2026–2032. Year-on-year movement in the near term remains resilient despite regulatory and structural shocks, offering a dependable aggregate revenue pool for incumbents and new entrants alike.
Worldwide Estate Agent Fees Market
Two strategic implications flow directly from this trajectory. First, modest but persistent growth favours scale and efficiency: firms that can compress cost-per-transaction and broaden ancillary revenue (leasing, property management, valuation services) will unlock disproportionate margins. Second, the predictability of top-line expansion masks high internal volatility by market and service line — reinforcing why granular segment intelligence (included in the full report) is essential before committing capital.
Worldwide Estate Agent Fees Market
Key structural drivers and headwinds
-
Regulatory reshaping of the buyer-seller fee model. 2024 and 2025 ushered in regulatory interventions that materially altered long-standing marketplace mechanics. A major antitrust settlement in the US and subsequent rule changes have accelerated decoupling of buyer-agent compensation from seller-paid listings in multiple markets, creating pricing pressure on traditional commission pools and introducing new contractual workstreams for buyer agents. Concurrently, increased disclosure and fee-display enforcement in mature markets has amplified price transparency.
-
Technology-driven disintermediation and productivity gains. Virtual brokerages and transactional platforms continue to reduce fixed overheads while enabling aggressive client-facing price points. At the same time, automation and AI-based valuation and lead qualification tools increase agent productivity, enabling alternative commission splits and subscription-based agent economics.
-
Labour-market realities. Agent remuneration, workforce availability and talent economics remain central to cost curves. Median wages and total employment dynamics in primary markets affect unit economics for traditional brokerages and the feasibility of high-touch service models.
-
Consumer habit shifts. Cost-conscious sellers and digitally empowered buyers are increasingly experimenting with fee structures, exclusive vs. multi-agency models, and fixed-fee offerings. These preferences are diversifying the pathways by which fees are negotiated and realized.
Why the 2026 planning horizon is decisive
2026 is a pivot year for market participants because regulatory, technological and consumer trends that accelerated in 2024–25 will either consolidate or fragment business models over the next 18–24 months. Strategic choices made now determine whether a franchise or brokerage becomes a fee-compressing low-cost player, a high-service premium operator, or a platform aggregator. Four practical considerations should guide boardroom debates:
-
Reassess pricing architecture. The transition to explicit buyer-side agreements and increased fee transparency mandates revisiting default commission schedules, introducing tiered offerings (basic listing vs. full-service advisory), and evaluating fixed-fee options for specific price bands.
-
Reconfigure agent economics. Consider alternative splits, capping models, and subscription-based agent participation to align incentives for higher productivity while preserving retention in competitive labour markets.
-
Invest in automation where ROI is demonstrable. Prioritise investments that shorten time-to-close, reduce manual paperwork and improve lead-to-conversion ratios. Focus on tools with measurable per-transaction cost reductions and short payback periods.
-
Adapt market entry and M&A playbooks. With growth concentrated in specific service lines and geographies, M&A should be used tactically to acquire digital capabilities, local market share, or profitable ancillary services rather than as broad roll-up strategies without integration plans.
Report practicalities: what the full study delivers
Our complete Worldwide Estate Agent Fees Market report (base year 2025, forecast 2026–2032) is built for decision-makers who need executable intelligence, not just descriptive statistics. The report includes:
-
Top-down market sizing and a seven-year forecast with sensitivity scenarios (baseline, accelerated digital adoption, and regulatory stress cases).
-
Comprehensive revenue models and downloadable financial templates that allow users to stress-test commission schedules, agent-split alternatives and subscription models.
-
Commercial playbooks: productised pricing options, channel strategies for buyer vs. seller acquisition, and retention levers for high-performing agents.
-
Regulatory risk matrix and mitigation options by jurisdiction, including play-forces where enforcement has already shifted market mechanics.
-
Primary-sourced consumer and agent surveys, plus transaction-level analytics that highlight where fee leakage occurs and how to capture recurring revenues.
Note: this preview intentionally omits the granular market splits by region, property type and service line. Those core segment tables and the transaction-level datasets are available only in the full report and the accompanying data pack.
Competitive landscape — profiles and strategic postures
The market remains fragmented at the global scale, with a mix of legacy franchise networks, tech-first virtual brokerages, and full-service consultancies. Among notable players:
-
Large franchise networks (example profile). Established franchises maintain extensive agent networks and strong brand recognition across multiple territories. Their strategic choices focus on standardising service quality, improving agent retention and selectively adopting capex-light digital capabilities.
-
Agent-centric, co-operative models. Firms adopting agent-owned economics compete on proposition flexibility and recruitment appeal. Their success depends on balancing generous agent splits with centralised marketing and technology provision to avoid margin erosion.
-
Virtual/transactional brokerages. Purely virtual platforms concentrate on low per-transaction fees and streamlined processes. They gain share where cost-sensitive consumers prioritise price over full-service advisory.
-
Consultancy-style firms. Specialist consultancies and high-end agencies defend premium fee bands by focusing on luxury and complex transactions where advisory value is tangible.
Our full report contains company-level strategic heatmaps and investment profiles for leading firms, illustrating where each player is likely to expand, retrench or double-down through 2026.
Actionable priorities for executives in 2026
For leaders preparing 2026 plans, we recommend a three-tier programme of work that can be completed within a standard financial planning cycle:
-
90-day diagnostic. Rapid review of current pricing, agent economics and digital capability gaps. Deliverable: prioritized list of low-effort, high-impact changes (e.g., contract templates, fee disclosure updates, targeted automation pilots).
-
6–9 month transformation sprint. Implement revised pricing architecture, launch pilot alternative service tiers, and roll out at least one back-office automation to reduce cost-per-transaction. Deliverable: a repeatable, measurable improvement in gross margin per transaction.
-
18–24 month strategic positioning. Build or acquire platform capabilities to lock-in recurring revenues (property management, leasing services, digital valuation tools) and revise M&A criteria to prioritise capability over scale alone. Deliverable: a defensible multiyear revenue mix that mitigates single-channel fee pressure.
Governance: monitoring and KPIs
We advise boards to require a small set of leading indicators to monitor execution: effective fee rate (net of rebates), average time-to-close, agent productivity (transactions per agent per year), churned-agent rate, and share of recurring revenue. Quarterly reviews should include scenario updates reflecting regulatory shifts and consumer pricing experiments.
Conclusion and call to action
The global estate agent fees market offers steady aggregate growth but increasing structural complexity. 2026 will reward organisations that move quickly to unbundle legacy commission models, redesign agent economics for a hybrid physical-digital world, and capture recurring revenue streams that are less exposed to transactional compression.
PW Consulting’s full Worldwide Estate Agent Fees Market report provides the granular segmentation, regional models, pricing matrices and executable playbooks required to make those choices with confidence. For boards and investors planning 2026 strategies, the full dataset and our workshop packages illuminate where to reduce risk, where to invest and how to structure deals that align incentives across the value chain.
To access the complete report, data appendices and bespoke advisory options, please visit the PW Consulting research portal or contact our Industry Practice team for a briefing and demo of the downloadable financial models.
For detailed analysis of this topic, please visit the official page: Worldwide Estate Agent Fees Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Robotic Scope Holder Market to Expand at 7.5% CAGR, Reaching USD 514.3 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Robotic Scope Holder Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases an executive preview of our forthcoming Worldwide Robotic Scope Holder Market report. Built on a base year of 2025 with a historical lens across 2020–2025 and a forward-looking forecast to 2032, this study synthesizes commercial, clinical, regulatory and technology signals that will shape procurement, R&D and M&A choices in 2026 and beyond. The global market for robotic scope holders has demonstrated steady expansion—rising from USD 215.94 Million in 2020 to USD 310.0 Million in 2025—and PW Consulting projects continued momentum with a compound annual growth rate of 7.5% over the 2026–2032 forecast window to reach an expected USD 514.3 Million by 2032. This preview outlines why those topline dynamics matter, the actionable frameworks our full report delivers, and a compact competitive read on the leading players influencing the space.
Worldwide Robotic Scope Holder Market
What the full report delivers (practical, actionable content)
- Rigorous market sizing and scenario-driven forecasts (base year 2025; historical 2020–2025; forecast 2026–2032, USD Million), including sensitivity analyses that isolate demand shocks, reimbursement shifts and supply constraints.
- Go-to-market playbooks for suppliers and hospitals: channel strategies, service and consumable monetization, direct vs distributor models, and field service economics for high-uptime operating-room devices.
- Regulatory and reimbursement roadmaps tailored to product and market-entry strategies—covering electrical safety standards, 510(k) pathways and CPT-level reimbursement levers relevant to scope positioning systems.
- Technology and integration matrices: interoperability requirements with surgical robots and endoscope platforms, AI-enabled positioning roadmaps, and sterilization/material constraints affecting product design and lifecycle cost.
- Buyer decision frameworks and procurement templates: clinical value dossiers, ROI calculations for hospital administrators, and pilot-program design for rapid adoption in high-volume laparoscopic centers.
- Competitive intelligence and supplier scorecards: product capability benchmarking, channel strength, geographic reach and strategic M&A targets—ranked to help prioritize partnership or acquisition targets.
- Case studies and clinical-value evidence snapshots showing typical OR time savings, staff reallocation, and infection-control benefits observed in early-adopter institutions.
Why this matters for 2026 strategic planning
After a robust recovery and expansion phase in the first half of the decade, the robotic scope holder market is entering a commercialization phase where product differentiation, interoperability and service economics will determine commercial winners. With an overall market expanding from USD 215.94 Million in 2020 to USD 310.0 Million in 2025 and projecting to exceed half a billion USD by 2032 at a 7.5% CAGR, enterprises must decide in 2026 whether to: (a) accelerate investment to capture share in the next growth wave, (b) form partnerships to extend product ecosystems into hybrid robotic procedures, or (c) pursue a defensive consolidation strategy to protect installed-base revenue.
Worldwide Robotic Scope Holder Market
The market’s structural features—moderate-to-high concentration among a small group of committed suppliers—create both entry barriers and M&A opportunities. Our concentration analysis shows that the top three providers control a meaningful portion of the market, with the top five further amplifying consolidation incentives. For manufacturers and private equity investors, this means well-executed bolt-on acquisitions, or differentiated niche plays (e.g., AI-assisted positioning, service-led revenue models), can rapidly improve profitability and scale.
Worldwide Robotic Scope Holder Market
Competitive landscape — a tactical snapshot
- Mitaka Kohki (Tokyo, Japan) — Known for clinical-grade robotic holders such as the MS-51 and MS-6A, Mitaka combines multi-axis mechanics with voice control and is actively integrating with larger robotic platforms. A recent product update announced in October 2024 emphasized AI-assisted positioning enhancements intended to speed intraoperative set-up and improve targeting precision—an area where clinical evidence and software validation will differentiate leaders.
- FreeHand Surgical (London, UK) — The company’s FreeHand 2.0 unit emphasizes voice-activated control and OR ergonomics. With regulatory clearances supporting global use and high-visibility demonstrations (notably at SAGES in March 2024), FreeHand is positioning itself around ease-of-use and hybrid-procedure integration—key selling points for ambulatory surgery centers and tertiary hospitals seeking predictable OR throughput gains.
- EndoControl / Medtronic (Rennes, France; now part of Medtronic) — The ViKY system, acquired in 2014 and supported through Medtronic’s global distribution, benefits from broader device integration and scale. Notably, expanded 510(k) clearances reported in late 2023 have improved compatibility with next-generation endoscopes and lowered friction for hospital integration projects.
- Olympus (Tokyo, Japan) — Leveraging its endoscope and imaging platforms, Olympus offers robotic positioning complements that integrate with their VISERA ELITE systems. For OEMs and hospital systems, vendor-aligned ecosystems remain attractive because they reduce integration risk and support bundled-service economics.
Collectively, these players illustrate two competing strategic models: platform-led incumbents that bundle hardware, service and consumables versus specialist innovators that compete on focused features (voice control, AI positioning, OR ergonomics). In 2026, buyers will reward proven integration with existing OR ecosystems, validated clinical outcomes, and flexible procurement models.
Regulatory, reimbursement and materials dynamics
- Electrical safety and OR compliance: Robotic scope holders must conform to IEC 60601-1 and associated IEC collateral standards to ensure safe operation in clinical environments. These standards affect design choices and lead times for verification and validation activities.
- Reimbursement pathways and clinical coding: In markets where procedure coding exists for computer-assisted positioning, such as CPT-coded pathways covering scope navigation adjuncts, the ability to demonstrate quantifiable OR time savings and clinical benefit materially improves hospital procurement economics.
- Materials and sterilization: Typical designs employ medical-grade stainless steels and titanium alloys and require autoclave-compatible architectures validated to withstand repeated sterilization cycles. Material choices drive lifecycle costs, service intervals and total cost of ownership models hospitals use in procurement.
- Regulatory classification and safety history: These devices are generally regulated under Class II pathways in major markets, often requiring 510(k)-style filings in the U.S. The field has shown a good safety record with no prominent recalls for major models since 2020—an important trust signal for hospital risk committees.
Strategic imperatives for suppliers, investors and health systems in 2026
- Prioritize interoperability: Ensure compatibility with major endoscope and robotic platforms. Integration agreements and supported interfaces are short-term enablers of scale.
- Shift to outcome-based evidence generation: Invest in multi-center pilots that quantify OR time savings, staffing efficiencies and patient safety benefits—data that unlocks procurement approvals and reimbursement discussions.
- Design for the service economy: Field service, predictive maintenance and subscription-based models can turn hardware into recurring revenue streams and improve lifetime margins.
- Optimize regulatory and clinical timelines: Early engagement with regulatory bodies and health technology assessment teams reduces time-to-market risk; plan 510(k) strategies with enough clinical evidence to broaden labels and hospital uptake.
- Pursue targeted consolidation: For acquirers, the near-term focus should be bolt-ons that extend product portfolios into AI-enabled positioning or strengthen service networks in priority geographies.
What we intentionally withhold (and why)
True to the “trailer” principle behind this preview, we have presented high-confidence market trajectories, structural insights and competitive signals while withholding the granular segmentation tables and line-by-line regional and application forecasts that drive specific go-to-market and M&A models. Those detailed regional splits, product-level revenue breakdowns and per-application forecasts—together with supplier scorecards, full financial models, and downloadable slide decks—are available in the complete PW Consulting report and accompanying data workbook. This approach preserves the strategic value of the dataset for subscribers while providing executives a clear and actionable assessment of where to focus 2026 plans.
Next steps for senior leaders
Executives preparing budgets and investment priorities for 2026 should use this preview as a trigger to: (1) validate product roadmaps against interoperability and sterilization constraints; (2) allocate modest budgets for evidence-generation pilots in target hospitals; (3) map potential partners and acquisition targets against our supplier scorecard; and (4) update procurement models to capture service and consumable revenue potential. For investors, the period through 2027 will determine which platform players can convert clinical acceptance into predictable, recurring revenues.
To obtain the full dataset, comprehensive segmentation, supplier scorecards and the downloadable financial model behind these conclusions, please visit PW Consulting’s report page or contact our Client Services team for an executive briefing and licensing options. PW Consulting’s Worldwide Robotic Scope Holder Market report is purpose-built to convert market intelligence into executable strategies for 2026—and to help leaders prioritize where to invest, partner and accelerate adoption in the OR of the future.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cold Ramming Paste Market to Top USD 640.9 Million by 2032, Expanding at 4.0% CAGR as Asia‑Pacific and Anthracite‑Based CRP Drive Demand
By pmarketresearch, 2026-07-15
Worldwide Cold Ramming Paste (CRP) Market: Strategic Imperatives for 2026 — PW Consulting Preview
As industrial operators and upstream suppliers prepare their 2026 strategies, PW Consulting’s forthcoming Worldwide Cold Ramming Paste (CRP) Market report offers timely, action-oriented intelligence. Our analysis traces the market’s evolution from a post-2020 recovery phase through the 2025 base year and projects forward across 2026–2032, delivering a fact-based foundation for capital allocation, supplier strategy, and regulatory risk mitigation.
Worldwide Cold Ramming Paste (CRP) Market
Executive snapshot
The CRP market has demonstrated resilient expansion since 2020, rising from USD 385.4 Million in 2020 to USD 487.04 Million in the 2025 base year. Our forecast models—incorporating demand drivers, raw material cost trajectories, and regulatory scenarios—project steady growth through 2032, with the total market approaching USD 640.9 Million by the end of the forecast window. This implies an expected compound annual growth rate (CAGR) of approximately 4.0% for the forecast period (2026–2032).
Worldwide Cold Ramming Paste (CRP) Market
Why this matters for 2026 decision-makers
- Investment timing: The market’s steady CAGR signals that selective capacity investments and targeted process upgrades can yield consistent returns, but timing must be aligned with supply-chain dynamics and technology transitions described below.
- Supplier strategy: The market presents a semi-concentrated supplier landscape. The three largest players account for a meaningful share of capacity (our CR3 measure), and the top five further consolidate control—an important consideration for procurement negotiation levers and dual-sourcing plans.
- Regulatory and ESG alignment: Shifts in binder technology and PAH-related controls are reshaping product specifications. Organizations that proactively adopt low- or zero-PAH CRP formulations will minimize compliance risk and protect smelter operational continuity.
Market trajectory and volatility drivers
Behind the headline growth are several compounding drivers and punctuated risks. Aluminum smelting activities and furnace maintenance cycles underpin base-level CRP demand, while commodity cycles—especially anthracite and pitch feedstocks—introduce short-term volatility. Our historical reconstruction (2020–2025) captures pandemic impacts, post-pandemic restarts, and 2024–2025 supply realignments, which inform our 2026 scenario planning.
Worldwide Cold Ramming Paste (CRP) Market
On the forecast horizon, incremental gains are expected from process optimization at smelting plants, modest capacity additions among incumbent suppliers, and progressive substitution of alternative binders in regulated jurisdictions. These forces translate into steady volume expansion coupled with periodic price sensitivity tied to feedstock swings.
Raw materials, formulations, and regulatory dynamics
- Feedstock fundamentals: CRP formulations continue to rely on calcined anthracite, artificial graphite, and traditional pitch binders. These materials determine thermal stability, electrical resistivity, and mechanical integrity in cathode and furnace linings.
- Binder evolution: Coal tar pitch—historically dominant—remains technically effective but is increasingly scrutinized due to polycyclic aromatic hydrocarbons (PAHs). Over the last decade, industry players and select smelters have accelerated adoption of alternatives (furan resins, lignin-based binders, treated pitches) to meet occupational health and environmental requirements.
- Regulatory pressure and innovation: Case studies and vendor trials demonstrate viable low- or zero-PAH CRP variants. These alternatives are no longer purely niche: they are a strategic necessity in jurisdictions with strict emissions and worker-safety regimes. Companies that integrate eco-friendly chemistry into product lines will gain market access and reduce lifecycle liabilities.
Competitive landscape — who to watch
The CRP supplier field mixes multi-national materials groups, regional specialists, and technology-focused innovators. Key company archetypes and strategic positions include:
- Global materials integrators with vertically integrated upstream operations and global distribution footprints. These players can leverage R&D and cross-border manufacturing to supply standardized CRP and specialized cathode variants.
- Regional manufacturers with localized feedstock advantage and competitive cost structures. Many of these suppliers serve nearby smelter clusters and offer rapid technical support for lining repairs and retrofit projects.
- Specialty innovators introducing eco-friendly and low-emission CRP formulations. While often smaller in scale, these companies can command strategic premium positioning by addressing PAH and other environmental constraints.
Representative firms exemplifying these archetypes include long-established multinational producers supplying cathode ramming paste variants tailored to aluminum electrolysis cells, regional manufacturers with deep technical experience in high-temperature environments, and niche developers of zero-PAH products that have been validated at industrial sites. Our full report assesses these firms across production footprint, product portfolio, R&D investments, and commercial channels—delivering a supplier scorecard essential for procurement and M&A screening.
Market concentration and strategic implications
Concentration metrics indicate a market in which a limited set of suppliers command a significant portion of capacity—our CR3 and CR5 measures show meaningful aggregate shares. For buyers, this concentration translates into two practical implications: first, the need for robust dual- or multi-sourcing strategies to mitigate single-supplier exposure; second, the opportunity to leverage scale by partnering with lead suppliers for co-development of low-emission CRP formulations.
Operational and commercial playbook for 2026
For operating companies, smelters, and midstream suppliers, the path to resilient 2026 operations should include:
- Technical validation: Run pilot trials of low-PAH and alternative-binder CRPs during scheduled maintenance windows to verify thermal, electrical, and mechanical performance under plant-specific conditions.
- Supply-security audits: Map current single points of failure in CRP supply and create contingency contracts that balance cost with delivery reliability.
- Lifecycle cost modeling: Move beyond unit price to incorporate occupational safety costs, potential emission-control capex, and downstream yield impacts when comparing CRP formulations.
- Strategic partnerships: Consider co-development agreements with suppliers that have proven eco-friendly tech or with regional producers positioned for expansion—especially where proximity to anthracite or specialized graphite sources confers logistics advantage.
Report composition — practical contents that guide action
PW Consulting’s full report (base year 2025; historical 2020–2025; forecast 2026–2032) is built for practitioners. Highlights include:
- Top-down and bottom-up market sizing with sensitivity scenarios that stress-test demand under multiple commodity and regulatory pathways.
- Supply-side mapping: production footprints, capacity estimates, and a supplier benchmarking toolkit that ranks vendors on technical breadth, environmental credentials, and commercial reach.
- Feedstock cost scenarios and stress-tests: modeled impacts of anthracite and pitch price swings on CRP margins and smelter operating costs.
- Regulatory impact analysis: jurisdictional heatmaps for PAH and VOC-related rules, and an emissions-compliance roadmap for transitioning to alternative binders.
- Commercial playbooks: procurement strategies, contractual templates for co-development, and pricing indices for index-linked supply agreements.
- M&A and partnership pipeline: screened target lists and valuation frameworks for bolt-on acquisitions or strategic JV formations (designed for acquirers seeking rapid entry into eco-friendly CRP production).
- Excel model deliverable: configurable demand and revenue model enabling users to run custom scenarios for budgeting and strategic planning.
How to use this intelligence in Q1–Q2 2026 planning cycles
Leaders should treat the report as a decision-grade toolkit. Specific short-term actions we recommend for Q1–Q2 2026 include:
- Finalize pilot schedules with two alternate CRP formulations (conventional and low-PAH) to inform procurement specs for the coming maintenance season.
- Run a supplier risk heatmap, using our benchmark outputs, to identify one incumbent supplier for expansion and one alternative supplier for contingency supply.
- Model the impact of alternative-binder adoption on total cost of ownership (TCO) across a five-year window, including potential capex offsets from lower emissions-control investments.
Concluding perspective
The CRP market’s mid-single-digit CAGR and semi-concentrated supplier structure create a predictable yet strategically rich environment. Firms that combine operational discipline with proactive supplier engagement and early adoption of low-emission chemistries will both reduce regulatory exposure and unlock incremental value. PW Consulting’s full Worldwide Cold Ramming Paste report translates this dynamic landscape into concrete, executable steps—backed by scenario-tested numbers, supplier scorecards, and tactical playbooks.
For procurement leads, plant managers, and corporate strategists planning for 2026, this is not a market to treat as a commodity. It is a technical material whose choice reverberates through safety, compliance, thermal performance, and bottom-line economics. Our full report provides the granular segmentation, regional analysis, and supplier-specific intelligence you will need to act confidently; visit our report page to access the complete study and downloadable models.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Concrete Densification Polishing Material Market Poised to Expand at a 6.15% CAGR Through 2032
By pmarketresearch, 2026-07-15
PW Consulting: Strategic Brief — Worldwide Concrete Densification & Polishing Material Market (2026 Outlook)
PW Consulting today publishes a strategic briefing to accompany our new Worldwide Concrete Densification Polishing Material Market report (base year 2025, forecast 2026–2032). The study synthesizes five years of historical market dynamics (2020–2025) with a finely grained forward view anchored to a 6.15% CAGR through the forecast window. The global market has expanded from roughly USD 736 million in 2020 to about USD 985 million in 2025 and is projected to continue that trajectory into the next decade under multiple demand and cost scenarios.
Worldwide Concrete Densification Polishing Material Market
Why this matters for 2026 corporate decision-making
- Budgeting with confidence: Our top‑line trajectory and scenario work translate a steady mid-single-digit growth path into practical implications for procurement, inventory and capex planning in 2026.
- Input-cost realism: Raw-material volatility has clear pass-through effects on margins and tender pricing; companies that incorporate near-term commodity scenarios into pricing and contract design will protect margins.
- Sustainability is now a procurement lever: Environmental Product Declarations (EPDs) and alignment with LEED v5/GWP crediting are reshaping specification behavior in construction procurement chains. Vendors with certified EPDs secure preference in low-carbon projects.
- Fragmentation creates M&A and partnership opportunities: The market is structurally fragmented (three‑firm and five‑firm concentration remain low relative to legacy chemical sectors), creating scope for roll‑ups, distribution partnerships and local scale plays.
- Technology and specification risk: Emerging chemistries and system approaches (colloidal silica, silica‑free densifiers, blended product systems, integrated polishing services) are shifting the basis of competition from price-alone to performance, safety and life-cycle carbon.
What the report delivers — practical, executable content
Our aim was pragmatic: provide materials that commercial, procurement and R&D teams can use immediately. The full report package includes:
Worldwide Concrete Densification Polishing Material Market
- Market sizing and a transparent forecasting engine for 2026–2032 with scenario toggles for energy and raw-material shocks.
- Demand-driver analytics tied to construction segments, lifecycle requirements, and polished-concrete adoption curves.
- Cost-model templates that translate soda ash, silica sand and sodium silicate price movements into margin pressure maps for manufacturers and distributors.
- Competitive mapping with strategic profiles, capability matrices and go‑to‑market archetypes for the leading suppliers and disruptive entrants.
- Commercial playbooks: specification language, tender strategies, distributor compensation models and pilot implementation checklists to win low-carbon and high‑performance projects.
- Supplier risk assessments, hedging approaches and a short-list of practical mitigation actions for 12–24 month horizons.
- Downloadable financial models and procurement templates designed for direct integration into corporate planning systems.
To preserve commercial value and drive direct engagement, the report intentionally withholds the full set of granular regional and application share tables in this press release. Full segment detail, company revenue shares and downloadable spreadsheets are available in the source report and on our materials portal.
Worldwide Concrete Densification Polishing Material Market
Competitive landscape — strategic takeaways
The competitive map blends long‑standing brand owners, chemical incumbents and innovation-led challengers. Several patterns matter for 2026:
- Heritage brands with system plays: Companies such as Curecrete Distribution (originator of the Ashford Formula) and The Euclid Chemical Company maintain strong recognition among contractors and architects through multi-decade presence and system-based product offerings tied to polishing workflows.
- Multinational chemical players: Sika and others leverage global formulation capability and channel breadth to serve large construction projects and specification-led procurement, where consistency and certification matter.
- Premium performance and sustainability leaders: Vendors like PROSOCO and Ecolab are pushing certification and product declarations as entry ballots into low‑carbon tenders; for example, PROSOCO’s January 2026 release of Environmental Product Declarations for multiple densifiers is a concrete signal that EPDs have moved from optional to strategic.
- Innovation disruptors: Niche and technology-focused firms such as Adhesives Technology Corporation/Convergent (STRiON:Fortify, a silica‑free spray‑on densifier) and colloidal-silica specialists are changing the product playbook by addressing applicator safety, cure time and long‑term hardness.
- Equipment + chemistry bundles: Several players align densifiers with polishing systems (including grinding and chemical finishing) to capture higher parts of the value chain and lock in recurring consumable demand.
These dynamics, coupled with relatively low CR3 (~21.5%) and CR5 (~33.8%) concentration metrics, point to a market where local reach, technical service and certification advantages can outweigh pure price competition.
Supply-side realities: raw materials, logistics and margin impact
Input-cost dynamics are a top pivot for 2026 planning. Sodium silicate — a widely used feedstock for many silicate-based densifiers — demonstrates regional price dispersion that matters for manufacturing footprint and sourcing decisions. February 2026 benchmark prices showed notable variation across major producing regions (for example, Northeast Asia, Europe, India and North America), and the industry remains sensitive to soda ash and energy cost swings following the 2024–2025 period of volatility. Colloidal silica supply chains are similarly tied to sodium silicate and acid availability, and historical episodes have driven double-digit annual cost jumps in short windows.
Implications:
- Manufacturers with flexible procurement and regional blending/neutralization capacity can protect margins.
- Longer supplier contracts and commodity hedging strategies are now routine recommendations for 12–24 month planning horizons.
- Localizing critical feedstock processing or securing toll‑manufacturing arrangements reduces exposure to freight and energy spikes in high‑cost regions.
Regulation, sustainability and procurement
Regulatory and voluntary sustainability frameworks are altering specification rules within commercial, institutional and infrastructure projects. EPDs now map cleanly to LEED v5 and GWP optimization credits, creating immediate procurement lift for densifiers and polishing systems that can demonstrate lower embodied carbon. The PROSOCO EPD release in January 2026 is the most visible early-mover example; expect more manufacturers to follow suit during 2026 as sustainability criteria become table stakes in major tenders.
Recommendations for corporate leaders in 2026
- Fast-track certification: prioritize EPDs and third‑party validation for core products planned for use in large‑scale or public projects.
- Recalibrate product mix: balance legacy silicate formulations with colloidal-silica and silica‑free innovations to meet applicator safety, finish performance and sustainability demands.
- Protect margins via procurement design: implement multi-sourced contracts, indexed pricing clauses, and selective inventory resilience for key feedstocks.
- Commercialize services: bundle specification support, applicator training and warranty programs to differentiate from commoditized offerings.
- Scan the M&A landscape: prioritize targets that add geographies, distribution density or specialized chemistries; the market’s fragmentation creates arbitrage for consolidators.
- Operationalize the forecast: translate our scenario models directly into the annual budgeting process and update rolling forecasts at least quarterly.
How to use our full report
This briefing should be read as a strategic primer. The full PW Consulting report contains the granular build-ups — regional and application-level tables, product-type demand curves, competitor revenue matrices, and an interactive Excel model you can import into your planning systems. For procurement teams, the report’s supplier scorecards and tender‑ready specification language are designed for direct adoption. For product and R&D leaders, the dossier on chemistries and life‑cycle carbon impact offers prioritized R&D bets for 2026.
To access the complete dataset, downloadable models and the full strategic playbook, visit our report page. PW Consulting clients and subscribers may also request a tailored briefing workshop to translate findings into a 90‑day action plan.
Closing
Concrete densification and polishing materials are transitioning from a largely product‑led market to a solutions and sustainability‑led ecosystem. As 2026 procurement cycles open, companies that combine certification, cost discipline and service‑based commercial models will capture outsized share of the forecast growth. PW Consulting’s report equips leaders with the scenarios, tools and tactical templates to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Concrete Densification Polishing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com