

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Concrete Densification Polishing Material Market Poised to Expand at a 6.15% CAGR Through 2032

PW Consulting: Strategic Brief — Worldwide Concrete Densification & Polishing Material Market (2026 Outlook)
PW Consulting today publishes a strategic briefing to accompany our new Worldwide Concrete Densification Polishing Material Market report (base year 2025, forecast 2026–2032). The study synthesizes five years of historical market dynamics (2020–2025) with a finely grained forward view anchored to a 6.15% CAGR through the forecast window. The global market has expanded from roughly USD 736 million in 2020 to about USD 985 million in 2025 and is projected to continue that trajectory into the next decade under multiple demand and cost scenarios.
Worldwide Concrete Densification Polishing Material Market
Why this matters for 2026 corporate decision-making
- Budgeting with confidence: Our top‑line trajectory and scenario work translate a steady mid-single-digit growth path into practical implications for procurement, inventory and capex planning in 2026.
- Input-cost realism: Raw-material volatility has clear pass-through effects on margins and tender pricing; companies that incorporate near-term commodity scenarios into pricing and contract design will protect margins.
- Sustainability is now a procurement lever: Environmental Product Declarations (EPDs) and alignment with LEED v5/GWP crediting are reshaping specification behavior in construction procurement chains. Vendors with certified EPDs secure preference in low-carbon projects.
- Fragmentation creates M&A and partnership opportunities: The market is structurally fragmented (three‑firm and five‑firm concentration remain low relative to legacy chemical sectors), creating scope for roll‑ups, distribution partnerships and local scale plays.
- Technology and specification risk: Emerging chemistries and system approaches (colloidal silica, silica‑free densifiers, blended product systems, integrated polishing services) are shifting the basis of competition from price-alone to performance, safety and life-cycle carbon.
What the report delivers — practical, executable content
Our aim was pragmatic: provide materials that commercial, procurement and R&D teams can use immediately. The full report package includes:
Worldwide Concrete Densification Polishing Material Market
- Market sizing and a transparent forecasting engine for 2026–2032 with scenario toggles for energy and raw-material shocks.
- Demand-driver analytics tied to construction segments, lifecycle requirements, and polished-concrete adoption curves.
- Cost-model templates that translate soda ash, silica sand and sodium silicate price movements into margin pressure maps for manufacturers and distributors.
- Competitive mapping with strategic profiles, capability matrices and go‑to‑market archetypes for the leading suppliers and disruptive entrants.
- Commercial playbooks: specification language, tender strategies, distributor compensation models and pilot implementation checklists to win low-carbon and high‑performance projects.
- Supplier risk assessments, hedging approaches and a short-list of practical mitigation actions for 12–24 month horizons.
- Downloadable financial models and procurement templates designed for direct integration into corporate planning systems.
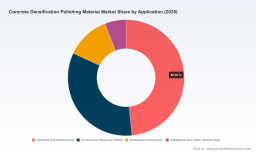
To preserve commercial value and drive direct engagement, the report intentionally withholds the full set of granular regional and application share tables in this press release. Full segment detail, company revenue shares and downloadable spreadsheets are available in the source report and on our materials portal.
Worldwide Concrete Densification Polishing Material Market
Competitive landscape — strategic takeaways
The competitive map blends long‑standing brand owners, chemical incumbents and innovation-led challengers. Several patterns matter for 2026:
- Heritage brands with system plays: Companies such as Curecrete Distribution (originator of the Ashford Formula) and The Euclid Chemical Company maintain strong recognition among contractors and architects through multi-decade presence and system-based product offerings tied to polishing workflows.
- Multinational chemical players: Sika and others leverage global formulation capability and channel breadth to serve large construction projects and specification-led procurement, where consistency and certification matter.
- Premium performance and sustainability leaders: Vendors like PROSOCO and Ecolab are pushing certification and product declarations as entry ballots into low‑carbon tenders; for example, PROSOCO’s January 2026 release of Environmental Product Declarations for multiple densifiers is a concrete signal that EPDs have moved from optional to strategic.
- Innovation disruptors: Niche and technology-focused firms such as Adhesives Technology Corporation/Convergent (STRiON:Fortify, a silica‑free spray‑on densifier) and colloidal-silica specialists are changing the product playbook by addressing applicator safety, cure time and long‑term hardness.
- Equipment + chemistry bundles: Several players align densifiers with polishing systems (including grinding and chemical finishing) to capture higher parts of the value chain and lock in recurring consumable demand.
These dynamics, coupled with relatively low CR3 (~21.5%) and CR5 (~33.8%) concentration metrics, point to a market where local reach, technical service and certification advantages can outweigh pure price competition.
Supply-side realities: raw materials, logistics and margin impact
Input-cost dynamics are a top pivot for 2026 planning. Sodium silicate — a widely used feedstock for many silicate-based densifiers — demonstrates regional price dispersion that matters for manufacturing footprint and sourcing decisions. February 2026 benchmark prices showed notable variation across major producing regions (for example, Northeast Asia, Europe, India and North America), and the industry remains sensitive to soda ash and energy cost swings following the 2024–2025 period of volatility. Colloidal silica supply chains are similarly tied to sodium silicate and acid availability, and historical episodes have driven double-digit annual cost jumps in short windows.
Implications:
- Manufacturers with flexible procurement and regional blending/neutralization capacity can protect margins.
- Longer supplier contracts and commodity hedging strategies are now routine recommendations for 12–24 month planning horizons.
- Localizing critical feedstock processing or securing toll‑manufacturing arrangements reduces exposure to freight and energy spikes in high‑cost regions.
Regulation, sustainability and procurement
Regulatory and voluntary sustainability frameworks are altering specification rules within commercial, institutional and infrastructure projects. EPDs now map cleanly to LEED v5 and GWP optimization credits, creating immediate procurement lift for densifiers and polishing systems that can demonstrate lower embodied carbon. The PROSOCO EPD release in January 2026 is the most visible early-mover example; expect more manufacturers to follow suit during 2026 as sustainability criteria become table stakes in major tenders.
Recommendations for corporate leaders in 2026
- Fast-track certification: prioritize EPDs and third‑party validation for core products planned for use in large‑scale or public projects.
- Recalibrate product mix: balance legacy silicate formulations with colloidal-silica and silica‑free innovations to meet applicator safety, finish performance and sustainability demands.
- Protect margins via procurement design: implement multi-sourced contracts, indexed pricing clauses, and selective inventory resilience for key feedstocks.
- Commercialize services: bundle specification support, applicator training and warranty programs to differentiate from commoditized offerings.
- Scan the M&A landscape: prioritize targets that add geographies, distribution density or specialized chemistries; the market’s fragmentation creates arbitrage for consolidators.
- Operationalize the forecast: translate our scenario models directly into the annual budgeting process and update rolling forecasts at least quarterly.
How to use our full report
This briefing should be read as a strategic primer. The full PW Consulting report contains the granular build-ups — regional and application-level tables, product-type demand curves, competitor revenue matrices, and an interactive Excel model you can import into your planning systems. For procurement teams, the report’s supplier scorecards and tender‑ready specification language are designed for direct adoption. For product and R&D leaders, the dossier on chemistries and life‑cycle carbon impact offers prioritized R&D bets for 2026.
To access the complete dataset, downloadable models and the full strategic playbook, visit our report page. PW Consulting clients and subscribers may also request a tailored briefing workshop to translate findings into a 90‑day action plan.
Closing
Concrete densification and polishing materials are transitioning from a largely product‑led market to a solutions and sustainability‑led ecosystem. As 2026 procurement cycles open, companies that combine certification, cost discipline and service‑based commercial models will capture outsized share of the forecast growth. PW Consulting’s report equips leaders with the scenarios, tools and tactical templates to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Concrete Densification Polishing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com