

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Optoelectronic Safety Laser Scanner Market Poised for 7.15% CAGR in 2026–2032

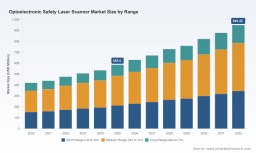
Worldwide Optoelectronic Safety Laser Scanner Market: Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s latest market study on the worldwide optoelectronic safety laser scanner market delivers a focused, decision‑centric view designed for executives planning product, procurement, and M&A moves in 2026. The market has expanded steadily from a base of approximately USD 420 million in 2020 to roughly USD 585 million in 2025, and our modelling shows continued momentum into the coming decade — with a compound annual growth rate of 7.15% across the 2026–2032 forecast window and an expected market size approaching USD 950 million by 2032. This briefing highlights the structural forces, competitive dynamics, and practical playbooks that will determine winners and laggards next year, while reserving the detailed segment-level datapoints to the full report to protect the value of our proprietary modelling.
Worldwide Optoelectronic Safety Laser Scanner Market
Why 2026 is a pivotal planning year
-
Technology transition: Component and sensor innovation is shifting the product set from classic 2D Type‑3 scanners to higher-capability 3D and multi‑echo LiDAR solutions that broaden safe‑perception envelopes for mobile and outdoor applications.
Worldwide Optoelectronic Safety Laser Scanner Market -
Standards and certification updates: Regulatory clarifications and standards revisions are reshaping installation practices and system architectures, prompting engineering teams to revalidate risk assessments and update safety calculators.
Worldwide Optoelectronic Safety Laser Scanner Market -
Supply‑chain stress: Concentration in upstream compound semiconductor supply and export policy shifts have increased lead times and price volatility for critical laser-diode wafers, forcing procurement and product‑planning tradeoffs that will reverberate through 2026.
Market trajectory in plain terms
Our historical time series shows steady, resilient growth: the global market rose from approximately USD 420 million in 2020 to about USD 585 million in 2025. Looking forward, the market is forecast to continue expanding at a mid‑single‑digit to high‑single‑digit pace (7.15% CAGR across 2026–2032), driven by accelerated adoption in automated material handling, expanded deployment in automotive and mobile robotics, and the increasing use of scanners as integrated perception elements in larger safety architectures.
Key structural dynamics
-
Consolidation and concentration: The market exhibits clear concentration at the top. The leading firms together hold a material share of the market, creating scale advantages in R&D, certification pathways, and global service footprints. This concentration favours firms that can pair product breadth with channel depth.
-
Component dependency risk: Laser diodes and compound semiconductor wafers remain critical bottlenecks. Prolonged lead times and price inflation in upstream materials — exacerbated by geopolitics and export controls — increase the value of supply diversification, contract hedging, and backward integration strategies.
-
Standards tightening: Updates to installation standards and safety distance calculations are raising the technical bar for compliant system design, making certified firmware, validated safety calculators, and interface flexibility (industrial safety protocols) decisive procurement criteria.
Competitive landscape — what to watch
The competitive field mixes longstanding safety specialists with automation and sensing incumbents. Across the vendor set, three strategic archetypes are emerging: platform incumbents with broad product portfolios and deep certification capabilities; focused sensor specialists targeting size, robustness, or cost niches; and system vendors integrating scanners into wider automation solutions.
-
SICK AG has broadened its roadmap into 3D perception for outdoor mobile applications, introducing high‑aperture, safety‑certified LiDAR systems aimed at cranes, AGVs and other outdoor mobile platforms. Their investments exemplify a move toward multi‑echo, high‑range devices with rugged housings — a direct play for higher‑duty, safety‑critical mobile use cases.
-
Leuze electronic is capitalizing on tight‑space integration and compact footprints with ultra‑small scanners tailored for AGVs and AMRs. The vendor’s focus on footprint, scan angle and integration-friendly form factors underscores a tactical approach to proliferating scanners into space‑constrained automation designs.
-
Pilz has advanced network integration and installer usability by adding industrial Ethernet interfaces and updating its safety‑calculation guidance to align with recent standards changes — a practical move that reduces system integration friction for plant engineering teams.
-
KEYENCE and several automation majors are differentiating on detection range, environmental resistance and network safety stacks, bundling device‑level perception with diagnostics and vision elements for premium applications.
-
North American and Japanese providers are leveraging strong machine‑tool and controls channel relationships to embed scanners into wider automation propositions, while European specialists continue to set pace on safety certification and functional‑safety documentation.
Recent product and regulatory signals that matter for 2026
-
New 3D LiDAR launches with PL‑level safety certifications are lowering the cost of adopting three‑dimensional perception in safety use cases, but they also introduce new validation and maintenance requirements for safety engineers.
-
Compact, high‑angle 2D scanners facilitate densification of perception on small stateful robots and constrained machinery, changing design rules for vehicle architects and machine builders.
At the same time, revisions to positioning standards (notably the 2024 update to device‑positioning guidance) materially affect how safety distances are calculated for orthogonal and parallel approaches and introduce new allowances for measurement uncertainty and wear. Procurement teams should insist on vendor documentation that is explicitly mapped to these updated standards.
Implications for buyer and vendor strategies in 2026
-
For buyers — resilience and specification clarity: Establish multi‑vendor sourcing lanes for critical sensor classes; require verifiable compliance artifacts mapped to the latest standards; and specify interface and diagnostics expectations (e.g., Profinet/Profisafe, CIP Safety, EtherNet/IP) to minimize integration rework. Adopt inventory and contractual hedges for laser diode supply to manage lead‑time and price volatility.
-
For vendors — differentiation through systemization: Prioritize product families that ease certification work for integrators (pre‑validated zone templates, safety calculation toolkits, and firmware update pathways). Consider software and services (remote diagnostics, lifecycle support) as margin levers. Targeted investment in ruggedized, outdoor‑rated LiDAR and compact form factors will unlock adjacent markets.
-
For investors and M&A strategists: The market’s measured concentration and technology bifurcation create opportunities for bolt‑on deals that expand sensing portfolios, accelerate time‑to‑market for 3D perception, or fill channel gaps in high‑growth end markets such as logistics mobility. Expect value creation from acquiring complementary software or systems capabilities rather than single‑product plays alone.
Operational playbooks — what PW Consulting recommends now
-
Run scenario planning that stress‑tests product roadmaps against 12–36 month upstream lead‑time shocks and price scenarios for compound semiconductor inputs.
-
Mandate standards traceability: require vendors to supply test reports, safety cases, and installation guidance explicitly referencing current editions of IEC 61496, ISO 13849 and related norms.
-
Quantify the total cost of ownership for sensor options by modelling installation, certification, downtime and maintenance costs — not just capex.
-
Accelerate firmware and field‑service capability development to reduce time‑to‑repair and improve in‑field safety compliance monitoring.
What the full PW Consulting report contains (select highlights)
Our flagship study provides a complete set of strategic deliverables for 2026 execution, including: multi‑year historicals and granular forecasts, competitive scorecards and capability maps, a vendor M&A matrix, product benchmarking across safety classes and environmental ratings, supply‑chain risk heatmaps, regulatory impact scenarios and practical go‑to‑market playbooks for suppliers and end‑users. Note: to preserve the proprietary value of our segment modelling and vendor scoring, detailed segment‑level revenues and regional breakdowns are reserved for report subscribers and are not published in this press preview.
Methodology and confidence
The report synthesizes primary interviews with industry leaders, certification bodies and integrators; bottom‑up product‑level bill‑of‑materials analysis; and supply‑chain mapping for semiconductor inputs. Our concentration metrics and market sizing reflect reconciled top‑down and bottom‑up approaches, and the analysis explicitly captures geopolitical and raw‑material tail risks that influence lead times and pricing. We judge the probability distribution around our base forecast to be moderate‑to‑high in the near term, with downside exposure concentrated in supply‑led scenarios and upside tied to accelerated adoption of 3D perception in outdoor and mobile segments.
Next steps for executives
-
Procurement chiefs should secure multi‑source contracts for laser‑diode dependent modules and revisit buffer policies now.
-
Product and R&D leaders should prioritize certification roadmaps and integration toolkits that reduce installer burden and time‑to‑compliance.
-
Strategy and corporate development leaders should evaluate bolt‑on acquisitions that add sensor modalities, ruggedization know‑how, or global service scale.
For a complete set of datasets, vendor profiles, actionable scenario analyses and the full segmentation model (range, end‑user, and regional splits), access the full Worldwide Optoelectronic Safety Laser Scanner Market report on the PW Consulting publications page. Our team is available to provide tailored briefings and bespoke scenario modelling to support 2026 decision cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com