

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts Worldwide Digital Cultural Tourism Market to Expand at a 17.6% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Digital Cultural Tourism Market — Strategic Imperatives for 2026
PW Consulting’s latest market study on the Worldwide Digital Cultural Tourism Market distills five years of historical performance and a seven-year forecast into an actionable strategic brief for leadership teams planning 2026 initiatives. The market has moved from early experimentation into scalable deployment: our base-year analysis shows the global market at approximately USD 26.45 billion in 2025, with a near-term uplift to an estimated USD 31.85 billion in 2026 and a compound annual growth rate (CAGR) of 17.6% across the forecast horizon. For executives, investors, cultural institutions, and public-sector planners, the report reframes digital cultural tourism not as a niche engagement channel but as a core line item of cultural preservation, audience development, and diversified revenue models.
Worldwide Digital Cultural Tourism Market
Why this report matters in 2026
- Strategic timing — 2026 sees accelerating public-private collaboration (notably new UNESCO/UN Tourism commitments) that will lower barriers for financed pilot projects and institutional partnerships.
- Technology convergence — high-resolution 3D capture, generative AI, cloud-based virtual exhibition infrastructure, and immersive UX are maturing in parallel, enabling repeatable deployments rather than bespoke proofs-of-concept.
- Policy momentum — regional standardization efforts for 3D data reuse and digital preservation are establishing interoperability baselines that change procurement, IP, and data governance considerations.
- Market scale — the global market trajectory and robust CAGR demonstrate that investment made this year can compound into meaningful audience, preservation, and commercial outcomes by the end of the decade.
What the report delivers — practical, executable intelligence
This study is intentionally operational. Rather than a high-level overview, the report provides the playbooks and templates needed to move from strategy to execution in 2026:
Worldwide Digital Cultural Tourism Market
- Executive dashboard: concise metrics tied to board-level KPIs (audience reach, preservation value, hybrid revenue potential).
- Market sizing & outlook: validated global market history and seven-year forecast, with scenario analysis to stress-test investment plans against downside and acceleration cases.
- Technology stack map: vendor-neutral architecture blueprints for digital platforms, immersive experiences, 3D scanning, AI-based content generation, and cloud orchestration.
- Procurement toolkit: RFP templates, scoring matrices, IP and data-rights clauses, and procurement risk checklists tailored for cultural institutions and destination management organizations (DMOs).
- Implementation playbooks: staged pilot templates, change-management frameworks, staff skilling plans, and sample timelines for medium and large-scale projects.
- Commercial models: revenue levers (sponsorship, freemium access, premium experiences, licensing), ROI frameworks, and sensitivity analyses suited for public–private partnerships.
- Policy & preservation guidance: regulatory considerations, interoperability priorities, and recommended governance structures for long-term stewardship of digital cultural assets.
- Vendor scorecards and case studies: comparative assessments and real-world implementation outcomes to accelerate vendor selection and partnership design.
To preserve commercial value and drive direct engagement, the report summarizes high-level segmentation and competitive dynamics while reserving granular sub-segment and region-level figures for the full report.
Worldwide Digital Cultural Tourism Market
Competitive landscape — who to watch and why
The vendor ecosystem spans global platform players, specialized immersive studios, 3D capture and digital-twin providers, and non-profit preservation specialists. Our competitive analysis profiles leading actors and situates their capabilities against likely client requirements in 2026.
- Google Arts & Culture — With an extensive partner network and platform-level distribution, Google’s offering remains the reference for scale and discoverability. Its strengths lie in reach, high-resolution imaging capabilities, and a consumer-friendly front end that institutional clients leverage for global exposure.
- YouVisit — Focused on interactive 360° experiences and layered media, YouVisit is notable for rapid content production and engagement-oriented storytelling. It is well-suited to destinations seeking high-volume, lower-cost interactive tours that integrate into marketing funnels.
- Matterport — The company’s 3D spatial scanning and digital-twin technology are de facto standards for accurate, navigable virtual representations. Matterport is a go-to for institutions that prioritize spatial fidelity, architectural documentation, and integration with facilities management systems.
- Global Mofy AI Limited — A generative-AI and 3D asset provider that has moved rapidly into full-scale immersive exhibitions. Recent deployments demonstrate commercial viability of themed, conservation-focused digital halls and provide a model for ecological and heritage interpretation projects.
- ARCTUR / 3D-4CH — The EU-focused initiative and its Online Competence Centre are accelerating pan-European interoperability and competence building. ARCTUR’s emphasis on tooling, training, and shared data infrastructures is changing the calculus for cross-border projects and grant-funded preservation programs.
- CyArk — As a specialized preservation and documentation non-profit, CyArk’s high-fidelity scanning workflows and archival practices remain critical where risk mitigation and conservation-grade records are the priority.
These actors occupy complementary positions in the ecosystem. Strategic buyers should evaluate combinations — for example, pairing high-fidelity capture (Matterport/CyArk) with distribution and engagement platforms (Google Arts & Culture/YouVisit) and AI-driven content enrichment (Global Mofy) — to build modular, scalable solutions.
Recent developments altering the decision landscape
- March 2026: UNESCO and UN Tourism formalized a partnership to promote sustainable, inclusive, and digitally-enabled access to cultural heritage. The agreement unlocks new funding streams and legitimizes virtual access as part of resilient tourism strategies.
- Early 2026: The EU 3D-4CH project launched an Online Competence Centre to standardize 3D data reuse and foster cross-border collaboration — a potential template for regional interoperability initiatives elsewhere.
- 2026: Vendor-led pilots demonstrate that cloud-hosted immersive halls and AI-driven content pipelines can be deployed at destination scale, with repeatable operational models for curation, rights management, and monetization.
Strategic recommendations for 2026 decision-makers
- Prioritize interoperability over proprietary lock-in. With standards and competence centers emerging, invest first in open, modular architectures that allow you to swap components as the market matures.
- Adopt a pilot-to-scale pathway. Run one or two high-visibility pilots that resolve procurement, IP, and staffing questions, then scale via templates and shared infrastructure rather than bespoke rebuilds.
- Combine preservation and commercial objectives. Frame digital initiatives as dual-purpose: heritage preservation and audience monetization. This alignment expands funding options (grants + commercial partners).
- Build partnerships with standards initiatives and multilateral programs. Engagement with UNESCO/UN Tourism and regional competence centers reduces risk and improves access to co-funding and technical assistance.
- Invest in people and processes. Content digitization and immersive experiences require cross-functional teams (curators, digital producers, data engineers, legal counsel). Allocate budget for sustained capability building, not one-off training.
- Measure what matters. Use a blended metric set that includes preservation integrity, accessibility, audience engagement, and diversified revenue — not just visitor counts.
Investment and risk outlook
The market’s growth trajectory offers significant upside, but investors and operators must manage execution risks. Our scenario models—built into the report—illustrate how variations in technology adoption, public funding, and regulatory harmonization affect returns. While headline growth supports continued capital allocation, the most attractive opportunities in 2026 will be those that combine proven tech stacks, policy alignment, and robust governance frameworks.
How to use this report
Whether you are a museum director, a destination manager, a technology vendor, or an investor, the report is structured to accelerate decision-making:
- Board briefings and investment memos — extract executive summaries and ROI slices for governance bodies.
- Procurement and partnerships — deploy RFP templates and vendor scorecards to secure the right partnerships quickly.
- Pilot planning — use staged templates to run fiscally responsible pilots that resolve technical and organizational uncertainty.
- Policy engagement — leverage regulatory analysis and recommended governance models to secure public support and funding.
Next steps
PW Consulting’s Worldwide Digital Cultural Tourism Market report arms leaders with the frameworks needed to act decisively in 2026. The document surfaces global market sizing, rigorous growth projections, technology and vendor assessments, and practical playbooks — while reserving detailed sub-segment and regional breakdowns to the full report to preserve actionable commercial intelligence.
For organizations preparing investment cases, drafting procurement documentation, or designing public–private cultural initiatives, this research is intended to shorten time-to-decision and de-risk early deployments. Visit the report landing page to access full data tables, segmented forecasts, and vendor scorecards — the granular intelligence that turns strategic intent into operational impact.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Cultural Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Multi‑Point Ground Flares Market to Expand from USD 346.48 Million in 2025 to USD 539.12 Million by 2032 at a 6.52% CAGR
By pmarketresearch, 2026-07-15
Worldwide Multi-Point Ground Flares (MPGF) Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Multi-Point Ground Flares (MPGF) synthesizes five years of historic market behaviour and a seven-year forecast to present an actionable strategic framework for companies operating across oil & gas, petrochemical, refining, and LNG infrastructure. Anchored on a 2025 base year and grounded in rigorous primary research, the report maps the MPGF landscape through 2032 and identifies the concrete implications that procurement teams, operations leaders, and corporate strategy groups must address in 2026.
Worldwide Multi-Point Ground Flares (MPGF) Market
Market trajectory at a glance
Our baseline model shows the MPGF market continuing a steady expansion from the mid-2020s into the next decade, underpinned by lifecycle replacements, capacity additions in petrochemical and LNG projects, and regulatory-driven retrofits. The market demonstrates a compound annual growth rate (CAGR) of 6.52% through the forecast horizon, reflecting a balance of long-tail replacement cycles and episodic large projects that periodically rebase demand. This pace of growth, combined with observed year-on-year increases in system uptake, signals both predictable demand windows and intermittent opportunities for outsized revenue capture by suppliers able to scale rapidly.
Worldwide Multi-Point Ground Flares (MPGF) Market
Why this report matters for 2026 strategic planning
- Capital allocation and project timing: The MPGF product class is capital-intensive with long lead times. Our scenario schedules and cash-flow sensitivity analyses help CFOs and project sponsors prioritize which flare procurements to accelerate or defer within the 2026 budget cycle to optimize return-on-capital and reduce exposure to supply-chain volatility.
- Procurement and supplier selection: Vendors differ markedly on turnkey capability, staging control philosophies, and smokeless performance at low flows. The report’s vendor diagnostic layers technical suitability against lifecycle cost to support procurement RFP design and negotiation strategy in 2026.
- Regulatory compliance and emissions oversight: New and clarified regulatory expectations — including accepted alternative means of emission limitation and evolving monitoring mandates — make compliance planning a first-order business risk. Our regulatory playbook converts obligations into operational checklists and capital upgrade timelines that legal and HSE leaders must act on in 2026.
- Operational reliability and continuity: For operators, the trade-off between radiant heat reduction, smokeless performance, and turndown flexibility determines both plant uptime and community relations. The report’s failure-mode and lifecycle-maintenance models quantify these trade-offs to inform O&M budgeting for the coming year.
What’s inside — practical deliverables you can use now
PW Consulting’s MPGF study is intentionally tactical and decision-focused. Core deliverables include:
Worldwide Multi-Point Ground Flares (MPGF) Market
- Proprietary market-sizing model with historic calibration (2020–2025) and forward scenarios (2026–2032), enabling users to test bespoke growth assumptions against our base-case CAGR.
- Investment-screening tools: IRR and payback simulations for retrofit versus greenfield MPGF acquisitions across a variety of operating regimes.
- Procurement playbook: RFP templates, technical checklists, and scoring matrices mapped to operational priorities (e.g., smokeless at low flow, staging responsiveness, closed-enclosure systems).
- Vendor benchmarking dossiers: comparative analysis of engineering approaches, delivery models (supply-only vs turnkey), after-sales service footprints, and risk profiles.
- Regulatory and monitoring roadmap: a synthesis of regional compliance requirements, accepted performance testing protocols, and monitoring/recordkeeping expectations tied to common MPGF configurations.
- Scenario risk register: supply-chain, regulatory, demand, and reputational risks with mitigation pathways and contingency trigger points for 2026 planning cycles.
Competitive landscape — who leads and why it matters
The MPGF supplier field is populated by a mix of specialized combustion houses and larger process equipment incumbents. Our qualitative analysis identifies several competitive vectors that will shape market outcomes in 2026:
- Technical differentiation: Suppliers offering multi-stage staging systems and effective assist-gas strategies secure superior smokeless performance across wide turndown ranges — a critical advantage for customers facing strict visibility and emissions constraints.
- Turnkey capability: The gap between supply-only vendors and those offering complete engineering, procurement, and commissioning (EPC) services is material when projects require integrated controls, monitoring, and containment solutions.
- Operational footprint and aftermarket: Rapid commissioning and local spares availability reduce downtime risk; suppliers with established service networks command a price premium during tight delivery cycles.
Notable vendor archetypes and strategic positions:
- Performance-optimized specialists — firms focused on high-destruction efficiency and advanced staging control are preferred where smokeless operation and low visible plume are non-negotiable.
- Turnkey integrators — companies with demonstrated EPC delivery and project financing relationships tend to win complex greenfield and retrofit contracts requiring integrated control-room integration and environmental reporting.
- Enclosed-combustion innovators — vendors delivering enclosed-array solutions appeal to high-capacity sites with community proximity constraints, offering noise and radiant-heat mitigation advantages.
In the competitive appendix of our full report, we profile leading firms across these archetypes, examining strengths, typical contract structures, and the strategic implications of recent product campaigns and project wins.
Recent market signals and regulatory dynamics
Several recent developments underscore the operational and regulatory drivers shaping 2026 choices. Industry product promotions and project implementations continue to emphasize the trade-offs between smokeless performance, turndown capability, and site visibility. Notably, companies are also increasing surveillance and instrumentation at MPGF installations — a sign that operators are prioritizing continuous monitoring and compliance defensibility.
On the regulatory front, recognized acceptance of pressure-assisted MPGF configurations under certain alternative emission controls has created a pathway for broader adoption in jurisdictions with stringent opacity and emissions rules. At the same time, standards — including international and domestic design and performance codes — require careful interpretation when tendering complex MPGF solutions. Our regulatory mapping translates these standards into procurement-ready requirements.
Key risks and opportunity vectors for 2026
- Supply-chain concentration: Lead times for burners and control skids remain the principal bottleneck. Firms that lock supply agreements early in 2026 reduce schedule risk.
- Regulatory tightening: Accelerating monitoring and reporting requirements could force unplanned retrofits; companies with modular designs and field-upgrade paths will be better positioned.
- Community relations and ESG scrutiny: Visible flaring events continue to attract stakeholder attention. Investment in low-visibility, low-radiation technologies yields reputational and permitting advantages.
- Technological convergence: Integration of automated staging, remote monitoring, and predictive maintenance is creating service-differentiation opportunities for suppliers and operators willing to invest in digital overlays.
How to apply the report in your 2026 planning cycle
The report is designed as a decision-support toolkit for 2026. Practical next steps we recommend:
- Use the market-sizing scenarios to stress-test internal demand projections and phase capital allocation across fiscal quarters to smooth supplier demand.
- Adopt the procurement checklists to convert performance requirements into measurable RFP criteria; require bidders to map compliance to specific standards and monitoring protocols.
- Prioritize modular solutions where possible to reduce retrofit lead times and allow incremental commissioning aligned with evolving regulatory milestones.
- Engage in supplier rationalization: select a short list combining a performance specialist and a turnkey integrator to diversify delivery risk while maintaining technical assurance.
- Embed monitoring and data-analytics requirements into contracts to capture operational insights and create pathways for predictive maintenance and emissions reporting.
Conclusion — positioning for advantage in 2026
Multi-Point Ground Flares occupy a nexus of environmental compliance, public acceptance, and process safety — making them a strategic asset rather than a commoditized piece of equipment. PW Consulting’s MPGF market study offers the modelling, procurement tooling, and vendor intelligence that decision-makers need to turn a regulatory and operational challenge into a competitive advantage. The steady market growth projected through 2032, together with the technology and regulatory drivers outlined above, creates a predictable planning environment for those who act early and structure procurements to prioritize flexibility and compliance.
For executives and technical leads preparing 2026 budgets and capital plans, the full report provides the granular segmentation, vendor scorecards, and downloadable models required to execute with confidence. Access the comprehensive findings, proprietary models, and vendor profiles on our report page to operationalize these insights.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Point Ground Flares (MPGF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Negative Ion Cyclotron Market Poised to Reach USD 646.16 Million by 2032, New Insight Report Says
By pmarketresearch, 2026-07-15
Worldwide Negative Ion Cyclotron Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As healthcare systems, industrial research facilities, and national isotope programs approach a new phase of capital investment, PW Consulting’s latest market study on the Worldwide Negative Ion Cyclotron Market delivers the strategic intelligence required to make high‑confidence decisions in 2026. The market reached an estimated USD 425.5 Million in our base year (2025) and the sector is projected to expand at a compound annual growth rate (CAGR) of 6.15% across the 2026–2032 forecast window. Market structure is concentrated: the leading three suppliers capture roughly two‑thirds of industry revenue, and the five largest vendors control the large majority of accessible demand. Against this backdrop, the report frames near‑term growth drivers, technological chokepoints, regulatory inflection points, and actionable responses for equipment OEMs, hospital systems, investors, and national program planners.
Worldwide Negative Ion Cyclotron Market
Why this matters for 2026 strategic planning
2026 will be a make‑or‑break year for many capital projects and supply‑chain realignments in the radiopharmaceutical and particle therapy ecosystems. Decision cycles for cyclotron procurement, facility design, regulatory clearance, and financing commonly span 12–36 months. A nuanced understanding of market momentum, vendor positioning, and the technical constraints that determine throughput and operational cost is therefore essential. Our study synthesizes historical performance (2020–2025) with forward projections (2026–2032) to convert macro momentum into programmatic recommendations — from timing capex to structuring supplier agreements and prioritizing R&D investments.
Worldwide Negative Ion Cyclotron Market
What the report contains: practical, deployable intelligence
- Primary market sizing and evolution: validated market totals and growth trajectories, with scenario modeling to stress‑test investment returns under conservative, base, and upside adoption paths.
- Operator economics: build vs. buy models for in‑house isotope production, utilization thresholds for payback, and sensitivity to isotope yield and downtime.
- Procurement playbook: RFP templates, critical technical specifications, acceptance testing checklists, and contractual clauses to mitigate delivery and performance risk.
- Regulatory and compliance map: clear paths to alignment with international frameworks (radiation protection, medical device classification, export control) and recommended documentation workflows to accelerate approvals.
- Technology and operations roadmap: prioritized areas for incremental improvements (ion source reliability, RF efficiency, vacuum integrity) and a timeline for when technology shifts will materially change unit economics.
- Strategic M&A and partnership toolbox: criteria for bolt‑on acquisitions, JV structuring guidance for market entry, and due‑diligence checklists tailored to cyclotron assets and service capabilities.
Market sizing and structure: what the headline numbers imply
The headline market figure and the 6.15% CAGR convey two important strategic signals. First, demand is supportive of continued vendor investment in service networks and product line extensions — not a fleeting niche. Second, growth is sufficiently steady to justify multi‑year R&D programs focused on reliability and throughput rather than one‑off capacity expansions. The concentration data underscores another reality: established incumbent vendors retain structural advantages in distribution, regulatory track record, and installed base servicing. New entrants or diversification strategies therefore require either a distinctive technology advantage or a go‑to‑market partnership that accelerates credibility.
Worldwide Negative Ion Cyclotron Market
Competitive landscape: who shapes supply and why that matters
The sector’s competitive map is dominated by a small group of companies with deep clinical and industrial track records. Leading European and North American OEMs offer mature product families spanning low‑ to high‑energy negative ion cyclotrons tailored for PET isotope production and select therapeutic isotopes. Notable recent developments illustrate incumbent momentum: a major European supplier expanded high‑energy capacity through strategic orders and installations in 2023, while established North American players continued to place mid‑range systems in expanding PET facilities across Europe and Asia.
What this means for buyers and investors:
- Vendor selection increasingly hinges on lifecycle service capability — downtime penalties from supply interruptions are a leading driver of total cost of ownership.
- Scale matters for regulatory support: suppliers with multiple installations in similar regulatory jurisdictions accelerate site approvals and acceptance testing.
- Technology parity in base performance places a premium on after‑sales services, consumable logistics, and local training programs.
Regulation, export control and standards — strategic constraints & enablers
Regulatory and export regimes are not background noise; they shape project feasibility, cost, and timing. Medical cyclotrons are subject to rigorous safety and device regulation frameworks. For radiation protection and facility design, international standards provide baseline requirements that influence shielding, layout, and operating procedures. Under prevailing European medical device regulations, relevant equipment classifications and quality standards necessitate documented QMS processes that vendors and buyers must demonstrate during procurement and commissioning. Separately, high‑energy systems face export licensing regimes where national and multilateral controls can delay cross‑border transactions. In short, regulation is a strategic input to procurement timelines and partnership choices, and our report provides a decision matrix for navigating these constraints.
Technical chokepoints and R&D priorities
Two technical realities constrain scaling and define near‑term R&D priorities. First, negative hydrogen (H‑) ion sources in commercial cyclotrons are practically limited in beam current by space‑charge effects and extraction efficiency; the industry currently operates within a constrained current envelope. Second, stable operation requires significant RF drive and ultra‑high vacuum systems — facility designs typically provision for multi‑hundred kilowatt RF systems and vacuum levels in the ultra‑high range to avoid beam loss and component degradation. These engineering limits translate into predictable performance ceilings for isotope yield and operating cost.
For executives allocating R&D budgets, the strategic choices are clear:
- Invest in incremental improvements to ion source lifetime and extraction efficiency — these yield direct improvements in throughput without requiring a step change in facility footprint.
- Optimize RF subsystem efficiency and thermal management to lower operating expense and reduce infrastructure demand.
- Develop system‑level diagnostics and predictive maintenance software to increase uptime and accelerate mean time to repair.
Operational and supply‑chain considerations
Facility operators and integrators must plan for significant utility and environmental controls. RF power provisioning, stringent vacuum systems, and radiation shielding are non‑negotiable design elements that affect capital expenditure and site selection. Consumable supply — targets, windows, ion source parts — and access to qualified service engineers are recurring drivers of operational resilience. The report supplies a practical supplier mapping and lead‑time matrix to align purchasing schedules with project milestones, reducing the risk of commissioning delays.
Strategic recommendations for 2026 action
Pushing strategy from insight to action, the report advances a prioritized list of measures for stakeholders preparing decisions in 2026:
- Buyers (hospitals, research consortia): initiate procurement processes with 18–24 month lead times; prioritize vendors with regional service hubs and demonstrated regulatory dossiers in your jurisdiction.
- OEMs: focus R&D on reliability and serviceability; consider modular service contracts and localized consumable supply agreements to lock in recurring revenue.
- Investors and private equity: target platform plays that combine manufacturing competence with strong service networks; consider roll‑up strategies that add regional service centers to bolt‑on cyclotron businesses.
- Policymakers and program planners: align grant and procurement windows with realistic export and licensing timelines; prioritize investments that reduce dependency on cross‑border isotope supply.
Risk factors and mitigation
Key risks include export licensing delays for high‑energy systems, supplier concentration exposing buyers to single‑point service risk, and the slower‑than‑expected pace of clinical adoption for new isotopes that could suppress upper‑end forecasts. The report includes scenario playbooks and contract templates that mitigate these exposures — for example, preferred supplier agreements with explicit uptime guarantees, contingency plans for target and consumable shortages, and staged procurement tied to milestone payments.
How to use this report now
The published study functions as both a strategic primer and an execution manual. It is organized so that executives can quickly extract board‑level implications, procurement managers can operationalize the procurement playbook, and technical teams can access prioritized R&D roadmaps. Importantly, while this summary surfaces the report’s principal conclusions and the strategic value it delivers for 2026 decision cycles, detailed segment breakouts, regional and application split tables, and vendor‑level quantitative metrics are reserved for the full study to preserve the integrity of proprietary analyses and to guide readers to the source for complete data.
Next steps
If your organization is preparing capital budgets, structuring a market entry, or evaluating acquisition targets in the negative ion cyclotron space, the PW Consulting report is designed to accelerate your critical path to decision. The full dossier includes executable tools — from RFP templates to service‑level KPIs and scenario financial models — that convert insight into deliverable outcomes. For access to the full study and the proprietary datasets, follow the link provided by our release distribution.
Closing note from PW Consulting
Negative ion cyclotrons occupy a unique intersection of medical value, industrial utility, and strategic supply importance. The market’s steady growth and concentrated vendor landscape create both opportunity and constraint. Our analysis equips leaders with the context and instruments to convert market trends into robust 2026 strategies while avoiding common operational, regulatory, and technology traps. PW Consulting remains available to brief executive teams, run tailored procurement workshops, and support transaction diligence informed by the findings of this study.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Student Microscopes Market to Expand at 5.1% CAGR (2026–2032), Hitting USD 1.06 Billion by 2032 — Compound Microscopes, K‑12 and Asia‑Pacific Lead
By pmarketresearch, 2026-07-15
Worldwide Student Microscopes Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest industry brief previews the forthcoming Worldwide Student Microscopes Market research report. This article synthesizes the analysis and strategic takeaways senior executives, product leaders, and investors should prioritize as they map 2026 decisions. We demonstrate the underlying market trajectory, supply-chain realities, competitive dynamics, and practical playbooks included in the full report—while deliberately reserving granular segment-level disclosures to the full publication to protect the report’s actionable value.
Worldwide Student Microscopes Market
Market snapshot: an established market on a measured growth path
Our base-year analysis (2025) and historical review (2020–2025) show a mature, steady market for student microscopes that balances slow product commoditization with pockets of premiumization driven by digital imaging and education technology integration. In constant 2025 USD terms, the student microscopes market is positioned at approximately 751.5 Million USD in 2025. Under PW Consulting’s central forecast scenario for 2026–2032, the market grows at a compound annual growth rate (CAGR) of roughly 5.1%, reaching an estimated 1,064.5 Million USD by 2032.
Worldwide Student Microscopes Market
This trajectory reflects a combination of recurring replacement cycles in institutional education, incremental technology-driven upgrades (digital/USB imaging, wireless connectivity), and an expanding home-education and hobbyist base that continues to attract consumer-grade innovations. For executives, the headline here is clarity: the market is large enough to matter, predictable enough to plan against, and dynamic enough to reward targeted investments in product and channel differentiation.
Worldwide Student Microscopes Market
Why this matters for 2026 strategy
-
Portfolio prioritization: As fiscal planning for 2026 commences, companies need to balance legacy mechanical-optical lines with investments in digital microscopy platforms and software-enabled services. The projected mid-single-digit CAGR signals opportunity for margin expansion through premiumization, not a race to the bottom on price alone.
-
Channel reconfiguration: School procurement cycles and the increasing role of online retail demand a dual channel play—maintain institutional sales capabilities while scaling D2C and edtech partnerships to capture out-of-cycle, high-ARPU home and hobbyist buyers.
-
Supply-chain resilience: Our analysis identifies raw-material and assembly cost drivers that will determine cost competitiveness in 2026. Lens blanks, for example, continue to be influenced by borosilicate supply dynamics; unit-level assembly labor cost advantages persist in offshore high-volume manufacturing but are sensitive to logistics and tariff regimes.
-
Regulatory readiness: Compliance requirements for educational optics and electronics (including biocompatibility standards and regional electrical safety markings) increasingly affect time-to-market for school-focused models—an often-underappreciated gating factor for 2026 launches.
What the full PW Consulting report delivers
The report is structured for direct operational use by product managers, corporate strategists, and commercial leaders. It combines quantitative market sizing and multi-year forecasts with practical decision tools. Highlights include:
- Market sizing & method transparency: Clear articulation of methodologies used to produce the 2025 base and 2026–2032 forecast series, enabling companies to re-run scenarios under different assumptions.
- Demand-driver intelligence: Segmented demand drivers mapped to procurement channels and buyer personas (K-12 administrators, university lab managers, home/hobbyist buyers, and edtech integrators).
- Product and pricing playbooks: Benchmarks for product-tiering, feature bundles, and pricing architectures that protect margin while expanding addressable markets.
- Go-to-market blueprints: Channel sequencing, tendering strategies for institutional buyers, and a digital-retail optimization checklist designed to improve conversion and lifecycle revenue.
- Supply-chain & cost maps: Component-cost breakdowns, supplier risk heatmaps, and a nearshoring vs offshore sourcing decision tool crafted for 2026 procurement cycles.
- Regulatory & compliance digest: Critical certification timelines and implications for product launch calendars in major education markets.
- Competitive intelligence: Profiled strategies, product roadmaps, and capability matrices for the leading incumbent vendors and fast-follow specialists.
- Scenario planning: Three alternate futures (base, accelerated adoption, and prolonged commoditization) with their respective P&L impacts to aid board-level decision-making.
Competitive landscape — incumbent strengths and strategic openings
The student microscopes market blends global instrument manufacturers, dedicated education brands, and consumer-science entrants. PW Consulting’s qualitative assessment identifies the following competitive archetypes and tactical recommendations:
-
Education-focused incumbents (e.g., AmScope, Swift, OMAX): These players benefit from deep distribution into K–12 and home-school channels, recognized product durability, and broad SKUs. Their near-term advantage lies in trusted institutional relationships and established replacement cycles. Strategic recommendation: convert installed base into upgrade pathways through trade-in programs and bundled digital-imaging kits.
-
Consumer/science hybrids (e.g., Celestron, Motic): These vendors leverage consumer retail and hobbyist channels, offering portable and value-driven models that are attractive to parents and amateur scientists. Strategic recommendation: develop educational content and subscription imaging apps that anchor long-term engagement and recurring revenue.
-
Premium laboratory brands with education lines (e.g., Leica, Olympus/Evident): These vendors provide modular, durable classroom microscopes with potential upsell to higher education markets. Strategic recommendation: create clear product pathways from classroom to lab to capture lifetime value of institutional customers.
-
Regional specialists (e.g., Meiji Techno, Euromex, NOVA): These suppliers have advantages in local channel partnerships and compliance familiarity. Strategic recommendation: form selective distribution alliances and local certification accelerators to reduce launch friction.
Recent product and go-to-market moves underscore these dynamics: product refreshes with improved LED illumination and portability, catalogs emphasizing digital and WiFi-enabled microscopes, and increased visibility at education-technology trade events. These developments validate the market’s shift toward imaging and classroom mobility—areas that pay off for early movers in 2026.
Operational factors that will shape 2026 outcomes
-
Component economics: Glass lens blanks and optics materials remain a non-trivial cost input; our supply-side modeling uses contemporary unit-price ranges to simulate margin sensitivity under input-price volatility. Manufacturers that lock favorable long-term supply agreements or invest in in-house coating and lens production will have clearer margin paths in 2026.
-
Assembly economics: High-volume assembly labor costs in offshore hubs continue to be lower than in developed markets. However, logistics, quality control, and nearshoring premium need to be factored into total landed cost calculations for 2026 product launches.
-
Standards and certification: Educational optics and associated electronics are subject to safety and biocompatibility standards; early engagement with regulatory bodies shortens certification timelines and minimizes costly product rework.
Practical 2026 playbook — five priority moves
-
Define a two-track product strategy: Maintain proven mechanical lines for institutional procurement while investing in a digital-imaging platform (hardware + software) designed for recurring revenue.
-
Build channel-specific offerings: Create tender-ready bundles for schools and universities, and curated D2C bundles with learning content for home buyers.
-
De-risk supply chains: Hedge optical component sourcing, establish secondary assembly partners, and model price scenarios for input-cost shocks.
-
Accelerate regulatory readiness: Prioritize certifications that shorten procurement cycles in key education markets and make compliance a selling point in bid responses.
-
Monetize data and services: Leverage imaging platforms to offer classroom analytics, remote lab access, and teacher training subscriptions—new levers for margin expansion beyond hardware.
How PW Consulting’s report supports execution
The full report is not just descriptive—it is prescriptive. Subscribers receive executable artifacts: pricing decks, channel scorecards, supplier negotiation scripts, procurement-tender templates, and a shortlist of M&A targets with readiness scores. We also provide an interactive forecast model so teams can run sensitivity tests on price, mix, and channel shifts to quantify expected EBITDA impact under alternative 2026 strategies.
Importantly, while this preview outlines the report’s structure and high-level conclusions, granular subsegment revenues, region-by-region breakdowns, and unit-volume matrices are intentionally omitted here. That proprietary granularity is available in the full PW Consulting report and is designed to equip commercial teams with the precise inputs needed for board-level decisions in 2026.
Next steps
For product, commercial, and corporate strategy teams preparing 2026 budgets: prioritize two actions this quarter. First, secure access to the full PW Consulting Worldwide Student Microscopes Market report to obtain the segment-level intelligence and downloadable models that translate market trends into P&L impact. Second, initiate a 90-day cross-functional “2026 readiness” sprint—align product roadmap, channel incentives, supplier contracts, and compliance checklists—using the report’s playbooks as the operating manual.
PW Consulting’s full report provides the detailed forecasts, vendor profiles, and operational tools necessary to turn the market’s 5.1% CAGR and its multi-year growth profile into tangible commercial advantage. Contact our research desk to access the complete study and the interactive scenario-planning assets that will inform confident, profit-focused decisions for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Student Microscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Surgical Tray Market Valued at USD 540.2 Million in 2025, Set for Robust Expansion
By pmarketresearch, 2026-07-15
Worldwide Surgical Tray Market 2026: Strategic Imperatives from PW Consulting
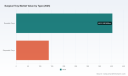
PW Consulting today publishes its latest Worldwide Surgical Tray Market report — an executive-grade toolkit designed to inform boardroom decisions in 2026 and beyond. Built on a verified historical series (2020–2025) and a seven‑year forecast (2026–2032), the study models market trajectories under multiple scenarios and quantifies the operational levers that will determine winner/loser outcomes across suppliers, providers, and investors. The market demonstrates resilient expansion: from a measured base in 2020 through a 2025 base year of USD 540.2 Million, the sector is projected to grow at a 5.81% compound annual growth rate under our baseline assumptions, reaching an estimated USD 801.6 Million by 2032. These headline metrics set the context for targeted 2026 strategy.
Worldwide Surgical Tray Market
Why this report matters for 2026 decision-makers
-
Actionable foresight for procurement: rapid shifts in purchasing models, sterilization protocols, and sustainability standards mean procurement teams need forward-looking TCO tools, supplier scorecards, and contract playbooks to lock in performance and margin protection.
Worldwide Surgical Tray Market -
Product and R&D prioritization: manufacturers must decide where to allocate limited R&D budgets between modular reusable systems, single‑use disposables, and hybrid product lines that improve sterilization throughput and reduce lifecycle costs.
Worldwide Surgical Tray Market -
M&A and corporate development: private equity and strategic acquirers need granular risk-adjusted deal valuations that account for sterilization compliance, concentration dynamics, and supplier concentration across hospital systems and ambulatory settings.
-
Operations and capital planning: hospitals and central sterile processing (CSPD) managers require capital planning scenarios that align tray inventories, cleaning load, and instrument turnover with epidemiology-driven case mix changes.
What the PW Consulting report delivers (operationally focused)
-
Executive dashboard: concise KPIs, baseline and stress forecasts, and a five‑year opportunity map linking strategic moves to profit and service outcomes.
-
Market sizing and methodology annex: transparent modeling assumptions, data sources, and a downloadable Excel model that lets you run your own sensitivity analyses against price, utilization, and sterilization costs.
-
Scenario-based forecasts: baseline (policy-stable), upside (accelerated ambulatory shift and sustainability adoption), and downside (supply shock or regulatory tightening) projections with decision triggers mapped to each.
-
Competitive playbook: supplier scorecards, win/loss themes, contract levers, and product differentiation matrices to inform procurement negotiation and product roadmaps.
-
Sterilization and regulatory playbook: step‑by‑step requirements for ISO 17665-1 validation, FDA 510(k) pathways for instrument trays, and implementation checklists to satisfy AAMI ST79 cleaning thresholds.
-
Supply‑chain risk matrix: raw material sensitivity analysis (including medical‑grade 316L stainless steel input cost dynamics), nearshoring options, and supplier contingency playbooks.
-
M&A and partnership framework: target screening criteria, valuation sensitivities tied to product mix, and integration playbooks for manufacturers and service providers.
-
Implementation tools: SKU rationalization templates, procurement RFP language, sterilization validation templates, and a hospital CSPD benchmark toolkit.
Market dynamics shaping 2026 strategy
The surgical tray market sits at the intersection of clinical demand, sterilization science, and procurement economics. Three dynamics will dominate near‑term strategy:
-
Clinical throughput and site-of-care migration. Continued movement of appropriate cases to ambulatory surgical centers and specialty clinics pressures tray volumes and encourages modular, easy‑to‑clean systems that reduce turnaround time.
-
Regulatory and sterilization rigor. Compliance with ISO 17665-1 for moist‑heat sterilization validation, the practical implications of FDA device classification pathways, and adherence to AAMI ST79 cleaning protocols impose both time and cost on manufacturers and providers. Hospitals that invest early in validated cleaning processes reduce bioburden risk and may realize lower lifecycle costs despite upfront capital spend.
-
Cost and material sensitivity. Raw material inputs — notably medical‑grade 316L stainless steel — represent a predictable but non‑trivial component of product cost; industry references currently put market pricing in a narrow band that materially affects manufacturer margins and pricing elasticity. Manufacturers that optimize material use, or substitute appropriately where clinical guidelines allow, will gain cost advantage.
Market concentration is meaningful but not prohibitive: the top three firms account for a sizeable share of the sector, and the top five further consolidate influence, leaving room for niche specialists and regional innovators to capture adjacencies or to be attractive acquisition targets.
Competitive landscape — what the main players reveal about industry direction
-
Cardinal Health, Inc. (Dublin, Ohio) — a global leader in custom sterile procedure trays. Cardinal’s multi‑year contracting activity with large hospital systems illustrates a strategy centered on scale, customization, and integrated supply solutions. For buyers, Cardinal remains a benchmark for contract design and value‑added services.
-
Medline Industries, LP (Northfield, Illinois) — a vertically integrated manufacturer of both reusable stainless steel and disposable plastic trays. Medline’s catalog expansions demonstrate a product design focus on modularity and clinician ergonomics; competitors should expect continued investment in fit‑for‑purpose tray sets and supply chain resilience.
-
B. Braun Melsungen AG (Melsungen, Germany) — emphasizes modular stainless steel containers engineered for steam and EO sterilization, signaling demand for durable solutions that integrate with CSPD workflows.
-
Steris plc (Dublin, Ohio) — with recent product innovation in rigid container systems designed to improve sterilization efficiency, Steris is positioning at the intersection of equipment and consumable solutions, creating cross‑sell opportunities into hospital sterile processing departments.
-
Teleflex Incorporated (Wayne, Pennsylvania) — through the Pilling brand, Teleflex focuses on specialty configurations (perforated and solid bottoms) serving instrument-specific needs, a reminder that product differentiation remains a viable strategy.
-
Integra LifeSciences (Princeton, New Jersey) — a niche player in neurosurgery and orthopedics, demonstrating that clinical specialization and instrument ecosystem coherence can create defensible margins in targeted segments.
-
Becton, Dickinson and Company (BD) (Franklin Lakes, New Jersey) — integrates tray solutions within broader procedural kits, underscoring the value of bundling and device ecosystems for customers seeking one‑stop procurement.
-
Mölnlycke Health Care AB (Gothenburg, Sweden) — focuses on custom procedure trays for wound care and general surgery, reflecting demand for tailored solutions with strong clinical support and hygiene credentials.
Recent product launches, catalog expansions, and supply agreements reflect three parallel strategic plays: (1) deepen relationships with large hospital systems through bespoke contracting and service bundling; (2) invest in sterilization‑efficient container systems that reduce CSPD cycle time; and (3) expand product families toward modularity and clinical specificity.
Strategic recommendations for executives in 2026
-
Procurement and hospital systems: adopt a dual‑track sourcing strategy — secure core capacity with established global suppliers while cultivating niche suppliers for clinical specialties. Insist on sterilization validation data and include service-level KPIs tied to CSPD turnaround and instrument availability.
-
Manufacturers: prioritize modular, sterilization‑compatible designs and invest in life‑cycle cost modeling to demonstrate value over single‑use alternatives. Build rapid validation pathways for ISO 17665-1 and FDA 510(k) where applicable.
-
Investors and acquirers: focus diligence on sterilization compliance, CSPD adoption curves, and supplier concentration risk. Small to mid‑cap players with strong clinician relationships and flexible manufacturing can be high‑value targets.
-
Operations leaders: normalize investments in CSPD automation and validated cleaning protocols per AAMI ST79 — doing so reduces infection risk and unlocks tray reuse opportunities that favor hospital economics.
-
Product development: accelerate features that improve sterilization throughput (venting, modular inserts, anti‑fog plating) and reduce lifecycle environmental footprint to capture sustainability-minded buyers.
-
Risk management: hedge raw‑material exposure through multi‑year supply commitments or strategic local sourcing. Embed contract clauses that allow for pass‑through of material cost spikes tied to transparent indices.
How PW Consulting supports 2026 execution
We pair the report’s downloadable models with advisory services that include supplier benchmarking, procurement RFP execution, M&A transaction support, and pilot design for tray reconfiguration or CSPD upgrades. Our engagements are structured to move from strategy to measurable implementation within a 6–12 month horizon, delivering the governance, KPIs, and playbooks necessary to convert insight into margin and service improvement.
PW Consulting’s Worldwide Surgical Tray Market report provides the strategic context and operational tools required to make high‑confidence decisions in 2026 — from contract negotiations and product roadmaps to M&A playbooks and CSPD investments. For the full dataset, granular segmentation, and downloadable Excel models that contain regional, type, and end‑user splits, please visit our report landing page or contact PW Consulting for an executive briefing and licensing of the underlying data.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide System on Module Boards Market to Grow at a 11.45% CAGR from 2026 to 2032
By pmarketresearch, 2026-07-15
Worldwide System on Module (SoM) Boards Market — Strategic Outlook to 2032
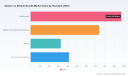
PW Consulting today publishes a focused strategic brief drawn from our new market research, Worldwide System on Module Boards Market (base year 2025, forecast 2026–2032). The SoM market has moved beyond niche embedded projects to become a mainstream platform strategy for industrial automation, edge AI, medical devices, transportation and other mission-critical systems. Our analysis shows the market expanding at a sustained compound annual growth rate (CAGR) of 11.45% from the 2025 base, with global revenue growing from USD 1,420.2 Million in 2020 to USD 2,450.5 Million in 2025 and a projected USD 5,233.78 Million by 2032. This trajectory presents both an opportunity and a set of operational and strategic imperatives for 2026 decision-makers.
Worldwide System on Module Boards Market
Why this matters for 2026 decision cycles
-
Design-to-deployment cadence: SoMs reduce time-to-market for complex embedded solutions, but they also alter supplier relationships and technical debt profiles. Companies making architecture choices in 2026 will lock in multi-year platform dependencies.
Worldwide System on Module Boards Market -
Supply chain resilience: The SoM value chain is sensitive to semiconductor policy, tariffs and critical material price swings. Procurement and engineering teams must adopt integrated sourcing-and-design strategies to avoid costly redesigns or production delays.
Worldwide System on Module Boards Market -
Value capture and differentiation: As the overall market doubles over the next decade, differentiation will shift from raw processing power toward software, integration services and long-term lifecycle support—areas where OEMs can capture margin or cede it to module suppliers.
What the report delivers — practical, transaction-ready intelligence
-
Market sizing and multi-scenario forecasts (2020–2032) with baseline, upside and downside paths linked to semiconductor supply, regulatory shifts and adoption of edge AI workloads.
-
Architecture and standards analysis mapping (ARM, x86, FPGA/PowerPC and the leading module standards) that explains trade-offs in performance-per-watt, certification complexity, longevity and ecosystem support.
-
Supplier scorecards and a competitive playbook that combine technical roadmaps, product maturity, geographic manufacturing footprints and partner ecosystems to support vendor selection and negotiation.
-
Hands-on deployment playbooks: BOM sensitivity models, lead-time mitigation templates, version-control and EOL migration plans to protect program timelines and margins.
-
Regulatory and trade impact assessment including scenario mapping for export controls, tariffs and localization incentives—translated into quantitative risk factors for procurement and R&D planning.
-
M&A and partnership heatmaps identifying adjacencies, bolt-on targets and co-development opportunities across regions and end-markets.
Competitive landscape — who matters and why
The SoM supplier ecosystem is diverse, with specialist vendors driving innovation alongside established embedded systems houses. Our report profiles the full competitive set and provides actionable intelligence on go-to-commercial strategies. Highlights:
-
Toradex (Horw, Switzerland) — a market leader in rugged, industrial-grade modules (Verdin, Colibri, Apalis) leveraging NXP, TI and Renesas families; strong in long-life and support for industrial deployments.
-
Variscite (Yokneam, Israel) — focused on compact DART and VAR-SOM lines for IoT and edge compute, with an emphasis on fast time-to-market and custom engineering support.
-
Kontron (Augsburg, Germany) — a systems integrator offering modules across SMARC, Qseven and COM Express standards with broad ruggedization and certification capabilities for industrial and transportation segments.
-
Advantech (Taipei, Taiwan) — strong portfolio for industrial automation and medical applications, combining SoMs and carrier boards with global manufacturing and field service.
-
Phytec (Mainz, Germany) — known for automotive- and avionics-oriented SoMs, with recent product introductions targeting ADAS and machine vision applications.
-
Compulab, Gateworks, TechNexion, MYIR Tech, Forlinx Embedded Technology, AAEON, IEI Integration Corp and Seco — each bringing regional strengths, specific processor optimizations and differentiated value in verticals such as defense, outdoor wireless, AI vision and HMI.
Recent commercial and product activity underlines the market’s technical momentum: leading vendors have been qualifying SoMs with next-generation application processors, launching modules tailored for edge AI, and ramping production to meet demand for higher compute density at the edge. These moves shorten development cycles for customers but raise the bar on lifecycle and compatibility management.
Market structure and concentration — what to expect
The market remains moderately consolidated: a handful of suppliers capture a notable share of industry revenue while a long tail of regional specialists serves niche verticals. This structure favors strategic partnerships for scale but leaves room for focused entrants that offer differentiated software, service-level agreements or regulatory certification expertise. For procurement teams, the implication is clear—vendor selection must balance performance, long-term support and geopolitical exposure.
Supply-chain and policy dynamics that will shape 2026 decisions
-
Policy levers: Initiatives such as the EU Chips Act are accelerating upstream capacity investments that can ease component constraints by the end of the decade. Conversely, export control regimes and targeted tariffs can quickly reroute sourcing options and raise the total landed cost for sensitive modules or components.
-
Component lead times and availability: Our analysis detects improving lead-time metrics for many mainstream SoC families compared with peak disruption years; however, lead times remain volatile for high-end SoCs and certain specialty components, necessitating multi-sourcing and design flexibility.
-
Input-cost risk: Price movements in critical raw materials (e.g., gallium for GaN components) have meaningful margin and design implications for power-efficient SoMs. Expect engineering trade-offs between power budgets and bill-of-materials economics to intensify.
-
Trade friction and manufacturing footprint decisions: Tariffs and export rules are driving increased interest in regional assembly and qualification, especially for regulated end-markets such as medical and defense.
Actionable strategic recommendations for 2026
-
Run a supplier-risk and architecture alignment audit within 90 days. Map your product roadmaps to supplier lifecycles and identify single points of failure, particularly around high-dependency SoCs and specialized modules.
-
Adopt a “design-for-supply” discipline. Treat SoM selection as a supply chain decision as much as an engineering one: require suppliers to deliver lifecycle, long-term availability commitments and clearly defined EOL pathways.
-
Prioritize modularity and standard-based migration paths. Where product form factors allow, choose standardized module families to enable future CPU swaps without full carrier redesigns.
-
Lock in price and lead-time hedges for critical components when justified. Use staged purchasing and buffer strategies to smooth production spikes while keeping inventory economics under control.
-
Engage in strategic co-development or exclusivity for differentiating features (security, safety certification, custom ISP or accelerators) to preserve product differentiation as raw compute becomes commoditized.
-
Prepare regulatory scenarios. Integrate export-control and tariff scenarios into project financials and supplier scorecards; consider regional qualification tracks where regulation or tariffs materially change TCO.
-
Scan for bolt-on assets and technology partnerships. Given market growth and consolidation dynamics, acquisitions or minority investments in specialized SoM vendors can accelerate entry into new verticals or geographies.
How PW Consulting supports your 2026 roadmap
Our report is designed as a near-term operational playbook and a medium-term strategic roadmap. Key deliverables include an interactive forecasting model (2020–2032), supplier scorecards with objective KPIs, BOM sensitivity tools, regulatory impact scenarios and templates for procurement contracts and lifecycle migration. For product leaders, the report provides a playbook that translates market growth into concrete program-level decisions; for corporate strategy teams, it surfaces M&A and partnership opportunities aligned with demand trajectories and regional policy shifts.
This summary intentionally omits granular segment-by-segment figures and certain proprietary scorecard metrics to preserve the value of the full dataset. The complete report contains detailed segmentation by architecture, standard, application and region, along with vendor market shares, price-by-configuration benchmarks and downloadable models for use in R&D, procurement and corporate planning.
Next steps
For teams making architecture, sourcing or M&A decisions in 2026, the clock is already ticking. Use our dataset and playbooks to stress-test your product plans against supply volatility, regulatory scenarios and the fast-evolving competitive landscape. To access the full analysis, detailed segment breakdowns and the downloadable forecasting model, please visit PW Consulting’s report page and request access to Worldwide System on Module Boards Market — 2025 Edition.
PW Consulting — actionable industry insight to turn market growth into decisive competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide System on Module Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide LAG3 Antibody Market Poised for 26.79% CAGR, Expected to Reach USD 6,950 Million by 2032 as North America Tops USD 792.48 Million in 2025
By pmarketresearch, 2026-07-15
Worldwide LAG‑3 Antibody Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
The Worldwide Lymphocyte Activating 3 (LAG‑3) antibody market is transitioning from a clinical curiosity into a commercially meaningful oncology modality. PW Consulting’s new report (base year 2025, forecast 2026–2032) projects a high‑growth trajectory underpinned by a compound annual growth rate (CAGR) of 26.79%. From a modest early‑stage market in 2020, our macro model shows expansion to a multi‑billion dollar opportunity by 2032 (reported in USD Million), driven by approvals, combination strategies with PD‑1/PD‑L1 therapies, and a robust pipeline of both monoclonal and multispecific constructs.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
This preview outlines the strategic value of our full report for executive teams making 2026 investment, portfolio and go‑to‑market decisions. We deliberately showcase analytical depth and actionable frameworks while reserving detailed segmentation tables, scenario spreadsheets and company‑level financials for the complete report available on PW Consulting’s website.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Why this matters for 2026 decision‑makers
-
Rapid market scaling: Our topline market model illustrates very steep growth from the mid‑teens low‑hundreds of millions in the early 2020s to a large single‑digit billion market by the end of the forecast, reflecting both uptake of approved products and conversion of multiple late‑stage programs into commercial launches.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market -
Concentrated competitive structure: Market concentration is high — the top three players control the vast majority of commercial LAG‑3 revenues, and the top five firms dominate nearly the entire market. This structural reality shapes pricing power, access dynamics and partnership opportunity sets.
-
Regulatory and reimbursement inflection points: With the first FDA approval of a LAG‑3 blocking antibody combination already establishing clinical precedent, the next 18–36 months will be decisive in setting label, reimbursement and guideline adoption patterns that will either accelerate or constrain market uptake.
Market dynamics — what the macro numbers tell us
PW Consulting’s baseline estimates for 2025 reflect a market that has achieved commercial scale and payer attention. When combined with our 2026–2032 forecast (26.79% CAGR), the numbers indicate that strategic investments made in 2026 — whether in late‑stage assets, manufacturing capacity, or commercialization infrastructure — will capture a disproportionate share of the value created over the next seven years.
Key dynamics captured in our analysis include: clinical differentiation between single‑target monoclonals, bispecific modalities, and non‑traditional LAG‑3 constructs; the centrality of PD‑1 combination strategies; regulatory momentum centered on the inaugural approved combination; and a manufacturing and supply chain profile that, while subject to the usual biologics challenges, does not currently show LAG‑3‑specific raw material bottlenecks in major markets.
What the full report contains — practical, transaction‑ready intelligence
-
Quantitative market model (2020–2032) with base, upside and downside scenarios, delivered in editable spreadsheet format. The model lets users test assumptions on clinical success rates, time‑to‑launch, price realization and market access to generate bespoke NPV and ROI outputs.
-
Pipeline and clinical risk mapping for all active LAG‑3 programs, including modality classification (monoclonal, bispecific, fusion protein, agonist), mechanism‑based competitive overlaps and program‑level probability of success assumptions.
-
Regulatory & reimbursement playbook that synthesizes precedent approvals, label dynamics, expected HTA review timelines in major markets, and payer negotiation levers specific to fixed‑dose checkpoint combinations.
-
Commercial launch readiness checklists and go‑to‑market options tailored for incumbents, late entrant biotechs and potential acquirers — including field force design, digital engagement frameworks, and patient support models.
-
Manufacturing, CMC and supply chain stress tests identifying capacity risk, CMO selection criteria, cost‑of‑goods sensitivities and points of failure that materially affect gross margins under different volume scenarios.
-
M&A and licensing decision support: valuation benchmarking, deal structuring templates, and a prioritized list of bolt‑on and platform targets aligned to strategic arcs (e.g., bispecific acceleration, autoimmune indications, manufacturing scale).
-
Competitive intelligence dossiers on leading developers, with strategic SWOTs, recent clinical milestones and an assessment of likely commercialization pathways.
Competitive landscape — players to watch and strategic positioning
The LAG‑3 competitive set includes large pharma, oncology specialty biotechs, and modular antibody platform companies. Each type of player brings distinct strategic options and constraints:
-
Bristol Myers Squibb (BMS) — As the commercial originator, BMS’s combination product established regulatory and clinical precedent. Recent trial outcomes have introduced new complexity into label extension and lifecycle planning. BMS’s choices around follow‑on indications, combination strategies and competitive defense will materially influence the commercial runway for competitors.
-
Regeneron (with strategic partner activity) — Regeneron’s late‑stage monoclonal program positions it as a near‑term challenger in the checkpoint combination space. Their clinical design emphasis, partnership model and development cadence will determine whether they contest BMS in labeled indications or pursue niche positioning.
-
Large pharmas with prior LAG‑3 investments (Merck, Novartis, Roche) — These firms bring deep commercialization muscle and are likely to compete through differentiated clinical development strategies, either pursuing broad label expansion or focusing on specific tumor types and biomarker populations.
-
Specialty biotechs and platform companies (MacroGenics, Xencor, Incyte, F‑star, Immutep) — These firms are advancing bispecifics, fusion proteins and agonist approaches that could reframe the value proposition of LAG‑3 modulation beyond oncology into autoimmune indications. Their strategic options include partnering, carve‑outs of specific assets, or leveraging bispecific IP to capture premium pricing.
-
Partnership dynamics (e.g., Sanofi collaborating on Regeneron programs) — Collaborative development models will continue to be the predominant route for sharing clinical risk and aligning commercialization capabilities for global launches.
Notable near‑term development: a major Phase III recurrence‑free survival study of a marketed LAG‑3 combination did not meet its primary endpoint in adjuvant melanoma. That result has immediate strategic consequences: it tightens evidentiary thresholds for label extension, increases the premium on positive phase III readouts, and rebalances relative value between combination strategies and differentiated modality entrants.
Strategic implications and recommended actions for 2026
For executive teams contemplating investments, partnerships or launch plans in 2026, PW Consulting recommends prioritizing three parallel tracks:
-
De‑risk the clinical and commercial pathway. Re‑specify pivotal trial designs to prioritize clinically meaningful endpoints that payers and guideline committees will accept. Consider adaptive designs, biomarker‑enriched cohorts and earlier engagement with HTA bodies in priority jurisdictions.
-
Lock down manufacturing and CMC scalability. Early capital allocation to validated CMOs or in‑house capacity reduces time‑to‑supply and protects margin potential during rapid uptake phases. Run cost‑of‑goods sensitivity analyses against multiple launch and uptake scenarios.
-
Define a differentiated commercial architecture. Whether pursuing PD‑1 combination parity or bispecific superiority, build a go‑to‑market plan that integrates value demonstration, payer evidence generation and targeted field force deployment to maximize share of voice in oncology segments with the highest therapeutic need.
Additional, tangible near‑term actions include: commissioning indication‑level real‑world evidence programs to support label expansions; negotiating staged licensing deals that share regulatory upside; and conducting focused M&A diligence on platform companies whose bispecific or fusion‑protein technologies can accelerate differentiation.
PW Consulting methodology and what you will get
The full report combines primary interviews with oncology KOLs, payer and HTA reviewers, anonymized investor diligence, and proprietary forecasting models calibrated to historical adoption curves for checkpoint inhibitors. All assumptions are transparently documented and delivered with editable scenario models so clients can rebase forecasts to their internal views.
We intentionally withhold granular segmentation tables and company‑level revenue lines in this preview to protect proprietary insight and to ensure the full analytical work product is accessed through the report portal. The full deliverable contains the actionable tables, heat maps and deal‑ready slides that corporate development, commercial and clinical teams use to operationalize strategy in 2026.
Conclusion — what to do next
The LAG‑3 antibody market presents substantial upside over the 2026–2032 horizon, but realizing that upside requires disciplined choices in clinical design, manufacturing preparedness and commercialization differentiation. PW Consulting’s report turns macro projections and competitive signal noise into decision‑grade intelligence: scenario‑tested models, specific operational checklists and a prioritized list of strategic plays for incumbents, challengers and investors.
For leaders who need to convert 2026 strategy into executable plans — from in‑licensing and M&A to launch sequencing and payer evidence generation — the full report provides the playbook. Access the complete Worldwide LAG‑3 Antibody Market report and annexed financial models on PW Consulting’s website to obtain the detailed segmentation, scenario spreadsheets and company‑level assessments reserved for report subscribers.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MRF Market to Grow from USD 4,886.96 Million in 2025 to USD 7,649.34 Million by 2032 (6.61% CAGR) — Single‑Stream MRFs, Sorting Systems and North America Lead
By pmarketresearch, 2026-07-15
Worldwide Materials Recovery Facility (MRF) Market: Strategic Preview for 2026 — PW Consulting Highlights Growth Path, Competitive Stakes and Decision Frameworks
PW Consulting’s new Worldwide Materials Recovery Facility (MRF) Market study delivers an executive-grade, action-oriented preview designed to shape capital allocation and commercial strategy decisions in 2026. The market is on a steady expansion trajectory, underpinned by regulatory tightening, accelerating automation, and shifting feedstock economics. Our analysis shows the global MRF market value rising from a mid‑2020s base to a materially larger market by the end of the forecast window, reflecting a compound annual growth rate (CAGR) of 6.61%. For leaders planning investments, partnerships, or divestitures next year, the right timing and technological choices will determine long‑term returns.
Worldwide Materials Recovery Facility (MRF) Market
Why this matters for 2026 decision-makers
2026 is the inflection year for many strategic choices: major public procurement cycles conclude, new regulatory enforcement regimes mature, and several technology nodes (sensor sorting, AI-enabled robotics, modular plants) transition from pilot to mainstream. PW Consulting’s forecast and scenario analysis make three points clear:
Worldwide Materials Recovery Facility (MRF) Market
- Market momentum is predictable at the macro level. After a period of recovery and re‑investment, the addressable market expands meaningfully through the end of the forecast period at an aggregate CAGR of 6.61% — a signal that capacity investments and service innovation retain economic rationale.
- Concentration remains low-to-moderate. The market structure shows relatively modest share accumulation among top vendors; the CR3 sits below 20% and the CR5 is below 30%, indicating buyers can still drive competitive bids and negotiate differentiated value propositions.
- Regulation and commodity swings will re‑price economics rapidly. Policy moves in the EU and China, upstream resin price volatility, and labor cost inflation are the immediate levers that shift project IRRs and operational risk profiles — and therefore should inform 2026 capex and contract designs.
What the PW Consulting report delivers — practical, transaction‑ready intelligence
The report is structured to support the full lifecycle of commercial and capital decisions: from initial market screening through bid playbooks and post‑commissioning optimization. Highlights include:
Worldwide Materials Recovery Facility (MRF) Market
- High‑fidelity market sizing and trend mapping calibrated to a 2025 base year and forward forecasts through 2032, with scenario branches for near-term regulatory accelerations and commodity‑price shocks.
- Actionable go‑to‑market playbooks for technology suppliers, EPC contractors, financiers and municipal buyers — including procurement templates, vendor scorecards and OPEX/CAPEX sensitivity matrices.
- Project-level financial models and benchmarking tools that allow teams to stress‑test plant configurations and automation mixes under varying feedstock quality and wage assumptions.
- Technology deep dives: sensor‑based optical sorters, AI and robotic pick‑and‑place, ballistic separators, shredding/crushing modules and modular plant architectures — with risk/benefit matrices and adoption curves to inform equipment selection.
- Regulatory and policy trackers that map near‑term enforcement timelines (notably EU separate collection mandates and tightened import rules in China) to regional capacity needs and funding windows.
- Scenario playbooks for M&A and partnership strategies, including value creation levers for bolt‑on acquisitions, JV structuring, and aftermarket service monetization.
Competitive landscape — capabilities, moves and what they imply for procurement
The report profiles the major system integrators, equipment specialists and turnkey providers who will shape procurement outcomes in 2026. Leading companies are advancing differentiated plays:
- CP Group (Netherlands) continues to build scale in turnkey MRF projects and has signaled capacity expansion with new high‑throughput installations, strengthening its appeal for large municipal and corporate clients seeking end‑to‑end delivery.
- Tomra (Norway) remains the technology front‑runner on sensor‑based sorting. Its latest sensor platform launched in late 2025 boosts plastic recovery rates and will catalyze retrofit activity among existing MRFs seeking near‑term yield uplifts.
- Bulk Handling Systems (United States) is combining AI robotics and robust engineering for high‑volume single‑ and dual‑stream facilities, and recent certification upgrades improve its value proposition to buyers requiring certified automation performance.
- Metso (Finland), Machinex (Canada), STADLER (Austria), Van Dyk (Netherlands) and Eggersmann (Germany) are pursuing complementary strategies across modular systems, ballistic separation, and specialized shredding/screening — creating distinct supplier archetypes for different project scales and feedstock mixes.
Recent vendor developments — new product launches, capacity additions and contract awards — are concentrated in automation and throughput scale. Buyers moving to 2026 procurements should expect intensified competition around integrated performance guarantees (recoveries, contamination rates and uptime) rather than pure equipment pricing.
Macro and operational tailwinds (and headwinds)
Our study synthesizes the key external drivers that will influence project economics in 2026:
- Regulatory enforcement: Implementation of separate collection mandates in the EU and stricter domestic waste processing rules in China are expanding the pipeline for MRF projects and accelerating retrofit demand.
- Commodity and feedstock price volatility: Recent increases in HDPE resin prices have raised the immediate value of recovered streams but also amplified volatility in revenue assumptions for recycling plants.
- Labor and OPEX pressures: Rising wage baselines in mature markets are increasing the attractiveness of automation and service‑based outsourcing models.
- Public funding windows: Significant grant programs and infrastructure funds (including finalized recycling infrastructure grants in the U.S.) create narrow procurement timing windows where public projects offer improved financial support.
Strategic implications — six priorities for 2026
For executives evaluating MRF investments or partnerships next year, PW Consulting recommends focusing on six priorities that balance value capture and risk mitigation:
- Time procurement to funding cycles: Align RFPs and financing close with identified public and private grant disbursement windows to reduce equity needs and improve project IRRs.
- Prioritize modularity and retrofittability: Choose equipment and plant architectures that allow phased automation upgrades and technology swaps as sensors and AI evolve.
- Design revenue models for commodity volatility: Use conservative commodity assumptions, indexed contracts, and blended revenue streams (processing fees, commodity sales, services) to stabilize cash flows.
- Negotiate performance‑based takeaways: Shift risk to vendors through recovery and contamination guarantees, combined with short technical milestones and liquidated damages calibrated to actual loss metrics.
- Opt for partnership models with specialist operators: Where labor costs and regulatory complexity are high, JV or concession structures with experienced operators reduce operational risk and accelerate ramp‑up.
- Embed circularity KPIs in procurement: Require traceability and end‑market certifications for recovered outputs to protect long‑term value and access to premium buyers.
How PW Consulting’s deliverables accelerate implementation
Our report goes beyond market narrative to provide executable instruments: bid evaluation templates, vendor scorecards with competency frameworks, full financial models with sensitivity toggles, and a prioritized project pipeline by funding availability and regulatory urgency. These deliverables are designed so teams can convert strategy into procurement and commissioning roadmaps within 90–180 days.
Keeping the core data secure — why you’ll need the full report
This press preview demonstrates the strategic shape of the MRF market and the decision levers that matter in 2026, but it intentionally omits granular segment tables, region‑by‑region forecasts and vendor scorecard weightings. Those detailed datasets — including equipment‑level cost curves, segmented demand drivers, and project-level IRR bandings — are included in the full PW Consulting report and the downloadable financial model available through our website. These datasets are essential for transaction due diligence, bid construction and precise CAPEX planning.
About PW Consulting
PW Consulting is a global strategy advisory firm specializing in industrial infrastructure and circular economy investments. Our UK‑ and US‑based teams combine engineering, commercial diligence and public policy expertise to produce decision‑grade research and transaction support. The MRF market study reflects primary interviews with operators and vendors, proprietary project benchmarking, and scenario modeling calibrated to 2025 market realities.
To request the full report, schedule a briefing with our MRF practice, or obtain the financial model for your internal analysis, please visit our official report page on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Materials Recovery Facility (MRF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com