

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Negative Ion Cyclotron Market Poised to Reach USD 646.16 Million by 2032, New Insight Report Says

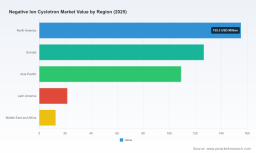
Worldwide Negative Ion Cyclotron Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As healthcare systems, industrial research facilities, and national isotope programs approach a new phase of capital investment, PW Consulting’s latest market study on the Worldwide Negative Ion Cyclotron Market delivers the strategic intelligence required to make high‑confidence decisions in 2026. The market reached an estimated USD 425.5 Million in our base year (2025) and the sector is projected to expand at a compound annual growth rate (CAGR) of 6.15% across the 2026–2032 forecast window. Market structure is concentrated: the leading three suppliers capture roughly two‑thirds of industry revenue, and the five largest vendors control the large majority of accessible demand. Against this backdrop, the report frames near‑term growth drivers, technological chokepoints, regulatory inflection points, and actionable responses for equipment OEMs, hospital systems, investors, and national program planners.
Worldwide Negative Ion Cyclotron Market
Why this matters for 2026 strategic planning
2026 will be a make‑or‑break year for many capital projects and supply‑chain realignments in the radiopharmaceutical and particle therapy ecosystems. Decision cycles for cyclotron procurement, facility design, regulatory clearance, and financing commonly span 12–36 months. A nuanced understanding of market momentum, vendor positioning, and the technical constraints that determine throughput and operational cost is therefore essential. Our study synthesizes historical performance (2020–2025) with forward projections (2026–2032) to convert macro momentum into programmatic recommendations — from timing capex to structuring supplier agreements and prioritizing R&D investments.
Worldwide Negative Ion Cyclotron Market
What the report contains: practical, deployable intelligence
- Primary market sizing and evolution: validated market totals and growth trajectories, with scenario modeling to stress‑test investment returns under conservative, base, and upside adoption paths.
- Operator economics: build vs. buy models for in‑house isotope production, utilization thresholds for payback, and sensitivity to isotope yield and downtime.
- Procurement playbook: RFP templates, critical technical specifications, acceptance testing checklists, and contractual clauses to mitigate delivery and performance risk.
- Regulatory and compliance map: clear paths to alignment with international frameworks (radiation protection, medical device classification, export control) and recommended documentation workflows to accelerate approvals.
- Technology and operations roadmap: prioritized areas for incremental improvements (ion source reliability, RF efficiency, vacuum integrity) and a timeline for when technology shifts will materially change unit economics.
- Strategic M&A and partnership toolbox: criteria for bolt‑on acquisitions, JV structuring guidance for market entry, and due‑diligence checklists tailored to cyclotron assets and service capabilities.
Market sizing and structure: what the headline numbers imply
The headline market figure and the 6.15% CAGR convey two important strategic signals. First, demand is supportive of continued vendor investment in service networks and product line extensions — not a fleeting niche. Second, growth is sufficiently steady to justify multi‑year R&D programs focused on reliability and throughput rather than one‑off capacity expansions. The concentration data underscores another reality: established incumbent vendors retain structural advantages in distribution, regulatory track record, and installed base servicing. New entrants or diversification strategies therefore require either a distinctive technology advantage or a go‑to‑market partnership that accelerates credibility.
Worldwide Negative Ion Cyclotron Market
Competitive landscape: who shapes supply and why that matters
The sector’s competitive map is dominated by a small group of companies with deep clinical and industrial track records. Leading European and North American OEMs offer mature product families spanning low‑ to high‑energy negative ion cyclotrons tailored for PET isotope production and select therapeutic isotopes. Notable recent developments illustrate incumbent momentum: a major European supplier expanded high‑energy capacity through strategic orders and installations in 2023, while established North American players continued to place mid‑range systems in expanding PET facilities across Europe and Asia.
What this means for buyers and investors:
- Vendor selection increasingly hinges on lifecycle service capability — downtime penalties from supply interruptions are a leading driver of total cost of ownership.
- Scale matters for regulatory support: suppliers with multiple installations in similar regulatory jurisdictions accelerate site approvals and acceptance testing.
- Technology parity in base performance places a premium on after‑sales services, consumable logistics, and local training programs.
Regulation, export control and standards — strategic constraints & enablers
Regulatory and export regimes are not background noise; they shape project feasibility, cost, and timing. Medical cyclotrons are subject to rigorous safety and device regulation frameworks. For radiation protection and facility design, international standards provide baseline requirements that influence shielding, layout, and operating procedures. Under prevailing European medical device regulations, relevant equipment classifications and quality standards necessitate documented QMS processes that vendors and buyers must demonstrate during procurement and commissioning. Separately, high‑energy systems face export licensing regimes where national and multilateral controls can delay cross‑border transactions. In short, regulation is a strategic input to procurement timelines and partnership choices, and our report provides a decision matrix for navigating these constraints.
Technical chokepoints and R&D priorities
Two technical realities constrain scaling and define near‑term R&D priorities. First, negative hydrogen (H‑) ion sources in commercial cyclotrons are practically limited in beam current by space‑charge effects and extraction efficiency; the industry currently operates within a constrained current envelope. Second, stable operation requires significant RF drive and ultra‑high vacuum systems — facility designs typically provision for multi‑hundred kilowatt RF systems and vacuum levels in the ultra‑high range to avoid beam loss and component degradation. These engineering limits translate into predictable performance ceilings for isotope yield and operating cost.
For executives allocating R&D budgets, the strategic choices are clear:
- Invest in incremental improvements to ion source lifetime and extraction efficiency — these yield direct improvements in throughput without requiring a step change in facility footprint.
- Optimize RF subsystem efficiency and thermal management to lower operating expense and reduce infrastructure demand.
- Develop system‑level diagnostics and predictive maintenance software to increase uptime and accelerate mean time to repair.
Operational and supply‑chain considerations
Facility operators and integrators must plan for significant utility and environmental controls. RF power provisioning, stringent vacuum systems, and radiation shielding are non‑negotiable design elements that affect capital expenditure and site selection. Consumable supply — targets, windows, ion source parts — and access to qualified service engineers are recurring drivers of operational resilience. The report supplies a practical supplier mapping and lead‑time matrix to align purchasing schedules with project milestones, reducing the risk of commissioning delays.
Strategic recommendations for 2026 action
Pushing strategy from insight to action, the report advances a prioritized list of measures for stakeholders preparing decisions in 2026:
- Buyers (hospitals, research consortia): initiate procurement processes with 18–24 month lead times; prioritize vendors with regional service hubs and demonstrated regulatory dossiers in your jurisdiction.
- OEMs: focus R&D on reliability and serviceability; consider modular service contracts and localized consumable supply agreements to lock in recurring revenue.
- Investors and private equity: target platform plays that combine manufacturing competence with strong service networks; consider roll‑up strategies that add regional service centers to bolt‑on cyclotron businesses.
- Policymakers and program planners: align grant and procurement windows with realistic export and licensing timelines; prioritize investments that reduce dependency on cross‑border isotope supply.
Risk factors and mitigation
Key risks include export licensing delays for high‑energy systems, supplier concentration exposing buyers to single‑point service risk, and the slower‑than‑expected pace of clinical adoption for new isotopes that could suppress upper‑end forecasts. The report includes scenario playbooks and contract templates that mitigate these exposures — for example, preferred supplier agreements with explicit uptime guarantees, contingency plans for target and consumable shortages, and staged procurement tied to milestone payments.
How to use this report now
The published study functions as both a strategic primer and an execution manual. It is organized so that executives can quickly extract board‑level implications, procurement managers can operationalize the procurement playbook, and technical teams can access prioritized R&D roadmaps. Importantly, while this summary surfaces the report’s principal conclusions and the strategic value it delivers for 2026 decision cycles, detailed segment breakouts, regional and application split tables, and vendor‑level quantitative metrics are reserved for the full study to preserve the integrity of proprietary analyses and to guide readers to the source for complete data.
Next steps
If your organization is preparing capital budgets, structuring a market entry, or evaluating acquisition targets in the negative ion cyclotron space, the PW Consulting report is designed to accelerate your critical path to decision. The full dossier includes executable tools — from RFP templates to service‑level KPIs and scenario financial models — that convert insight into deliverable outcomes. For access to the full study and the proprietary datasets, follow the link provided by our release distribution.
Closing note from PW Consulting
Negative ion cyclotrons occupy a unique intersection of medical value, industrial utility, and strategic supply importance. The market’s steady growth and concentrated vendor landscape create both opportunity and constraint. Our analysis equips leaders with the context and instruments to convert market trends into robust 2026 strategies while avoiding common operational, regulatory, and technology traps. PW Consulting remains available to brief executive teams, run tailored procurement workshops, and support transaction diligence informed by the findings of this study.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com