

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide System on Module Boards Market to Grow at a 11.45% CAGR from 2026 to 2032

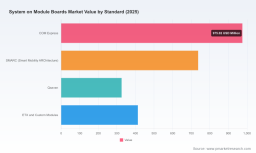
Worldwide System on Module (SoM) Boards Market — Strategic Outlook to 2032
PW Consulting today publishes a focused strategic brief drawn from our new market research, Worldwide System on Module Boards Market (base year 2025, forecast 2026–2032). The SoM market has moved beyond niche embedded projects to become a mainstream platform strategy for industrial automation, edge AI, medical devices, transportation and other mission-critical systems. Our analysis shows the market expanding at a sustained compound annual growth rate (CAGR) of 11.45% from the 2025 base, with global revenue growing from USD 1,420.2 Million in 2020 to USD 2,450.5 Million in 2025 and a projected USD 5,233.78 Million by 2032. This trajectory presents both an opportunity and a set of operational and strategic imperatives for 2026 decision-makers.
Worldwide System on Module Boards Market
Why this matters for 2026 decision cycles
-
Design-to-deployment cadence: SoMs reduce time-to-market for complex embedded solutions, but they also alter supplier relationships and technical debt profiles. Companies making architecture choices in 2026 will lock in multi-year platform dependencies.
Worldwide System on Module Boards Market -
Supply chain resilience: The SoM value chain is sensitive to semiconductor policy, tariffs and critical material price swings. Procurement and engineering teams must adopt integrated sourcing-and-design strategies to avoid costly redesigns or production delays.
Worldwide System on Module Boards Market -
Value capture and differentiation: As the overall market doubles over the next decade, differentiation will shift from raw processing power toward software, integration services and long-term lifecycle support—areas where OEMs can capture margin or cede it to module suppliers.
What the report delivers — practical, transaction-ready intelligence
-
Market sizing and multi-scenario forecasts (2020–2032) with baseline, upside and downside paths linked to semiconductor supply, regulatory shifts and adoption of edge AI workloads.
-
Architecture and standards analysis mapping (ARM, x86, FPGA/PowerPC and the leading module standards) that explains trade-offs in performance-per-watt, certification complexity, longevity and ecosystem support.
-
Supplier scorecards and a competitive playbook that combine technical roadmaps, product maturity, geographic manufacturing footprints and partner ecosystems to support vendor selection and negotiation.
-
Hands-on deployment playbooks: BOM sensitivity models, lead-time mitigation templates, version-control and EOL migration plans to protect program timelines and margins.
-
Regulatory and trade impact assessment including scenario mapping for export controls, tariffs and localization incentives—translated into quantitative risk factors for procurement and R&D planning.
-
M&A and partnership heatmaps identifying adjacencies, bolt-on targets and co-development opportunities across regions and end-markets.
Competitive landscape — who matters and why
The SoM supplier ecosystem is diverse, with specialist vendors driving innovation alongside established embedded systems houses. Our report profiles the full competitive set and provides actionable intelligence on go-to-commercial strategies. Highlights:
-
Toradex (Horw, Switzerland) — a market leader in rugged, industrial-grade modules (Verdin, Colibri, Apalis) leveraging NXP, TI and Renesas families; strong in long-life and support for industrial deployments.
-
Variscite (Yokneam, Israel) — focused on compact DART and VAR-SOM lines for IoT and edge compute, with an emphasis on fast time-to-market and custom engineering support.
-
Kontron (Augsburg, Germany) — a systems integrator offering modules across SMARC, Qseven and COM Express standards with broad ruggedization and certification capabilities for industrial and transportation segments.
-
Advantech (Taipei, Taiwan) — strong portfolio for industrial automation and medical applications, combining SoMs and carrier boards with global manufacturing and field service.
-
Phytec (Mainz, Germany) — known for automotive- and avionics-oriented SoMs, with recent product introductions targeting ADAS and machine vision applications.
-
Compulab, Gateworks, TechNexion, MYIR Tech, Forlinx Embedded Technology, AAEON, IEI Integration Corp and Seco — each bringing regional strengths, specific processor optimizations and differentiated value in verticals such as defense, outdoor wireless, AI vision and HMI.
Recent commercial and product activity underlines the market’s technical momentum: leading vendors have been qualifying SoMs with next-generation application processors, launching modules tailored for edge AI, and ramping production to meet demand for higher compute density at the edge. These moves shorten development cycles for customers but raise the bar on lifecycle and compatibility management.
Market structure and concentration — what to expect
The market remains moderately consolidated: a handful of suppliers capture a notable share of industry revenue while a long tail of regional specialists serves niche verticals. This structure favors strategic partnerships for scale but leaves room for focused entrants that offer differentiated software, service-level agreements or regulatory certification expertise. For procurement teams, the implication is clear—vendor selection must balance performance, long-term support and geopolitical exposure.
Supply-chain and policy dynamics that will shape 2026 decisions
-
Policy levers: Initiatives such as the EU Chips Act are accelerating upstream capacity investments that can ease component constraints by the end of the decade. Conversely, export control regimes and targeted tariffs can quickly reroute sourcing options and raise the total landed cost for sensitive modules or components.
-
Component lead times and availability: Our analysis detects improving lead-time metrics for many mainstream SoC families compared with peak disruption years; however, lead times remain volatile for high-end SoCs and certain specialty components, necessitating multi-sourcing and design flexibility.
-
Input-cost risk: Price movements in critical raw materials (e.g., gallium for GaN components) have meaningful margin and design implications for power-efficient SoMs. Expect engineering trade-offs between power budgets and bill-of-materials economics to intensify.
-
Trade friction and manufacturing footprint decisions: Tariffs and export rules are driving increased interest in regional assembly and qualification, especially for regulated end-markets such as medical and defense.
Actionable strategic recommendations for 2026
-
Run a supplier-risk and architecture alignment audit within 90 days. Map your product roadmaps to supplier lifecycles and identify single points of failure, particularly around high-dependency SoCs and specialized modules.
-
Adopt a “design-for-supply” discipline. Treat SoM selection as a supply chain decision as much as an engineering one: require suppliers to deliver lifecycle, long-term availability commitments and clearly defined EOL pathways.
-
Prioritize modularity and standard-based migration paths. Where product form factors allow, choose standardized module families to enable future CPU swaps without full carrier redesigns.
-
Lock in price and lead-time hedges for critical components when justified. Use staged purchasing and buffer strategies to smooth production spikes while keeping inventory economics under control.
-
Engage in strategic co-development or exclusivity for differentiating features (security, safety certification, custom ISP or accelerators) to preserve product differentiation as raw compute becomes commoditized.
-
Prepare regulatory scenarios. Integrate export-control and tariff scenarios into project financials and supplier scorecards; consider regional qualification tracks where regulation or tariffs materially change TCO.
-
Scan for bolt-on assets and technology partnerships. Given market growth and consolidation dynamics, acquisitions or minority investments in specialized SoM vendors can accelerate entry into new verticals or geographies.
How PW Consulting supports your 2026 roadmap
Our report is designed as a near-term operational playbook and a medium-term strategic roadmap. Key deliverables include an interactive forecasting model (2020–2032), supplier scorecards with objective KPIs, BOM sensitivity tools, regulatory impact scenarios and templates for procurement contracts and lifecycle migration. For product leaders, the report provides a playbook that translates market growth into concrete program-level decisions; for corporate strategy teams, it surfaces M&A and partnership opportunities aligned with demand trajectories and regional policy shifts.
This summary intentionally omits granular segment-by-segment figures and certain proprietary scorecard metrics to preserve the value of the full dataset. The complete report contains detailed segmentation by architecture, standard, application and region, along with vendor market shares, price-by-configuration benchmarks and downloadable models for use in R&D, procurement and corporate planning.
Next steps
For teams making architecture, sourcing or M&A decisions in 2026, the clock is already ticking. Use our dataset and playbooks to stress-test your product plans against supply volatility, regulatory scenarios and the fast-evolving competitive landscape. To access the full analysis, detailed segment breakdowns and the downloadable forecasting model, please visit PW Consulting’s report page and request access to Worldwide System on Module Boards Market — 2025 Edition.
PW Consulting — actionable industry insight to turn market growth into decisive competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide System on Module Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com