

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Surgical Tray Market Valued at USD 540.2 Million in 2025, Set for Robust Expansion

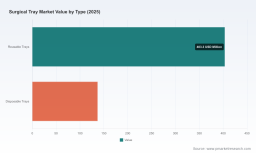
Worldwide Surgical Tray Market 2026: Strategic Imperatives from PW Consulting
PW Consulting today publishes its latest Worldwide Surgical Tray Market report — an executive-grade toolkit designed to inform boardroom decisions in 2026 and beyond. Built on a verified historical series (2020–2025) and a seven‑year forecast (2026–2032), the study models market trajectories under multiple scenarios and quantifies the operational levers that will determine winner/loser outcomes across suppliers, providers, and investors. The market demonstrates resilient expansion: from a measured base in 2020 through a 2025 base year of USD 540.2 Million, the sector is projected to grow at a 5.81% compound annual growth rate under our baseline assumptions, reaching an estimated USD 801.6 Million by 2032. These headline metrics set the context for targeted 2026 strategy.
Worldwide Surgical Tray Market
Why this report matters for 2026 decision-makers
-
Actionable foresight for procurement: rapid shifts in purchasing models, sterilization protocols, and sustainability standards mean procurement teams need forward-looking TCO tools, supplier scorecards, and contract playbooks to lock in performance and margin protection.
Worldwide Surgical Tray Market -
Product and R&D prioritization: manufacturers must decide where to allocate limited R&D budgets between modular reusable systems, single‑use disposables, and hybrid product lines that improve sterilization throughput and reduce lifecycle costs.
Worldwide Surgical Tray Market -
M&A and corporate development: private equity and strategic acquirers need granular risk-adjusted deal valuations that account for sterilization compliance, concentration dynamics, and supplier concentration across hospital systems and ambulatory settings.
-
Operations and capital planning: hospitals and central sterile processing (CSPD) managers require capital planning scenarios that align tray inventories, cleaning load, and instrument turnover with epidemiology-driven case mix changes.
What the PW Consulting report delivers (operationally focused)
-
Executive dashboard: concise KPIs, baseline and stress forecasts, and a five‑year opportunity map linking strategic moves to profit and service outcomes.
-
Market sizing and methodology annex: transparent modeling assumptions, data sources, and a downloadable Excel model that lets you run your own sensitivity analyses against price, utilization, and sterilization costs.
-
Scenario-based forecasts: baseline (policy-stable), upside (accelerated ambulatory shift and sustainability adoption), and downside (supply shock or regulatory tightening) projections with decision triggers mapped to each.
-
Competitive playbook: supplier scorecards, win/loss themes, contract levers, and product differentiation matrices to inform procurement negotiation and product roadmaps.
-
Sterilization and regulatory playbook: step‑by‑step requirements for ISO 17665-1 validation, FDA 510(k) pathways for instrument trays, and implementation checklists to satisfy AAMI ST79 cleaning thresholds.
-
Supply‑chain risk matrix: raw material sensitivity analysis (including medical‑grade 316L stainless steel input cost dynamics), nearshoring options, and supplier contingency playbooks.
-
M&A and partnership framework: target screening criteria, valuation sensitivities tied to product mix, and integration playbooks for manufacturers and service providers.
-
Implementation tools: SKU rationalization templates, procurement RFP language, sterilization validation templates, and a hospital CSPD benchmark toolkit.
Market dynamics shaping 2026 strategy
The surgical tray market sits at the intersection of clinical demand, sterilization science, and procurement economics. Three dynamics will dominate near‑term strategy:
-
Clinical throughput and site-of-care migration. Continued movement of appropriate cases to ambulatory surgical centers and specialty clinics pressures tray volumes and encourages modular, easy‑to‑clean systems that reduce turnaround time.
-
Regulatory and sterilization rigor. Compliance with ISO 17665-1 for moist‑heat sterilization validation, the practical implications of FDA device classification pathways, and adherence to AAMI ST79 cleaning protocols impose both time and cost on manufacturers and providers. Hospitals that invest early in validated cleaning processes reduce bioburden risk and may realize lower lifecycle costs despite upfront capital spend.
-
Cost and material sensitivity. Raw material inputs — notably medical‑grade 316L stainless steel — represent a predictable but non‑trivial component of product cost; industry references currently put market pricing in a narrow band that materially affects manufacturer margins and pricing elasticity. Manufacturers that optimize material use, or substitute appropriately where clinical guidelines allow, will gain cost advantage.
Market concentration is meaningful but not prohibitive: the top three firms account for a sizeable share of the sector, and the top five further consolidate influence, leaving room for niche specialists and regional innovators to capture adjacencies or to be attractive acquisition targets.
Competitive landscape — what the main players reveal about industry direction
-
Cardinal Health, Inc. (Dublin, Ohio) — a global leader in custom sterile procedure trays. Cardinal’s multi‑year contracting activity with large hospital systems illustrates a strategy centered on scale, customization, and integrated supply solutions. For buyers, Cardinal remains a benchmark for contract design and value‑added services.
-
Medline Industries, LP (Northfield, Illinois) — a vertically integrated manufacturer of both reusable stainless steel and disposable plastic trays. Medline’s catalog expansions demonstrate a product design focus on modularity and clinician ergonomics; competitors should expect continued investment in fit‑for‑purpose tray sets and supply chain resilience.
-
B. Braun Melsungen AG (Melsungen, Germany) — emphasizes modular stainless steel containers engineered for steam and EO sterilization, signaling demand for durable solutions that integrate with CSPD workflows.
-
Steris plc (Dublin, Ohio) — with recent product innovation in rigid container systems designed to improve sterilization efficiency, Steris is positioning at the intersection of equipment and consumable solutions, creating cross‑sell opportunities into hospital sterile processing departments.
-
Teleflex Incorporated (Wayne, Pennsylvania) — through the Pilling brand, Teleflex focuses on specialty configurations (perforated and solid bottoms) serving instrument-specific needs, a reminder that product differentiation remains a viable strategy.
-
Integra LifeSciences (Princeton, New Jersey) — a niche player in neurosurgery and orthopedics, demonstrating that clinical specialization and instrument ecosystem coherence can create defensible margins in targeted segments.
-
Becton, Dickinson and Company (BD) (Franklin Lakes, New Jersey) — integrates tray solutions within broader procedural kits, underscoring the value of bundling and device ecosystems for customers seeking one‑stop procurement.
-
Mölnlycke Health Care AB (Gothenburg, Sweden) — focuses on custom procedure trays for wound care and general surgery, reflecting demand for tailored solutions with strong clinical support and hygiene credentials.
Recent product launches, catalog expansions, and supply agreements reflect three parallel strategic plays: (1) deepen relationships with large hospital systems through bespoke contracting and service bundling; (2) invest in sterilization‑efficient container systems that reduce CSPD cycle time; and (3) expand product families toward modularity and clinical specificity.
Strategic recommendations for executives in 2026
-
Procurement and hospital systems: adopt a dual‑track sourcing strategy — secure core capacity with established global suppliers while cultivating niche suppliers for clinical specialties. Insist on sterilization validation data and include service-level KPIs tied to CSPD turnaround and instrument availability.
-
Manufacturers: prioritize modular, sterilization‑compatible designs and invest in life‑cycle cost modeling to demonstrate value over single‑use alternatives. Build rapid validation pathways for ISO 17665-1 and FDA 510(k) where applicable.
-
Investors and acquirers: focus diligence on sterilization compliance, CSPD adoption curves, and supplier concentration risk. Small to mid‑cap players with strong clinician relationships and flexible manufacturing can be high‑value targets.
-
Operations leaders: normalize investments in CSPD automation and validated cleaning protocols per AAMI ST79 — doing so reduces infection risk and unlocks tray reuse opportunities that favor hospital economics.
-
Product development: accelerate features that improve sterilization throughput (venting, modular inserts, anti‑fog plating) and reduce lifecycle environmental footprint to capture sustainability-minded buyers.
-
Risk management: hedge raw‑material exposure through multi‑year supply commitments or strategic local sourcing. Embed contract clauses that allow for pass‑through of material cost spikes tied to transparent indices.
How PW Consulting supports 2026 execution
We pair the report’s downloadable models with advisory services that include supplier benchmarking, procurement RFP execution, M&A transaction support, and pilot design for tray reconfiguration or CSPD upgrades. Our engagements are structured to move from strategy to measurable implementation within a 6–12 month horizon, delivering the governance, KPIs, and playbooks necessary to convert insight into margin and service improvement.
PW Consulting’s Worldwide Surgical Tray Market report provides the strategic context and operational tools required to make high‑confidence decisions in 2026 — from contract negotiations and product roadmaps to M&A playbooks and CSPD investments. For the full dataset, granular segmentation, and downloadable Excel models that contain regional, type, and end‑user splits, please visit our report landing page or contact PW Consulting for an executive briefing and licensing of the underlying data.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com