

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide LAG3 Antibody Market Poised for 26.79% CAGR, Expected to Reach USD 6,950 Million by 2032 as North America Tops USD 792.48 Million in 2025

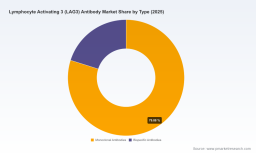
Worldwide LAG‑3 Antibody Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
The Worldwide Lymphocyte Activating 3 (LAG‑3) antibody market is transitioning from a clinical curiosity into a commercially meaningful oncology modality. PW Consulting’s new report (base year 2025, forecast 2026–2032) projects a high‑growth trajectory underpinned by a compound annual growth rate (CAGR) of 26.79%. From a modest early‑stage market in 2020, our macro model shows expansion to a multi‑billion dollar opportunity by 2032 (reported in USD Million), driven by approvals, combination strategies with PD‑1/PD‑L1 therapies, and a robust pipeline of both monoclonal and multispecific constructs.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
This preview outlines the strategic value of our full report for executive teams making 2026 investment, portfolio and go‑to‑market decisions. We deliberately showcase analytical depth and actionable frameworks while reserving detailed segmentation tables, scenario spreadsheets and company‑level financials for the complete report available on PW Consulting’s website.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Why this matters for 2026 decision‑makers
-
Rapid market scaling: Our topline market model illustrates very steep growth from the mid‑teens low‑hundreds of millions in the early 2020s to a large single‑digit billion market by the end of the forecast, reflecting both uptake of approved products and conversion of multiple late‑stage programs into commercial launches.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market -
Concentrated competitive structure: Market concentration is high — the top three players control the vast majority of commercial LAG‑3 revenues, and the top five firms dominate nearly the entire market. This structural reality shapes pricing power, access dynamics and partnership opportunity sets.
-
Regulatory and reimbursement inflection points: With the first FDA approval of a LAG‑3 blocking antibody combination already establishing clinical precedent, the next 18–36 months will be decisive in setting label, reimbursement and guideline adoption patterns that will either accelerate or constrain market uptake.
Market dynamics — what the macro numbers tell us
PW Consulting’s baseline estimates for 2025 reflect a market that has achieved commercial scale and payer attention. When combined with our 2026–2032 forecast (26.79% CAGR), the numbers indicate that strategic investments made in 2026 — whether in late‑stage assets, manufacturing capacity, or commercialization infrastructure — will capture a disproportionate share of the value created over the next seven years.
Key dynamics captured in our analysis include: clinical differentiation between single‑target monoclonals, bispecific modalities, and non‑traditional LAG‑3 constructs; the centrality of PD‑1 combination strategies; regulatory momentum centered on the inaugural approved combination; and a manufacturing and supply chain profile that, while subject to the usual biologics challenges, does not currently show LAG‑3‑specific raw material bottlenecks in major markets.
What the full report contains — practical, transaction‑ready intelligence
-
Quantitative market model (2020–2032) with base, upside and downside scenarios, delivered in editable spreadsheet format. The model lets users test assumptions on clinical success rates, time‑to‑launch, price realization and market access to generate bespoke NPV and ROI outputs.
-
Pipeline and clinical risk mapping for all active LAG‑3 programs, including modality classification (monoclonal, bispecific, fusion protein, agonist), mechanism‑based competitive overlaps and program‑level probability of success assumptions.
-
Regulatory & reimbursement playbook that synthesizes precedent approvals, label dynamics, expected HTA review timelines in major markets, and payer negotiation levers specific to fixed‑dose checkpoint combinations.
-
Commercial launch readiness checklists and go‑to‑market options tailored for incumbents, late entrant biotechs and potential acquirers — including field force design, digital engagement frameworks, and patient support models.
-
Manufacturing, CMC and supply chain stress tests identifying capacity risk, CMO selection criteria, cost‑of‑goods sensitivities and points of failure that materially affect gross margins under different volume scenarios.
-
M&A and licensing decision support: valuation benchmarking, deal structuring templates, and a prioritized list of bolt‑on and platform targets aligned to strategic arcs (e.g., bispecific acceleration, autoimmune indications, manufacturing scale).
-
Competitive intelligence dossiers on leading developers, with strategic SWOTs, recent clinical milestones and an assessment of likely commercialization pathways.
Competitive landscape — players to watch and strategic positioning
The LAG‑3 competitive set includes large pharma, oncology specialty biotechs, and modular antibody platform companies. Each type of player brings distinct strategic options and constraints:
-
Bristol Myers Squibb (BMS) — As the commercial originator, BMS’s combination product established regulatory and clinical precedent. Recent trial outcomes have introduced new complexity into label extension and lifecycle planning. BMS’s choices around follow‑on indications, combination strategies and competitive defense will materially influence the commercial runway for competitors.
-
Regeneron (with strategic partner activity) — Regeneron’s late‑stage monoclonal program positions it as a near‑term challenger in the checkpoint combination space. Their clinical design emphasis, partnership model and development cadence will determine whether they contest BMS in labeled indications or pursue niche positioning.
-
Large pharmas with prior LAG‑3 investments (Merck, Novartis, Roche) — These firms bring deep commercialization muscle and are likely to compete through differentiated clinical development strategies, either pursuing broad label expansion or focusing on specific tumor types and biomarker populations.
-
Specialty biotechs and platform companies (MacroGenics, Xencor, Incyte, F‑star, Immutep) — These firms are advancing bispecifics, fusion proteins and agonist approaches that could reframe the value proposition of LAG‑3 modulation beyond oncology into autoimmune indications. Their strategic options include partnering, carve‑outs of specific assets, or leveraging bispecific IP to capture premium pricing.
-
Partnership dynamics (e.g., Sanofi collaborating on Regeneron programs) — Collaborative development models will continue to be the predominant route for sharing clinical risk and aligning commercialization capabilities for global launches.
Notable near‑term development: a major Phase III recurrence‑free survival study of a marketed LAG‑3 combination did not meet its primary endpoint in adjuvant melanoma. That result has immediate strategic consequences: it tightens evidentiary thresholds for label extension, increases the premium on positive phase III readouts, and rebalances relative value between combination strategies and differentiated modality entrants.
Strategic implications and recommended actions for 2026
For executive teams contemplating investments, partnerships or launch plans in 2026, PW Consulting recommends prioritizing three parallel tracks:
-
De‑risk the clinical and commercial pathway. Re‑specify pivotal trial designs to prioritize clinically meaningful endpoints that payers and guideline committees will accept. Consider adaptive designs, biomarker‑enriched cohorts and earlier engagement with HTA bodies in priority jurisdictions.
-
Lock down manufacturing and CMC scalability. Early capital allocation to validated CMOs or in‑house capacity reduces time‑to‑supply and protects margin potential during rapid uptake phases. Run cost‑of‑goods sensitivity analyses against multiple launch and uptake scenarios.
-
Define a differentiated commercial architecture. Whether pursuing PD‑1 combination parity or bispecific superiority, build a go‑to‑market plan that integrates value demonstration, payer evidence generation and targeted field force deployment to maximize share of voice in oncology segments with the highest therapeutic need.
Additional, tangible near‑term actions include: commissioning indication‑level real‑world evidence programs to support label expansions; negotiating staged licensing deals that share regulatory upside; and conducting focused M&A diligence on platform companies whose bispecific or fusion‑protein technologies can accelerate differentiation.
PW Consulting methodology and what you will get
The full report combines primary interviews with oncology KOLs, payer and HTA reviewers, anonymized investor diligence, and proprietary forecasting models calibrated to historical adoption curves for checkpoint inhibitors. All assumptions are transparently documented and delivered with editable scenario models so clients can rebase forecasts to their internal views.
We intentionally withhold granular segmentation tables and company‑level revenue lines in this preview to protect proprietary insight and to ensure the full analytical work product is accessed through the report portal. The full deliverable contains the actionable tables, heat maps and deal‑ready slides that corporate development, commercial and clinical teams use to operationalize strategy in 2026.
Conclusion — what to do next
The LAG‑3 antibody market presents substantial upside over the 2026–2032 horizon, but realizing that upside requires disciplined choices in clinical design, manufacturing preparedness and commercialization differentiation. PW Consulting’s report turns macro projections and competitive signal noise into decision‑grade intelligence: scenario‑tested models, specific operational checklists and a prioritized list of strategic plays for incumbents, challengers and investors.
For leaders who need to convert 2026 strategy into executable plans — from in‑licensing and M&A to launch sequencing and payer evidence generation — the full report provides the playbook. Access the complete Worldwide LAG‑3 Antibody Market report and annexed financial models on PW Consulting’s website to obtain the detailed segmentation, scenario spreadsheets and company‑level assessments reserved for report subscribers.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com