

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Indirect Auto Finance Market Poised to Expand at a 6.85% CAGR Through 2032
By pmarketresearch, 2026-07-15
Indirect Auto Finance Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As companies set priorities for 2026, leaders in auto finance face a pivotal inflection point. PW Consulting’s new Indirect Auto Finance Market report — anchored on a 2025 base year, a 2020–2025 historical series, and a 2026–2032 forecast horizon — translates macro trends into executable choices. The market we model has expanded materially over the past half‑decade and, under our central case, continues to grow at a compounded annual growth rate of 6.85% through the forecast window. This briefing summarizes the report’s practical value for boardrooms and C‑suites while preserving the granular segment intelligence that we reserve for the full release.
Indirect Auto Finance Market
Why this report matters to 2026 decision-makers
-
Market momentum: After several years of accelerated expansion, indirect auto finance is entering a phase of more heterogeneous growth. Knowing the absolute market trajectory — and the pace implied by the 6.85% CAGR — is essential for calibrating return hurdles, capital allocation, and product shelf sizes for the year ahead.
Indirect Auto Finance Market -
Regulatory inflection: The regulatory backdrop has shifted meaningfully into 2025–2026. Recent CFPB activity and legislative analysis have elevated compliance and supervisory risk for nonbank participants; firms must understand how regulatory thresholds and enforcement posture could affect business models, dealer relationships, and origination strategies.
Indirect Auto Finance Market -
Competitive repositioning: Our analysis shows that market concentration is meaningful but not prohibitive — with the three‑firm and five‑firm concentration metrics indicating room for both scale players and specialist entrants to prosper. That dynamic shapes M&A, partnership, and pricing strategies for 2026.
-
Operational resilience: Macroeconomic and credit cycles are creating asymmetric risks between new‑vehicle and used‑vehicle exposures, underwriting tiers, and dealer channels. The report converts these risks into prioritized investments in underwriting, dealer portal experience, and collections playbooks.
What the PW Consulting report delivers — operationally usable insights
-
Proprietary market sizing and trajectory: A full historical series (2020–2025) and a detailed forecast (2026–2032) that quantify the market’s evolution and provide scenario runs for downside stress and upside acceleration. These are modeled to support budgeting, balance‑sheet planning, and securitization shelf sizing.
-
Revenue and concentration metrics: We provide top‑line market measures and market concentration analytics to support strategic benchmarking, including CR3 and CR5 analysis to inform M&A appetite and pricing discipline.
-
Dealer channel diagnostics: Practical playbooks for optimizing indirect origination through franchise and independent dealerships, including dealer economics, funding cadence, and dealer portal best practices.
-
Regulatory & compliance toolkits: A structured assessment of current and prospective regulatory actions (including CFPB rulemaking trajectories and supervisory focus areas), with a compliance “to‑do” matrix for 2026 to reduce legal and remediation exposure.
-
Underwriting & pricing playbooks: Tactical scoring updates, vintage performance stress tests, and model re‑calibration guidance that translate observed behavioral shifts into rate card and collateral strategies.
-
Capital & funding scenarios: Funding stack playbooks, securitization readiness checklists, and sensitivity analyses tying interest‑rate paths and originator mix to funding cost and liquidity buffers.
-
Technology and vendor shortlists: Evaluated vendor options across dealer portals, e‑contracting, decisioning engines, and collections/portfolio management, with implementation roadmaps mapped to expected ROI horizons.
-
M&A and partnership thesis: A pragmatic framework for evaluating targets — from non‑prime specialists to bank players and captive finance divestitures — with valuation sensitivities and integration risk matrices.
Competitive landscape — what we see and what it means
Indirect channels remain the dominant origination route for auto lending. Our report profiles established captives, bank portfolios, and specialized finance companies, and draws strategic implications for each category. Major participants include leading bank lenders, independent finance companies, and captive arms of manufacturers — each following distinct playbooks:
-
Banks and large non‑captives: These institutions are leveraging scale, depositor funding advantages, and increasingly sophisticated digital dealer integrations to defend and expand indirect share. Their focus for 2026 will center on optimizing dealer economics and improving approval velocity without compromising credit discipline.
-
Captive finance companies: Manufacturer captives remain central to OEM go‑to‑market strategies, especially for purchase and lease programs that support sales targets. Captives will continue to deploy product bundles, loyalty incentives, and sales‑aligned programs to retain channel primacy.
-
Independent and specialty lenders: Niche players are exploiting underwriting sophistication and nonprime expertise to capture incremental volume. However, they face higher regulatory scrutiny and funding premia — forcing tradeoffs between growth and capital resiliency.
The report includes company‑level profiles and strategic assessment for the leading participants, distilled from public disclosures and proprietary interviews. For example, we examine how major non‑captives are reengineering dealer relationships, how captives are aligning product suites to lifecycle financing, and how independents are segmenting credit risk to sustain yields.
Regulatory and macro dynamics shaping 2026 choices
Regulation and macro forces are converging to shape the competitive calculus for next year:
-
Supervisory focus and rulemaking: Recent CFPB activity — including notice on large participant definitions and interpretive guidance affecting fair‑lending claims — requires firms to revisit sampling, fair‑lending controls, and adverse action processes. The report prescribes specific governance and remediation playbooks to reduce supervisory risk and potential enforcement costs.
-
Originations trend sensitivity: Industry sources point to a modest near‑term softening in overall originations driven by affordability pressures. PW Consulting models alternative origination trajectories and demonstrates how modest volume contractions materially affect unit economics, portfolio turnover, and liquidity needs.
-
Dealer finance dynamics: Growth in dealer‑finance debt and shifting party shares underscore the need to rethink dealer advance facilities, buy‑rate/mark‑up economics, and reconciliation practices to limit credit leakage.
Strategic imperatives and recommended actions for 2026
Based on our modeling and competitive analysis, PW Consulting recommends a prioritized set of actions for executives planning 2026 strategies:
-
Recalibrate dealer economics: Redesign dealer compensation and funding offers to reward volume that aligns with risk‑adjusted margins. Invest in dealer-facing digital tools that compress time‑to‑fund while increasing transparency.
-
Harden compliance posture: Implement a near‑term compliance sprint focused on fair‑lending controls, model governance, and originations reporting to prepare for heightened supervisory attention.
-
Stress‑test funding plans: Run alternative funding scenarios and securitization stress tests that incorporate both mild demand erosion and sudden spread widening to ensure liquidity resilience.
-
Targeted portfolio optimization: Use granular vintage analysis to reweight originations toward the most attractive risk/return cohorts, and consider selling or hedging stressed vintages where economics deteriorate.
-
Pursue selective partnerships: For firms lacking scale, partnering with established bank platforms or technology providers can accelerate capability builds with lower up‑front capital consumption than full build‑outs.
-
Prepare for M&A optionality: Given market concentration metrics, scalable acquirers should accelerate target screening and pre‑deal integration planning — and non‑scale players should develop defensive consolidation strategies.
Scenarios to prioritize in 2026 planning
Three scenarios in our forecast require board attention:
-
Base case (policy steady, demand modest growth): Continuation of current trajectories with moderate growth consistent with the modeled CAGR; management focus on execution and efficiency gains.
-
Downside (affordability shock): A near‑term contraction in originations driven by affordability pressures requires rapid redeployment of capital to preserve liquidity and margin‑enhancing originations.
-
Regulatory tightening: Elevated enforcement or new rules imposing higher compliance costs that compress returns and alter the economics of smaller originators.
Each scenario in the full report includes quantified P&L and balance‑sheet impacts and recommended tactical responses tied to timing horizons (0–6 months, 6–18 months, 18–36 months).
Final notes — the trailer approach
PW Consulting’s Indirect Auto Finance Market report is designed as a strategic decisioning tool for 2026. This briefing highlights the report’s actionable insights and strategic implications while intentionally withholding detailed segment and regional breakout figures. The detailed segment sizes, regional matrices, and per‑company benchmarking tables — along with our full financial models — are available in the report and the accompanying data annex.
If your team is preparing 2026 budgets, capital plans, regulatory remediation roadmaps, or M&A pipelines, the report will convert the market’s macro trajectory and competitive forces into operational moves. For boards and senior leadership teams, it provides the scenarios, diagnostic tools, and tactical playbooks necessary to preserve optionality while capturing profitable growth.
Contact PW Consulting to access the full Indirect Auto Finance Market report, including the granular segment data, competitive scorecards, and the downloadable Excel model that powers our forecasts and scenario analyses.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Face‑Voice Biometric Market Poised to Grow at 14% CAGR, Reaching USD 18.72 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Face-Voice Biometric Market — Strategic Briefing for 2026 Decisions
Executive summary
As identity systems converge around multi-modal biometric authentication, face-plus-voice solutions have moved from niche pilots to boardroom-level investment priorities. Our latest PW Consulting report shows the global face-voice biometric market reached approximately USD 7.5 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of about 14%, reaching roughly USD 18.7 billion by 2032. This trajectory reflects an inflection point: enterprises and public authorities are simultaneously responding to rising fraud, stricter regulatory regimes, and the operational need for seamless, privacy-aware authentication across digital and physical channels.
Worldwide Face Voice Biometric Market
Why this matters for strategy in 2026
-
Timing of investment: With a sustained double-digit CAGR, 2026 is a critical year to translate exploratory projects into scalable rollouts. Delaying decisions risks higher implementation costs and missed access to early-network benefits.
Worldwide Face Voice Biometric Market -
Portfolio prioritization: Organizations must choose between horizontal identity platforms and integrated vertical solutions for sectors such as finance, government, and healthcare. Our research identifies the decision levers—technical maturity, compliance readiness, data governance models, and total cost of ownership—that separate successful pilots from enterprise deployments.
Worldwide Face Voice Biometric Market -
Competitive differentiation: Early adopters that pair biometric authentication with user experience improvements and fraud analytics can convert security investments into measurable revenue protection and customer retention advantages.
Market trajectory and the forces shaping growth
The market’s projected expansion through 2032 is driven by three mutually reinforcing forces. First, escalating fraud and identity theft in digital channels have created a persistent demand for stronger, passive, and continuous authentication. Second, regulatory and standards developments are both enabling and constraining deployments: conformity assessments and privacy rules raise the bar for vendors while creating a market for certified, auditable solutions. Third, technology maturation—improved liveness detection, multi-modal fusion algorithms, and edge inference hardware—has made real-time face-voice matching feasible at scale.
These forces interact with sector-specific needs. Financial services and contact-center driven use cases continue to anchor demand for voice-enabled identity proofing and transaction authentication. Border control and digital ID programs push adoption of multimodal biometric solutions where governmental compliance is non-negotiable. Meanwhile, consumer devices and healthcare settings create opportunities for frictionless authentication that respects privacy and accessibility.
Competitive landscape: who to watch and what to ask
The supplier market is characterized by a mix of global system integrators, specialized biometrics vendors, and platform providers. Market concentration is moderate: the top three suppliers account for roughly one-third of industry revenue, and the top five approach about half the market—enough concentration to create standard-setting players, but with ample space for innovative challengers.
-
NEC Corporation (Tokyo) continues to leverage scale and domain experience, integrating voice modules into its NeoFace portfolio for surveillance and enterprise security. Recent launches emphasize real-time, multi-modal watchlist matching suitable for high-throughput environments.
-
Aware Inc. (Bedford, MA) focuses on SDK-driven deployment models. Its Knomi offering now targets tighter device integration, reflecting a strategy to capture authentication flows at the endpoint—especially in regulated mobile scenarios.
-
ID R&D (Neurotechnology) (Cambridge, MA) has advanced liveness detection for both voice and face. Certification milestones in 2025 position it as a vendor to consider where anti-spoofing assurance is a procurement requirement.
-
Daon Inc. (Reston, VA) markets a platform approach combining face, voice, and behavioral biometrics, with recent pilots in banking highlighting its capabilities in KYC and remote onboarding.
-
Voice Biometrics Group (VBG) and Verint Systems remain strong in contact-center fraud prevention, while Thales and HID Global provide broad identity stacks used in border control, digital identity, and enterprise access scenarios.
Key vendor selection questions we recommend for 2026: How does the supplier demonstrate liveness and PAD (presentation attack detection) across modalities? What audit trails and data minimization controls exist to meet high-risk AI and data-protection obligations? Can the solution operate at the edge with sub-100ms matching latency? How transparent and extensible are the model validation and bias-mitigation processes?
Regulation, standards and ethical guardrails
Regulatory and standards developments are no longer background noise; they are primary determinants of deployment risk and opportunity. The EU AI Act’s classification of facial recognition and voice biometrics as high-risk systems requires conformity assessments for many use cases, and GDPR continues to restrict biometric data processing without explicit legal basis. International standards such as ISO/IEC 30107-3 set PAD testing protocols, while national testing bodies (for example, NIST’s face recognition evaluation frameworks) are already incorporating voice benchmarks and multimodal assessments.
For strategy teams, this means procurement must couple technical due diligence with regulatory impact assessments. Choose suppliers that publish test artifacts, support third-party audits, and build privacy-by-design into data pipelines. Expect certification timelines to be a gating factor for large public-sector bids in 2026 and beyond.
Technology and deployment realities
-
Edge compute matters: Real-time face-voice fusion often requires on-device neural processing units (NPUs) to meet latency and privacy requirements. Hardware platforms with optimized NPUs are the practical enablers of sub-100ms matching and are increasingly a prerequisite for consumer-facing and mission-critical applications.
-
Liveness and anti-spoofing: Effective PAD across modalities is the single most important technical differentiator. Vendors that combine acoustic challenge-response, spectral analysis, and active/passive face liveness have a measurable advantage in lowering false-accept and false-reject rates.
-
Integration and orchestration: Identity orchestration layers—APIs, SDKs, and identity hubs—dictate how smoothly biometrics plug into existing IAM, fraud analytics, and CRM systems. Prioritize suppliers that support standardized connectors and provide operational runbooks.
-
Bias mitigation and testing: Robust evaluation across demographic groups and operational environments is a procurement must. Insist on reproducible test suites and explainability artifacts as part of vendor deliverables.
What our WW Face-Voice Biometric Market report delivers
The report is built as an operational tool for executives and technical leaders. It contains:
-
Market sizing and a 2026–2032 forecast model with scenario analysis highlighting upside and downside trajectories under alternative regulatory and technology adoption assumptions.
-
A vendor decision framework: procurement checklists, RFP templates, and a matrix that evaluates vendors on technical, compliance, integration, and commercial axes.
-
Use-case playbooks tailored to priority sectors—financial services, government ID, healthcare, contact centers—with ROI modelling templates and implementation timelines.
-
Risk and compliance toolkit: a mapping of EU AI Act conformity requirements, GDPR impact considerations, and recommended audit artifacts and testing protocols aligned with ISO/IEC and national testing practices.
-
Technology deep-dive: guidance on edge vs. cloud architectures, latency engineering, liveness testing methods, and vendor benchmark procedures without exposing raw sub-segment revenue figures.
-
Competitive profiles and recent dealflow: curated intelligence on leading vendors, product launches, certifications, and pilot outcomes to inform partnership and M&A screening.
How to use this intelligence in 2026
-
Board-level planning: Use the market forecast and risk scenarios to quantify runway for identity modernization programs and to align capex cycles with compliance milestones.
-
Procurement and vendor selection: Apply the vendor decision framework to weigh trade-offs between turnkey platforms and best-of-breed integrations, prioritizing vendors with demonstrable PAD certifications and edge-deployment capabilities.
-
Regulatory preparedness: Map live projects against conformity assessment requirements and build compliance checkpoints into sprint cycles to avoid costly rework.
-
Partnership and M&A scouting: Identify capability gaps—such as liveness testing or edge optimization—and use our vendor intelligence to target partnerships or tuck-in acquisitions that accelerate time-to-market.
Final recommendations
Face-plus-voice biometrics are entering a phase where technical feasibility, regulatory compliance, and commercial value are simultaneously aligning. For 2026, organizations should move from speculative pilots to prioritized, governed rollouts—focusing first on high-value, high-feasibility use cases where certified vendors and mature integration patterns exist. Procurement must demand explainability, PAD certification, and edge-capable implementations. At the same time, leaders must build internal capabilities to manage ethical, privacy, and audit obligations as part of the identity operating model.
Next steps
PW Consulting’s full Worldwide Face-Voice Biometric Market report provides the data, templates, and vendor intelligence necessary to execute the 2026 roadmap. For teams preparing board submissions, procurement processes, or compliance workstreams, the report acts as an actionable playbook without revealing the underlying granular segment disclosures reserved for subscribers. Contact our research team or visit our report page to access the complete dataset, vendor profiles, and downloadable implementation assets.
For detailed analysis of this topic, please visit the official page: Worldwide Face Voice Biometric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Centrifugal Lorry Washing Pump Market to Reach USD 626.82 Million by 2032, Backed by Rising Automated Truck Wash Demand
By pmarketresearch, 2026-07-15
Worldwide Centrifugal Lorry Washing Pump Market — Strategic Imperatives for 2026
PW Consulting’s new market study on the Worldwide Centrifugal Lorry Washing Pump Market provides a focused, execution-ready intelligence package to inform capital allocation, product strategy, sourcing, and go-to-market decisions in 2026. The market is progressing from an estimated USD 442.5 Million in the 2025 base year and is forecast to grow at a 5.14% CAGR through our 2026–2032 forecast window, crossing roughly USD 626.8 Million by 2032. These headline metrics understate a more nuanced reality: demand drivers, regulatory shifts, and technology choices are forcing supply- and demand-side reconfiguration that will determine winners and losers over the next three fiscal planning cycles.
Worldwide Centrifugal Lorry Washing Pump Market
Why this report matters for 2026 decision-makers
- Investment prioritization. The mid-single-digit CAGR masks pockets of above-average growth tied to high-efficiency systems, water-reuse retrofits, and automation projects. Boards and CFOs need a granular view of where to direct capex for the best IRR in 2026.
- Product and R&D roadmaps. Engineers and product leaders must reconcile material choice, pump architecture, and smart controls (for example, VFD integration) to satisfy total cost of ownership and regulatory compliance demands.
- Sourcing and operations. Raw material pressures and service expectations require a strategic supplier playbook — from mainline OEM procurement to aftermarket spare-parts logistics.
- Commercial strategy. Channel economics for automated truck wash operators vs. fleet services vs. mobile providers differ materially; the right commercial model in 2026 can accelerate adoption and aftermarket capture.
Key market dynamics shaping 2026
- Energy efficiency mandates and control tech. Regulatory and corporate energy targets are accelerating adoption of Variable Frequency Drives (VFDs) for pump systems. VFDs allow pumps to match output to instantaneous demand, reduce energy consumption, and — in commercial truck wash environments — can deliver payback periods measured in months, not years, when properly deployed.
- Water stewardship and regulation. Water-reclamation and treatment requirements are moving from optional value-add to procurement precondition in many commercial installations. Advanced wash systems can realize very high reclaimed-water rates, and operators that meet reclamation benchmarks gain both regulatory compliance and operating-cost advantage.
- Material selection and lifecycle cost. Stainless steels (commonly 304/316) and engineered thermoplastics are the core materials in centrifugal pumps for lorry washing. Material choice directly affects corrosion resistance, maintenance intervals, and replacement-cost trajectories — critical inputs for TCO modelling.
- Labor scarcity and automation. Labor availability pressures are accelerating adoption of touch-free and gantry-based automated washes that rely on robust pump systems and smart controls. For fleet operators, the net effect is substitution of upfront capital for lower ongoing personnel costs and more predictable throughput.
- Market structure. The market is moderately concentrated: a small group of established pump OEMs and systems integrators hold a meaningful share of commercial and industrial procurement. Yet structural fragmentation in applications — from fixed automated systems to mobile units and manual fleet wash operations — leaves attractive niches for focused entrants and regional challengers.
Competitive landscape — what to watch from core suppliers
- Cat Pumps (Minneapolis, USA). A long-standing specialist in high-pressure cleaning pumps, Cat Pumps is positioning VFD-capable solutions and high-pressure ranges tailored to automatic and self-serve truck washes. Expect continued emphasis on energy-efficient central systems and channel engagement through trade shows and end-user events to reinforce specification-level preference among carwash operators.
- MP Pumps (Detroit, USA). MP Pumps combines centrifugal and self‑priming capabilities with corrosion-resistant material sets, making it a credible choice where fluid-handling demands are tougher (e.g., saline or chemical-laden runoff). Their product posture is attractive to engineering-led procurement teams focused on uptime and materials engineering.
- Pacer Pumps (USA). Pacer’s thermoplastic centrifugal pumps are notable where abrasion and chemical compatibility drive material choice. Their suite lowers upfront corrosion risk and supports lower-weight installations — an advantage in mobile units and retrofit programs.
- Ampco Pumps (Menomonee Falls, USA). With product lines explicitly targeted at semi truck wash stations and wastewater handling, Ampco is bridging the wash-system and wastewater ecosystems. Recent product showcases underscore a push into higher-capacity industrial wash segments and integration with process-fluid handling needs.
- Xylem / Goulds Water Technology (Rye Brook, USA). Xylem’s stainless end‑suction and multistage offerings are optimized for circulation and spray systems in commercial washing. Their scale and aftermarket footprint position them favorably for specification in large-scale operator rollouts and service contracts.
- Grundfos (Bjerringbro, Denmark). Grundfos brings global brand, energy‑efficiency engineering, and modular booster/circulation pumps that map well to car and commercial vehicle wash architectures. Their strengths are in engineering-resale channel partnerships and energy-optimized portfolios.
- Kärcher (Winnenden, Germany). As a supplier of integrated wash systems, Kärcher’s strength is the systems approach — combining pumps, controls, and water treatment. For operators procuring turnkey solutions or requiring validated water-reuse performance, system suppliers like Kärcher remain high on the short list.
Recent trade-show activity through 2025 demonstrates supplier intent: Cat Pumps and Ampco have actively showcased truck-wash-relevant lines, and multiple industry exhibitions continue to serve as the primary venue for specification decisions among equipment buyers. These events are not merely marketing exercises; they are where systems integrators and fleet operators assess engineering tradeoffs and aftermarket service propositions.
Worldwide Centrifugal Lorry Washing Pump Market
What the PW Consulting report delivers (practical deliverables)
The report is designed as an operational playbook for procurement, product, and corporate strategy teams. Highlights include:
Worldwide Centrifugal Lorry Washing Pump Market
- Top-down and bottom-up market sizing with transparent methodology (base year 2025) and scenario-based forecasts through 2032.
- Demand-driver analysis that quantifies the influence of energy mandates, water-reuse regulation, and automation on purchasing cycles.
- Supplier scorecards and a technical-decision matrix for materials, pump architecture, and control systems to support RFP specifications.
- TCO models and retrofit calculators (including VFD payback and water-recovery ROI templates) you can adapt to site-specific inputs.
- Commercial playbooks: channel strategies for OEMs, integrators, and service providers, including prioritized go-to-market tactics for 2026.
- A regulatory roadmap and compliance checklist for water reclamation and energy-efficiency standards relevant to commercial vehicle wash installations.
- Case studies and procurement checklists to shorten vendor selection cycles and de-risk pilot programs.
Note: while this release outlines the scale and direction of the market, detailed revenue-by-subsegment tables and share tables are withheld here to preserve the value of the full report and are available through our report portal.
Concrete actions for 90 days, 6 months, and 18 months
- 90 days — Diagnostic and quick wins. Run a portfolio audit to identify pumps and systems that are prime candidates for VFD retrofit or material upgrade. Implement a pilot water-reclamation retrofit at one high-throughput site to validate reclaimed-water ratios and operational savings.
- 6 months — Scale and commercial execution. Roll out a prioritized retrofit program for fleet depots, renegotiate supplier terms incorporating life-cycle pricing, and pilot bundled service contracts that monetize preventive maintenance and spare parts.
- 18 months — Structural repositioning. Consider strategic partnerships or bolt-on acquisitions to secure capacity in critical materials or to acquire systems-integration capabilities for water treatment. Product teams should deliver at least one modular pump/control platform optimized for energy and water efficiency.
Risks and watch points
- Raw material volatility (stainless and engineered plastics) can compress margins; hedging and dual-sourcing strategies are essential.
- Accelerating regulatory requirements for water reuse and discharge can alter procurement timing and increase the total solution cost; proactive compliance-first design reduces tender friction.
- New entrants targeting the modular, low-cost mobile-wash niche could disrupt legacy OEM margins unless incumbents accelerate product simplification and aftermarket offerings.
Conclusion — how to use this intelligence in 2026
For executives planning 2026 budgets, the strategic choice is clear: prioritize investments that lower operating cost per wash (energy + water + labor) and solidify recurring aftermarket revenue. PW Consulting’s report converts high-level market growth into executable decisions — from R&D tradeoffs to supplier contracts and channel plays — while providing tools to model site-level economics and regulatory impact. To access the full dataset, subsegment tables, and proprietary supplier scorecards, please visit our report page or contact PW Consulting for a briefing tailored to your organizational role and priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Centrifugal Lorry Washing Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Child-Resistant Blister Lidding Film Market to Reach USD 1,559.1 Million by 2032 at a 6.94% CAGR
By pmarketresearch, 2026-07-15
Worldwide Child Resistant Blister Lidding Film Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Child Resistant Blister Lidding Film Market delivers a focused, actionable intelligence package designed to inform executive decision-making throughout 2026. The market has evolved from an estimated USD 715.4 Million in 2020 to USD 975.0 Million in our 2025 base year and is projected to reach approximately USD 1,559.1 Million by 2032, implying a compound annual growth rate (CAGR) of about 6.94% for the forecast window. These headline metrics mask a number of structural shifts—regulatory tightening, material-feedstock pressures, and innovation nodes around adult-accessibility and sustainability—that will determine winners and losers over the next 18 months.
Worldwide Child Resistant Blister Lidding Film Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year for packaging compliance and circularity. New enforcement, tax regimes, and recycled‑content mandates converge with persistent raw-material volatility to create both risk and opportunity for manufacturers, OEMs and contract packagers.
Worldwide Child Resistant Blister Lidding Film Market -
Decision focus: Whether the objective is pricing strategy, procurement hedging, product roadmap prioritization, or M&A, this study provides the scenario tools and playbooks firms need to convert market momentum into defensible outcomes.
Worldwide Child Resistant Blister Lidding Film Market -
Competitive context: The market exhibits moderate concentration—the top 3 players account for roughly two-fifths of the market, and the top 5 approach a clear majority—making targeted competitive moves (partnerships, capability buy-ins, niche specialization) highly leverageable.
What the report contains (practical components)
-
High-fidelity market sizing and trajectory: multi-year historical tracking and a seven-year forecast that factor in regulatory milestones, commodity price scenarios, and adoption curves for child-resistant formats.
-
Segment architecture and demand drivers: detailed treatment of region, material, and opening-type segmentation to support portfolio rationalization and go-to-market planning (note: the public summary here omits granular segment figures to preserve strategic exclusivity).
-
Cost and margin levers: modelled unit-cost breakdowns that isolate the impact of aluminum, polymer laminates and converting operations under different aluminum price bands—critical given current market sensitivity.
-
Regulatory and standards matrix: practical compliance checklists and design thresholds keyed to CPSC Protocol 1700.20, EN 14375 and other jurisdictional requirements, with recommended testing cadences and documentation templates.
-
Supplier and competitive playbooks: profiles of global suppliers, capability maps, and spotted innovation streams—useful for supplier selection, competitive benchmarking, and acquisition screening.
-
Scenario planning and stress tests: three pragmatic scenarios (Baseline Growth, Commodity Shock, and Accelerated Circularity) with actionable response options for commercial, procurement and R&D leaders.
Market dynamics that should shape 2026 strategy
-
Regulatory pressure and differentiated design requirements. Child-resistance standards—CPSC Protocol 1700.20 in the U.S. and EN 14375 in the EU—create a dual imperative: ensure low child-success rates while maintaining adult accessibility (especially for older adults). Compliance is not a checkbox; it drives product architecture, testing investments, and time-to-market planning.
-
Sustainability mandates are accelerating product redesign. Policy levers such as national plastic taxes and EU recycled-content targets are reshaping the economics of polymer laminates and pushing suppliers toward mono-material solutions or higher-capture recyclable laminates. These rules produce a new cost-benefit calculus for innovation investments and capital allocation.
-
Raw-material exposure remains a near-term business-critical variable. Aluminum—commonly used in 9–20 micron foils laminated to PET or PVC—continues to trade with material-sensitive volatility; recent references place aluminum prices in the mid‑thousands of USD per metric ton. Procurement strategies must therefore combine contractual hedging, supplier diversification and process efficiency to protect margins.
-
Consolidation and capability plays are likely. Given the market’s concentration profile and the capital intensity of specialized converting for child-resistant formats, expect selective M&A and partnerships that provide either geographic reach or technical offerings (e.g., thermoformable lidding, peel-push designs, recyclable polymer laminates).
Competitive landscape — what to watch
-
Amcor plc (Melbourne, Australia): A global packaging leader offering a broad suite of child‑resistant lidding films including recyclable options. Amcor’s product launches signal mainstreaming of circular design principles in pharma-facing formats.
-
Constantia Flexibles (Vienna, Austria): Known for high-barrier aluminum lidding and multi-layer film solutions, Constantia’s trade show presence underscores investments in both performance and regulatory-compliant innovation streams.
-
Tekni‑Plex (Wayne, PA, USA): Strong in thermoformable lidding and senior-friendly peel designs. Certification updates and testing focus reflect a premium placed on validated user performance.
-
Winpak Ltd., Alpine Packaging, ProAmpac, Hood Packaging, Sonoco: These specialists and regional champions add depth across puncture resistance, custom laminates, and sustainability-adopted offerings—making strategic partnerships or bolt-on acquisitions attractive routes to fill capability gaps quickly.
-
Recent signals: Product launches and trade show activities in 2023–2024 demonstrate active product pipelines and an industry pivot toward recyclable/low-carbon offerings—critical intel for players contemplating counter‑moves in pricing, marketing, or product specs.
How to use the report to inform 2026 decisions
-
Procurement and commodity risk: Use the report’s cost-sensitivity models to quantify margin exposure per 1000‑ton aluminum price swings, and adopt a layered procurement approach—short-term spot contracts plus medium-term fixed-volume agreements—to smooth input-cost volatility.
-
Product R&D prioritization: Prioritize designs that satisfy both child-resistance testing and adult usability stress tests (e.g., >100 openings for older adults per EN 14375) while creating a feasible pathway to recycled-content targets without failing CPSC child-safety requirements.
-
Commercial positioning: Segment customers by their sensitivity to sustainability, regulatory compliance burden and cost; tailor value propositions accordingly—certified reproducible test results and lifecycle claims will command a premium in the pharma OEM channel.
-
M&A and partnerships: Target transactions that either close gaps in recyclability/mono-material technology or add converting capacity in strategic geographies. Given a moderate market concentration, focused acquisitions can materially improve market share and bargaining power.
-
Compliance and certification roadmaps: Implement a tiered testing and document strategy keyed to the jurisdictions you serve; accelerate third-party child-safety testing for new materials and incorporate adult-accessibility cohorts in pilot runs.
Practical next steps for executives
-
Run a rapid internal audit against the report’s compliance matrix to identify any immediate gaps in CPSC/EN testing documentation and recycled-content reporting.
-
Model three procurement scenarios using the report’s commodity sensitivity tables to determine the level of hedging and contract length that preserves target margins.
-
Initiate controlled pilots for recyclable/mono-material lidding with two strategically selected customers, using the report’s test-protocol templates to accelerate validation and commercial rollout.
-
Evaluate a short list of potential partners or acquisition targets mapped in the supplier appendices to strengthen capability in high-barrier recyclable laminates or thermoformable technologies.
Closing perspective
The child resistant blister lidding film market is moving from a compliance-driven niche toward a strategic battleground where sustainability, adult-accessibility, and supply-chain resilience determine competitive advantage. With market value expanding materially from mid‑2020s levels toward a substantially larger market by the early 2030s, 2026 will reward firms that convert regulatory pressure and material constraints into product and commercial differentiation.
PW Consulting’s report provides the scenario models, supplier intelligence, and regulatory playbooks required to make those choices with confidence—while reserving the most actionable numeric breakouts and segment-level forecasts for report subscribers. For teams prioritizing pragmatic, defensible action plans for 2026, this study serves as both a roadmap and an operational toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide AI Learning Machine Market to Surge from USD 8.9B in 2025 to USD 33.95B by 2032 at a 21.08% CAGR
By pmarketresearch, 2026-07-15
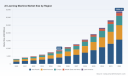
Worldwide AI Learning Machine Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations across education, hardware, and consumer electronics prepare their 2026 playbooks, the Worldwide AI Learning Machine market offers both a compelling growth story and a complex strategic landscape. Our new PW Consulting report — built on a transparent market model and multi‑scenario forecasting — shows the market expanding from an established 2025 baseline to a markedly larger opportunity over the 2026–2032 horizon, driven by rapid adoption of model‑based personalized learning, hardware innovation, and policy tailwinds. The forecast embedded in the study assumes a compound annual growth rate (CAGR) of 21.08% across the projection period, resulting in a materially larger market by the end of the forecast window.
Worldwide AI Learning Machine Market
Executive snapshot: why 2026 is the inflection year
-
Momentum meets regulation. Adoption curves driven by K‑12 and institutional buyers intersect with new national standards and curricular mandates introduced in 2024–2025, creating decisive procurement windows in 2026.
Worldwide AI Learning Machine Market -
Content exclusivity becomes a competitive moat. Recent exclusive content deals and platform bundling moves are shifting value from hardware specifications to curated, pedagogically sound experiences.
Worldwide AI Learning Machine Market -
Supply‑side constraints and sovereignty concerns are reshaping architecture choices. Controls on advanced semiconductors and equipment, combined with supplier realignment, force early decisions on cloud vs edge compute and local manufacturing partnerships.
What PW Consulting’s report delivers — practical tools for 2026 decisions
-
Transparent market model and sensitivity scenarios. We provide a revenue‑model workbook calibrated to 2020–2025 historicals and stress‑tested across three adoption scenarios for 2026–2032, enabling procurement and M&A teams to quantify upside and downside outcomes.
-
Actionable go‑to‑market playbooks. Tailored templates for hardware OEMs, platform providers, content licensors, and institutional buyers (schools, training providers) that translate strategy into 90‑ to 180‑day implementation plans.
-
Procurement and total cost of ownership (TCO) frameworks. Comparative TCO for device fleets, subscription services, content licensing, and support — designed to assist budgeting decisions and vendor negotiations in 2026.
-
Compliance & safety checklists. Practical mappings of relevant standards and regulatory expectations — from algorithmic security benchmarks to content safety boundaries — with mitigation measures and vendor audit templates.
-
Competitive diagnostic dashboards. Benchmarks and strategic profiles for incumbents and challengers, highlighting capability gaps, partnership vectors, and consolidation targets.
Market dynamics you cannot ignore
-
Policy is a demand lever. Educational authorities have started to formalize AI literacy and classroom integration policies; these mandates create institutional procurement cycles and certification requirements that suppliers must meet.
-
Content safety and model governance are table stakes. National standards on model and corpus safety and industry group norms for content review are forcing vendors to invest in runtime filters, curated corpora, and transparent review processes.
-
Hardware and chip access remain strategic chokepoints. Export controls affecting advanced semiconductors and manufacturing equipment are pushing firms to re‑architect inference strategies, with implications for product roadmaps and unit economics.
-
Market concentration is meaningful. The market displays a mid‑tier concentration profile: leading firms account for a material share of revenue but leave substantial room for specialized and regional players. This structure encourages focused differentiation strategies.
Competitive landscape: what the leaders are signaling
-
iFLYTEK — positioning through content and model depth. Recent public filings and product intelligence indicate a strategic emphasis on cognitive large models and exclusive content partnerships. A notable early‑2026 content deal positions the firm to monetize immersive language learning experiences via licensed animation and engaging IP. Their reported acceleration in smart‑education revenue in 2025 underscores the commercial traction of that approach.
-
Yuanfudao (Xiaoyuan) — hardware innovation meets emotional intelligence. Product launches in 2025 revealed an approach that combines tablet computing with an intelligent base unit, prioritizing diagnostics, interactive companionship, and emotional interaction as differentiators for the K‑12 segment.
-
Zuoyebang, TAL and other incumbents — platform breadth and curricular alignment. These market participants are iterating on device ecosystems tightly coupled with existing content libraries and tutoring services, effectively selling an integrated learning proposition rather than standalone hardware.
-
Consumer electronics entrants and legacy educational hardware suppliers — incremental upgrade play. Brands with established distribution networks are rapidly adopting AI features and curriculum‑sync capabilities to defend shelf space and margins.
Implication for partners and investors: the current competitive moves show two clear, investable pathways. One route is content‑centric differentiation — securing pedagogically strong, exclusive IP and building learning analytics to demonstrate outcomes. The other is systems‑level differentiation — integrating hardware, edge inference, and device management to lower TCO and increase deployability in constrained networks.
Scenario planning — three plausible 2026 market trajectories
-
Scenario A: Accelerated adoption. Strong policy support, robust school budgets, and rapid content ecosystem maturation lead to higher‑than‑expected device and subscription uptake. Winners are firms that can scale content licensing and supply chains quickly.
-
Scenario B: Regulated consolidation. Tightened content and model governance increases certification costs, driving out undercapitalized players and favoring larger incumbents and certified niche suppliers.
-
Scenario C: Fragmented localization. Supply constraints and localization policies fragment the market into regional clusters, benefiting players with local content partnerships and compliant manufacturing footprints.
Actionable 90‑ to 360‑day playbook for executives (prioritized)
-
Perform a compliance audit against model safety and content standards. Map gaps, budget remediation, and secure third‑party attestations where necessary.
-
Lock content pipelines. Negotiate multi‑layer licensing deals (seasonal, exclusive, classroom bundles) to protect retention and pricing power.
-
Decide the compute posture. Run an architectural decision workshop to evaluate edge vs cloud trade‑offs given chip availability and latency/affordability constraints.
-
Diversify supply and manufacturing options. Build dual sourcing and local assembly pathways to reduce geopolitical and export risk exposure.
-
Embed measurement into product cycles. Define learning outcome metrics and A/B frameworks to demonstrate educational efficacy to procurement stakeholders.
-
Prepare M&A and partnership scouting. Target assets that close capability gaps — content studios, model safety providers, regional distribution networks — and accelerate time to market.
Why this report matters for 2026 decisions
Across product development, procurement, regulatory compliance, and corporate strategy, 2026 is a make‑or‑break year for organizations aiming to capture long‑term value in the AI learning machine space. PW Consulting’s market model quantifies the trajectory and the levers that most influence upside, while our playbooks translate those levers into executable, calendar‑driven steps. Whether you are a device OEM, content studio, platform provider, or institutional buyer, the analysis equips you to prioritize investments, negotiate from an informed position, and mitigate asymmetric risks tied to regulation and supply chains.
Next steps and how to access the full intelligence
This release is a strategic preview: it highlights the core trends, competitive moves, and decision frameworks that matter for 2026 without disclosing the granular regional and product split tables that form the basis of our customer‑facing model. The full report includes proprietary datasets, scenario‑driven revenue models, vendor scorecards, and downloadable implementation templates designed for immediate operational use. For teams planning budgets, partnership strategies, or bolt‑on acquisitions in 2026, the full suite of deliverables will materially shorten time to action and reduce execution risk.
To obtain the complete report, model workbook, and executive briefing package, please refer to the official PW Consulting distribution channel. Our analysts are available to walk through tailored implications for your organization and to run a bespoke 90‑day activation workshop aligned to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Headphones Without Mic Market to Grow at 4.25% CAGR, Reaching USD 6.42 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Headphones Without Mic Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies prepare 2026 strategies, the Worldwide Headphones Without Mic market presents a picture of steady expansion, structural specialization and supplier-side stresses that will determine competitive advantage. Our analysis — with base year 2025 and a forecast window of 2026–2032 — shows a market that has grown from the low billions in 2020 to roughly USD 4.8 billion in 2025 and is expected to expand at a compound annual growth rate of approximately 4.25% through 2032, when overall size will exceed the mid‑six‑billion dollar mark. The pace is modest but meaningful: sufficient to reward clarity in product segmentation, supply-chain planning and regulatory readiness.
Worldwide Headphones Without Mic Market
What PW Consulting’s report delivers — a practical toolkit
- Proven market-sizing methodology and scenario models that reconcile historical performance (2020–2025) with three forward-looking demand cases (conservative, baseline, upside) for 2026–2032.
- Actionable demand-driver analysis (professional studio, home entertainment and audiophile use cases) that connects buyer priorities to SKU-level product attributes and margin expectations.
- Supply-chain diagnostics, including raw‑material exposure matrices, supplier concentration heatmaps and lead‑time sensitivity dashboards to quantify production risk and cost volatility.
- Competitive playbooks: comparative capability maps for global OEMs and specialty brands, plus a tactical list of 12 go-to-market plays for premium, pro and mass segments.
- Commercial tools — SKU rationalization frameworks, pricing and tariff impact simulators, TCO models for localized vs centralized manufacturing, and M&A screening checklists.
- Regulatory and sustainability compliance checklists mapped to likely 2026 enforcement priorities and supplier audit templates.
Why this matters for 2026 planning
Three structural realities make this market uniquely actionable in 2026.
Worldwide Headphones Without Mic Market
- Modest but persistent growth: steady CAGR means companies cannot rely on demand tailwinds to mask operational or product missteps; market share moves incrementally but decisively.
- Fragmented specialization: leadership is split between legacy pro audio incumbents and a diverse set of premium audiophile and niche handcrafted players — creating both partnership and disruption opportunities.
- Supplier-side pressures: raw-material price swings, labor cost inflation, regulatory tightening and specific component bottlenecks are the immediate levers that will shape margin and time-to-market.
Industry dynamics you must factor into Q1–Q2 2026 decisions
- Raw materials: Neodymium magnet pricing has risen materially (approximately a mid‑double‑digit percentage year‑on‑year move, with recent market reports citing prices near USD 85/kg), increasing per‑unit driver costs for dynamic-driver models.
- Labor: Assembly hubs are experiencing wage inflation — for example, Vietnam’s headphone assembly wage trends have increased, tightening labor-cost differentials versus alternative locations.
- Regulation: Updated RoHS thresholds (effective January 2026) raise compliance requirements for cable and component suppliers; firms must validate vendor declarations and redesign legacy harnesses where needed.
- Trade policy: US tariffs on certain headphone imports remain a material input to landed cost models; companies selling into North America must choose between tariff absorption, price pass‑through, or near‑market assembly options.
- Component supply constraints: High‑end planar magnetic driver lead times have extended substantially (industry tracking indicates multiples of prior norms), forcing prioritization of core SKUs and alternative technology roadmaps.
Competitive landscape — profiles and tactical implications
The market’s upper tier blends multinational electronics giants and specialized audio houses. Our report provides side‑by‑side capability maps; below is a concise strategic read of the leading players:
Worldwide Headphones Without Mic Market
- Sony Corporation (Tokyo, Japan — https://www.sony.com): Sony’s pro and hi‑fi MDR lineage anchors its professional and consumer credibility. Recent product continuity moves for legacy studio models signal a focus on reliability and brand trust in core markets.
- Sennheiser (Wedemark, Germany — https://www.sennheiser.com): Strong in both audiophile and studio monitoring, Sennheiser continues to invest in driver and tuning refinements — most recently introducing a new open-back studio model showcased at a major industry event in late 2025. Their technical heritage positions them well for mixing and critical listening segments.
- Audio‑Technica (Machida, Japan — https://www.audio-technica.com): Known for rugged studio staples, Audio‑Technica’s recent stationary studio and passive model releases underscore an approach that balances classic mechanical designs with targeted product variants for recording professionals.
- Beyerdynamic (Helicon, Germany — https://www.beyerdynamic.com): Beyerdynamic’s investments in driver technology and professional updates have kept it competitive in closed‑back, pro‑use categories; incremental upgrades to established lines are their tactical play.
- Grado Labs (Brooklyn, NY — https://gradolabs.com): A handcrafted, artisanal competitor, Grado leverages wood housing and niche manufacturing to command premium pricing among audiophile buyers — an example of differentiation that is resilient to component commoditization.
- AKG (Harman) (Northridge, CA — https://www.akg.com): AKG’s studio legacy and broad pro adoption keep it relevant in reference monitoring; the brand’s positioning favors OEM partnerships and studio channel depth.
- Focal‑JMlab (Saint‑Étienne, France — https://www.focal.com): A high‑end audiophile specialist, Focal’s material and transducer innovations target top‑tier listeners and distributors who value technical differentiation over scale.
- Audeze (Costa Mesa, CA — https://www.audeze.com): As a planar‑magnetic leader, Audeze exemplifies both premium pricing power and exposure to planar driver lead‑time risk — an asset class that commands dedicated supply‑chain strategies.
Strategic implications — recommended actions for 2026
Leaders must convert market intelligence into operational moves. The following condensed playbook is designed for executives who need rapid, high‑confidence decisions:
- Supply‑chain resilience: Secure multi‑tier supply agreements for magnet and driver components, prioritize long‑lead items for early booking, and evaluate hedging instruments where appropriate.
- Near‑market assembly and tariff mitigation: Model localized assembly in North America or Mexico for SKUs destined for the US market to avoid tariff pressure, while using centralized facilities for global mass SKUs.
- SKU and portfolio optimization: Use SKU rationalization tools to retire low‑margin variants and focus R&D spend on high‑margin professional and audiophile lines where brand and materials deliver defensible pricing.
- Regulatory-first design: Adopt “RoHS‑first” cable and connector specifications across new launches and impose supplier attestations to prevent costly redesigns mid‑production.
- Channel and pricing discipline: Segment pricing by channel (pro dealers vs DTC audiophile) and insulate professional SKUs from discount cycles common in consumer channels.
- M&A and partnerships: Target strategic acquisitions of specialized driver suppliers or boutique brands to secure IP and reduce dependence on constrained planar driver vendors.
- Scenario planning: Maintain parallel plans for continued tariff environments, accelerated component inflation, and an upside where high‑resolution audio demand surges — each plan tied to explicit trigger metrics.
How PW Consulting’s report supports execution
The full report translates analysis into executable deliverables: downloadable pricing and tariff simulators, supplier risk heatmaps, SKU prioritization matrices, and editable scenario models you can plug into your FY‑2026 planning. We also provide board‑ready slides that map each strategic play to expected P&L and cash‑flow outcomes over 12–36 months.
What this preview omits — and where to find it
This release intentionally highlights strategic insights without revealing the granular regional, application or type‑level revenue splits. The full dataset — including regional and application breakdowns, detailed SKU‑level forecasts and the downloadable financial models referenced above — is available in the complete Worldwide Headphones Without Mic Market report page. That dataset is indispensable for precise go‑to‑market modeling, M&A valuation work and supply‑chain contracting.
Final thought
For 2026, success in headphones without mic will not be won by chasing generalized growth but by mastering three levers: (1) securing scarce component supply on commercially sensible terms, (2) aligning product architecture to clearly differentiated buyer needs, and (3) structuring manufacturing and channel decisions to neutralize tariff and regulatory shocks. PW Consulting’s comprehensive report converts those levers into executable plans — with the modeling, vendor intelligence and board-level narratives necessary to move from insight to implementation.
For detailed analysis of this topic, please visit the official page: Worldwide Headphones Without Mic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Stearyl Methacrylate Market Tops USD 163.1 Million in 2025, Poised for 5.48% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Stearyl Methacrylate (SMA) Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Worldwide Stearyl Methacrylate (SMA) Market report (base year 2025; forecast period 2026–2032) delivers a concise, executable perspective for corporate leaders preparing strategy and investment plans in 2026. SMA — a long‑chain methacrylate employed across lubricant additives, personal care, adhesives, coatings and specialty chemical syntheses — is on a steady growth trajectory. Our model places the global market at USD 163.1 Million in 2025 and forecasts a compound annual growth rate (CAGR) of 5.48% through the 2026–2032 horizon, taking the market from roughly USD 179.7 Million in 2026 to around USD 236.9 Million by 2032.
Worldwide Stearyl Methacrylate (SMA) Market
Why this report matters for 2026 strategic planning
-
Actionable timing: The transition from recovery to structural growth in the SMA market creates distinct windows for capacity investments, partnerships and product premiumization. Our forecast pinpoints where and when demand inflection points will test supply resilience.
Worldwide Stearyl Methacrylate (SMA) Market -
Risk‑calibrated choices: Volatility in fatty alcohol feedstocks and shifting raw material sourcing patterns are primary risk drivers. Our scenario matrix allows procurement and treasury to stress‑test procurement strategies against plausible feedstock and price shocks.
Worldwide Stearyl Methacrylate (SMA) Market -
Competitive positioning: With a marketplace dominated by a small set of established specialty chemical players, effective 2026 strategies will need to combine product differentiation, supply security and go‑to‑market agility. The report translates this into tactical playbooks for upstream and downstream stakeholders.
Key macro dynamics translating to boardroom decisions
-
Steady, predictable growth: The expected mid‑single digit CAGR through 2032 supports disciplined capacity expansion rather than aggressive brownfield greenfield race. For capital planners, that favors staged debottlenecking and flexible, modular capacity additions.
-
Feedstock and sustainability: SMA is produced by esterification of methacrylic acid with stearyl alcohol, making stearyl alcohol a critical upstream input. Supply choices — petrochemical versus bio‑derived fatty alcohols — carry implications for cost, carbon footprint and market access, particularly in premium personal care and high‑end lubricant segments.
-
Product purity and segmentation: Market demand divides between standard and high‑purity grades. High‑purity SMA commands strategic value in formulations where trace impurities affect performance or regulatory classification, but it requires higher processing control and capex. Our guidance helps product managers determine when to chase purity premiums versus scale economics.
-
Application mix shifts: Lubricant additives remain a core demand engine, but growth in personal care formulations and specialty coatings creates attractive adjacent opportunities for margin improvement. Commercial teams should prioritize application‑specific value propositions and co‑development with formulators.
What’s in the report — practical deliverables
-
Supply‑demand model (2020–2032) with monthly and annualized outputs, enabling scenario comparisons and capacity utilization simulations.
-
Price architecture and margin model denominated in USD (revenue unit: Million), with breakpoint analysis for premium versus commodity grades.
-
Raw material exposure map focusing on stearyl alcohol sourcing, transport corridors and supplier concentration risk.
-
Commercial playbooks for product segmentation, channel strategy and account prioritization across lubricant, personal care and industrial coatings customers.
-
Regulatory, sustainability and product stewardship checklist tailored to 2026 compliance landscapes.
-
M&A and JV decision framework including target screening criteria, valuation lenses and integration risk checklists.
Competitive landscape — strategic read on leading players
The SMA market is characterized by a meaningful presence of established specialty chemical manufacturers and niche suppliers. These companies combine R&D capability, global distribution and, in many cases, branded product offerings. Key players analyzed in the report include:
-
BASF SE (Ludwigshafen, Germany) — Leading specialty portfolio with SMA products (e.g., SMA 1618 and SMA 1618 F) positioned as mono‑functional monomers with long hydrophobic chains. BASF’s strength lies in integrated coatings and additives relationships, enabling them to place SMA into end‑use formulations and co‑develop performance enhancements such as flow improvement and pour point depression for lubricants.
-
Mitsubishi Gas Chemical Company, Inc. (Tokyo, Japan) — A diversified specialty chemical player with a product position focused on fiber treatments, coatings and adhesives. Mitsubishi’s global customer base in performance materials makes it a valuable comparator for players seeking to expand in Asia and premium industrial segments.
-
Jamorin International (Luxembourg / Global) — A focused supplier with differentiated SMA grades targeted at lubricant additive compounding, particularly viscosity index improvement and pour point depression in paraffinic oils. Jamorin exemplifies the niche‑specialist model: fewer products, high technical intimacy with a select set of formulators.
-
NOF Corporation (Tokyo, Japan) — Offers SMA as part of a broader functional monomers and oleo‑specialty chemicals portfolio. NOF’s breadth across functional monomers provides cross‑sell opportunities and resilience where adjacent monomers move counter‑cyclically.
Across this set, strategic positioning varies from global integrated solutions and co‑development (BASF) to niche technical partnerships (Jamorin). For industry entrants and incumbents reconsidering competitive priorities in 2026, the choice is between scale‑and‑integration and specialist intimacy — both viable when matched to a disciplined operational model.
Strategic recommendations for 2026
-
Prioritize supply security through diversified contracts: Given the centrality of stearyl alcohol, firms should secure multi‑tier sourcing, consider backward integration where economically viable, and negotiate indexed supply contracts with flexibility clauses for feedstock shifts.
-
Adopt modular capacity expansion: The market’s steady growth supports modular debottlenecking over large greenfield projects. This reduces time‑to‑market for higher‑purity grades and preserves optionality to pivot toward higher‑margin application niches.
-
Differentiate on formulation value, not just price: Commercial teams should invest in application labs and joint development agreements with formulators in lubricants and personal care. Demonstrable performance gains (e.g., improved cold‑flow or tactile properties) enable premium pricing and stickier contracts.
-
Embed sustainability into product positioning: Develop traceable fatty alcohol sourcing, favor bio‑based feedstocks where feasible and quantify lifecycle benefits. Sustainability credentials will unlock premium channels in cosmetics and regulated markets.
-
Use M&A selectively to acquire capabilities: Look for targets offering specialty grades, regional distribution strength, or complementary monomers. Focus on bolt‑on acquisitions that accelerate access to specific application clusters or regional customers without large integration risk.
-
Hedge commercial exposure through contractual structuring: Offer blended contracts that include price adjustment mechanisms tied to feedstock indices, while protecting margins with floor pricing and minimum purchase commitments.
Risk factors and early warning indicators
-
Feedstock volatility: Moves in fatty alcohol availability or pricing can compress margins rapidly. Early warnings include extended lead times for fatty alcohols, spot price spikes and shifts in supplier portfolios toward higher‑value co‑products.
-
Regulatory tightening: Changes in monomer or residual solvent regulations can increase compliance costs for higher‑throughput plants; monitor draft regulations in major jurisdictions and anticipate reformulation timelines.
-
Substitution and formulation shifts: Advances in alternative polymer chemistries or additive platforms could reduce reliance on SMA in selected formulations — keep a close watch on R&D developments from lubricant and coating formulators.
-
Consolidation dynamics: Continued consolidation among specialty chemical suppliers or lubricant formulators could alter bargaining dynamics — maintain prioritized relationships with strategic customers.
How PW Consulting’s analysis helps you act in 2026
Our report synthesizes quantitative forecasting (2020–2032) with qualitative, transaction‑focused insight to create a playbook for executives. Whether the goal is to optimize procurement, calibrate capital expenditure, execute targeted M&A, or redesign sales coverage, the intelligence in this study is tailored for decisions that have 12–36 month lead times and multi‑year commercial impacts.
Importantly, while this summary highlights the strategic levers and macro numbers that matter for boardroom conversations in 2026, the full report contains the granular models, regional demand breakdowns, purity‑tier economics and supplier maps that support executable investment plans. For procurement teams, product managers and corporate development leads preparing their 2026 agendas, those deliverables are the difference between reactive and proactive strategy execution.
Next steps
To access the full dataset, regional breakdowns, detailed segment economics and our supplier risk maps, visit the PW Consulting report page for the Worldwide Stearyl Methacrylate (SMA) Market. The full report provides the confidential appendices and actionable templates required to convert these insights into commercial outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Stearyl Methacrylate (SMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCM Metal Sheet Market Set for Steady Expansion — 5.15% CAGR Through 2032, Led by Asia‑Pacific Demand
By pmarketresearch, 2026-07-15
PCM Metal Sheet Market 2026: Strategic Intelligence for Decision Makers
Executive snapshot
The pre‑coated metal (PCM) sheet market has entered a phase where disciplined industrial strategy, granular supplier intelligence, and nimble cost‑management will determine winners. Our updated market model shows the industry expanding from roughly USD 3.75 billion in 2020 to about USD 4.85 billion in 2025 (base year), with a mid‑single‑digit trajectory thereafter. PW Consulting’s forecast through 2032 projects a compound annual growth rate (CAGR) of 5.15%, taking the market to an estimated USD 6.89 billion by the end of the decade. For 2026 corporate planning, these headline dynamics — steady demand growth coupled with episodic input‑cost volatility — create a narrow window for strategy choices that materially affect margin and market position.
PCM Metal Sheet Market
Why this report matters for 2026 planning
- Actionable timing: We align market forecasts to procurement cycles, new product development timelines, and capex review windows commonly used by appliance OEMs, construction product manufacturers, and large fabricators.
- Decision economics: The report converts market growth assumptions into supplier capacity scenarios, price sensitivity models, and profitability break‑points so senior leaders can test “what‑if” options without building bespoke analytics teams.
- Risk‑to‑opportunity mapping: Beyond headline growth, the analysis translates raw material shocks, regulatory constraints, and service differentiators into prioritized mitigation and capture plays for commercial, sourcing, and R&D leaders.
Report contents — practical, deployable modules
- Executive framework and five strategic pathways for market leaders and challenger brands.
- Market sizing and trend lines (2020–2025 historical, 2026–2032 forecast) with scenario overlays and sensitivity to raw material price indices.
- Supply‑side diagnostics: capacity maps, line‑level capabilities (coil coating, embossing, film lamination), and supplier readiness for specialty coatings and small‑lot color matching.
- Commercial playbooks: contracting templates, indexation clauses keyed to cold‑rolled and hot‑rolled coil benchmarks, and customer segmentation for premium vs. commoditized PCM.
- Regulatory and sustainability module: compliance checklists (ISO 9001, RoHS) and EPD/LCAs required by large appliance OEMs and public infrastructure tenders.
- Supplier scorecards and deal structuring guidance — quality, lead time, price, and environmental compliance are weighted and benchmarked.
- Competitive landscape and M&A heat map with tactical recommendations for alliances, bolt‑on acquisitions, and JV structures.
- Operational excellence playbook: recommended takt times, quality checkpoints (e.g., ΔE color tolerances, salt‑spray resistance thresholds), and digitization priorities for shopfloor traceability.
- Appendices: downloadable model, data tables, and an annotated list of primary data sources and validation checks.
Market dynamics that should shape 2026 choices
- Input cost pressure: The market is sensitive to base‑metal spreads and processing differentials. Current industry indicators show a persistent premium on cold‑rolled coil versus hot‑rolled coil, reflecting the extra processing required for PCM substrates; meanwhile regional HRC price movements in early 2026 have displaced short‑term margin assumptions for many suppliers. Companies that revise contract terms to include transparent, auditable indexation mechanisms reduce margin leakage and preserve supply relationships.
- Demand complexion: End‑market pull remains anchored in household appliances and construction finishes, while transportation and specialty industrial segments provide episodic upside. Winning propositions will marry material performance (corrosion resistance, long‑life warranties) with service elements such as just‑in‑time coil replenishment and precise color matching.
- Compliance and procurement hygiene: ISO 9001 and environmental constraints such as RoHS are table stakes; leading buyers now vet third‑party test reports (SGS, BV, Intertek) and expect suppliers to publish EPDs or equivalent lifecycle disclosures when bidding for large programs.
- Concentration and competitive tension: The market exhibits moderate consolidation among top players. A compact competitive core controls a meaningful share of capacity, placing a premium on commercial sophistication for mid‑market buyers looking to diversify risk without sacrificing price.
Competitive landscape — what top players reveal about strategy
The sector combines global steel majors, regional champions, and specialist PCM producers. Each archetype signals a distinct strategic playbook for 2026:
PCM Metal Sheet Market
- Global integrated producers (examples include long‑standing steel majors): leverage vertical integration to defend margin through upstream supply security, offering bundled guarantees (coating warranties, long‑tenor supply contracts) that appeal to large OEMs seeking single‑source simplicity.
- Regional system integrators and niche specialists: firms with focused production of pre‑painted coils and value‑added services (tight ΔE color matching, extended salt‑spray resistance) win business where technical fit and service responsiveness trump lowest price.
- Commercial differentiators: several suppliers are investing in coatings development (e.g., antiviral surfaces) and cataloged product families to lock in specification leadership with appliance OEMs and building product manufacturers.
Key operational signals to watch from publicly visible players: capacity announcements and published performance records (for example, a supplier reporting zero rust claims across a large shipment cohort), catalog expansions that imply new color or film portfolios, and facility investments tied to coil center processing and embossing capabilities. These moves are strong leading indicators of where competition for premium segments will intensify.
PCM Metal Sheet Market
Strategic implications and recommended moves for 2026
- Procurement: Move from annual RFQs to multi‑year, index‑linked frameworks that incorporate transparent cost pass‑through for coil indices and processing differentials. Embed quality KPIs (color delta, salt‑spray hours) with financial penalties and reward gates tied to continuous improvement.
- Supply diversification: Adopt a tiered supplier strategy — retain strategic capacity with integrated majors while engaging regional specialists for innovation and service uplift. Scenario‑based sourcing playbooks in the report map how to rebalance exposure across supplier archetypes without disrupting production.
- Product strategy: For OEMs, specify performance bands (e.g., corrosion warranty, aesthetic durability) rather than commodity grades; this allows suppliers to propose differentiated coating systems and supports premium pricing models.
- Operational resilience: Invest in inbound visibility (real‑time shipment tracking, quality imaging) and co‑design small‑lot production capabilities to reduce inventory drag and accelerate new SKUs from pilot to scale.
- Sustainability and compliance: Prioritize suppliers with published EPDs and demonstrable third‑party certification. Early alignment with green procurement criteria will be a competitive advantage in public tenders and OEM supplier scorecards.
- M&A and partnerships: The report identifies niches where bolt‑on acquisitions (local coil centers, film‑lamination specialists) deliver step‑change capabilities quickly; alternatively, use JVs to access regional logistics benefits while sharing capex.
Data integrity & what we deliberately withhold here
To preserve the value of the full research package and to comply with our “trailer” principle for public communications, this release presents sector‑level growth and concentration metrics while omitting detailed segment splits, regional percentages, and supplier revenue lines. The full report contains the granular datasets that senior decision‑makers use in sourcing negotiations — downloadable supplier scorecards, regional demand curves, substrate‑by‑application matrices, and a live Excel model calibrated to multiple pricing scenarios. Clients and interested parties are invited to access the complete package to operationalize these insights.
Recent market signals to monitor in 1H–2H 2026
- Supplier performance disclosures (e.g., reported rust‑free shipment cohorts, expanded catalogs) that validate quality claims and reduce due diligence friction.
- Facility communications and community engagement from regional producers, which often presage capacity availability or local hiring that will impact lead times.
- Raw material index movements and substrate spreads; a sustained premium for cold‑rolled coil versus hot‑rolled coil will change the relative economics of PCM substrates and co‑determine pricing strategies.
- Regulatory tender language shifts favoring environmental declarations and lifecycle metrics.
Next steps for leaders
- Download the full PCM Metal Sheet Market report and Excel model to run procurement scenarios against your 2026 budgets and capex plans.
- Initiate a rapid supplier risk audit using our scorecard template (included with the report) to identify high‑risk single‑source dependencies and validate alternative qualified suppliers within 60 days.
- Convene a cross‑functional war‑room (procurement, engineering, quality, regulatory) to adopt the tactical playbook and contract templates we provide — this reduces negotiation cycles and locks in performance parameters before cost swings intensify.
PW Consulting’s PCM Metal Sheet Market report is crafted for leaders who need both the macro line of sight (market size and 2026 trajectory) and the micro operational tools to convert insight into commercial advantage. For access to the full datasets, supplier scorecards, and downloadable models, visit our report page and contact our strategy team for a briefing tailored to your business priorities.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com