

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Headphones Without Mic Market to Grow at 4.25% CAGR, Reaching USD 6.42 Billion by 2032

Worldwide Headphones Without Mic Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies prepare 2026 strategies, the Worldwide Headphones Without Mic market presents a picture of steady expansion, structural specialization and supplier-side stresses that will determine competitive advantage. Our analysis — with base year 2025 and a forecast window of 2026–2032 — shows a market that has grown from the low billions in 2020 to roughly USD 4.8 billion in 2025 and is expected to expand at a compound annual growth rate of approximately 4.25% through 2032, when overall size will exceed the mid‑six‑billion dollar mark. The pace is modest but meaningful: sufficient to reward clarity in product segmentation, supply-chain planning and regulatory readiness.
Worldwide Headphones Without Mic Market
What PW Consulting’s report delivers — a practical toolkit
- Proven market-sizing methodology and scenario models that reconcile historical performance (2020–2025) with three forward-looking demand cases (conservative, baseline, upside) for 2026–2032.
- Actionable demand-driver analysis (professional studio, home entertainment and audiophile use cases) that connects buyer priorities to SKU-level product attributes and margin expectations.
- Supply-chain diagnostics, including raw‑material exposure matrices, supplier concentration heatmaps and lead‑time sensitivity dashboards to quantify production risk and cost volatility.
- Competitive playbooks: comparative capability maps for global OEMs and specialty brands, plus a tactical list of 12 go-to-market plays for premium, pro and mass segments.
- Commercial tools — SKU rationalization frameworks, pricing and tariff impact simulators, TCO models for localized vs centralized manufacturing, and M&A screening checklists.
- Regulatory and sustainability compliance checklists mapped to likely 2026 enforcement priorities and supplier audit templates.
Why this matters for 2026 planning
Three structural realities make this market uniquely actionable in 2026.
Worldwide Headphones Without Mic Market
- Modest but persistent growth: steady CAGR means companies cannot rely on demand tailwinds to mask operational or product missteps; market share moves incrementally but decisively.
- Fragmented specialization: leadership is split between legacy pro audio incumbents and a diverse set of premium audiophile and niche handcrafted players — creating both partnership and disruption opportunities.
- Supplier-side pressures: raw-material price swings, labor cost inflation, regulatory tightening and specific component bottlenecks are the immediate levers that will shape margin and time-to-market.
Industry dynamics you must factor into Q1–Q2 2026 decisions
- Raw materials: Neodymium magnet pricing has risen materially (approximately a mid‑double‑digit percentage year‑on‑year move, with recent market reports citing prices near USD 85/kg), increasing per‑unit driver costs for dynamic-driver models.
- Labor: Assembly hubs are experiencing wage inflation — for example, Vietnam’s headphone assembly wage trends have increased, tightening labor-cost differentials versus alternative locations.
- Regulation: Updated RoHS thresholds (effective January 2026) raise compliance requirements for cable and component suppliers; firms must validate vendor declarations and redesign legacy harnesses where needed.
- Trade policy: US tariffs on certain headphone imports remain a material input to landed cost models; companies selling into North America must choose between tariff absorption, price pass‑through, or near‑market assembly options.
- Component supply constraints: High‑end planar magnetic driver lead times have extended substantially (industry tracking indicates multiples of prior norms), forcing prioritization of core SKUs and alternative technology roadmaps.
Competitive landscape — profiles and tactical implications
The market’s upper tier blends multinational electronics giants and specialized audio houses. Our report provides side‑by‑side capability maps; below is a concise strategic read of the leading players:
Worldwide Headphones Without Mic Market
- Sony Corporation (Tokyo, Japan — https://www.sony.com): Sony’s pro and hi‑fi MDR lineage anchors its professional and consumer credibility. Recent product continuity moves for legacy studio models signal a focus on reliability and brand trust in core markets.
- Sennheiser (Wedemark, Germany — https://www.sennheiser.com): Strong in both audiophile and studio monitoring, Sennheiser continues to invest in driver and tuning refinements — most recently introducing a new open-back studio model showcased at a major industry event in late 2025. Their technical heritage positions them well for mixing and critical listening segments.
- Audio‑Technica (Machida, Japan — https://www.audio-technica.com): Known for rugged studio staples, Audio‑Technica’s recent stationary studio and passive model releases underscore an approach that balances classic mechanical designs with targeted product variants for recording professionals.
- Beyerdynamic (Helicon, Germany — https://www.beyerdynamic.com): Beyerdynamic’s investments in driver technology and professional updates have kept it competitive in closed‑back, pro‑use categories; incremental upgrades to established lines are their tactical play.
- Grado Labs (Brooklyn, NY — https://gradolabs.com): A handcrafted, artisanal competitor, Grado leverages wood housing and niche manufacturing to command premium pricing among audiophile buyers — an example of differentiation that is resilient to component commoditization.
- AKG (Harman) (Northridge, CA — https://www.akg.com): AKG’s studio legacy and broad pro adoption keep it relevant in reference monitoring; the brand’s positioning favors OEM partnerships and studio channel depth.
- Focal‑JMlab (Saint‑Étienne, France — https://www.focal.com): A high‑end audiophile specialist, Focal’s material and transducer innovations target top‑tier listeners and distributors who value technical differentiation over scale.
- Audeze (Costa Mesa, CA — https://www.audeze.com): As a planar‑magnetic leader, Audeze exemplifies both premium pricing power and exposure to planar driver lead‑time risk — an asset class that commands dedicated supply‑chain strategies.
Strategic implications — recommended actions for 2026
Leaders must convert market intelligence into operational moves. The following condensed playbook is designed for executives who need rapid, high‑confidence decisions:
- Supply‑chain resilience: Secure multi‑tier supply agreements for magnet and driver components, prioritize long‑lead items for early booking, and evaluate hedging instruments where appropriate.
- Near‑market assembly and tariff mitigation: Model localized assembly in North America or Mexico for SKUs destined for the US market to avoid tariff pressure, while using centralized facilities for global mass SKUs.
- SKU and portfolio optimization: Use SKU rationalization tools to retire low‑margin variants and focus R&D spend on high‑margin professional and audiophile lines where brand and materials deliver defensible pricing.
- Regulatory-first design: Adopt “RoHS‑first” cable and connector specifications across new launches and impose supplier attestations to prevent costly redesigns mid‑production.
- Channel and pricing discipline: Segment pricing by channel (pro dealers vs DTC audiophile) and insulate professional SKUs from discount cycles common in consumer channels.
- M&A and partnerships: Target strategic acquisitions of specialized driver suppliers or boutique brands to secure IP and reduce dependence on constrained planar driver vendors.
- Scenario planning: Maintain parallel plans for continued tariff environments, accelerated component inflation, and an upside where high‑resolution audio demand surges — each plan tied to explicit trigger metrics.
How PW Consulting’s report supports execution
The full report translates analysis into executable deliverables: downloadable pricing and tariff simulators, supplier risk heatmaps, SKU prioritization matrices, and editable scenario models you can plug into your FY‑2026 planning. We also provide board‑ready slides that map each strategic play to expected P&L and cash‑flow outcomes over 12–36 months.
What this preview omits — and where to find it
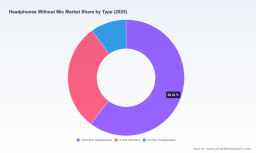
This release intentionally highlights strategic insights without revealing the granular regional, application or type‑level revenue splits. The full dataset — including regional and application breakdowns, detailed SKU‑level forecasts and the downloadable financial models referenced above — is available in the complete Worldwide Headphones Without Mic Market report page. That dataset is indispensable for precise go‑to‑market modeling, M&A valuation work and supply‑chain contracting.
Final thought
For 2026, success in headphones without mic will not be won by chasing generalized growth but by mastering three levers: (1) securing scarce component supply on commercially sensible terms, (2) aligning product architecture to clearly differentiated buyer needs, and (3) structuring manufacturing and channel decisions to neutralize tariff and regulatory shocks. PW Consulting’s comprehensive report converts those levers into executable plans — with the modeling, vendor intelligence and board-level narratives necessary to move from insight to implementation.
For detailed analysis of this topic, please visit the official page: Worldwide Headphones Without Mic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com