

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
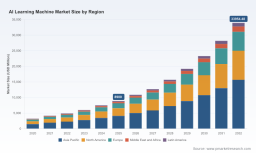
PW Consulting: Worldwide AI Learning Machine Market to Surge from USD 8.9B in 2025 to USD 33.95B by 2032 at a 21.08% CAGR

Worldwide AI Learning Machine Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations across education, hardware, and consumer electronics prepare their 2026 playbooks, the Worldwide AI Learning Machine market offers both a compelling growth story and a complex strategic landscape. Our new PW Consulting report — built on a transparent market model and multi‑scenario forecasting — shows the market expanding from an established 2025 baseline to a markedly larger opportunity over the 2026–2032 horizon, driven by rapid adoption of model‑based personalized learning, hardware innovation, and policy tailwinds. The forecast embedded in the study assumes a compound annual growth rate (CAGR) of 21.08% across the projection period, resulting in a materially larger market by the end of the forecast window.
Worldwide AI Learning Machine Market
Executive snapshot: why 2026 is the inflection year
-
Momentum meets regulation. Adoption curves driven by K‑12 and institutional buyers intersect with new national standards and curricular mandates introduced in 2024–2025, creating decisive procurement windows in 2026.
Worldwide AI Learning Machine Market -
Content exclusivity becomes a competitive moat. Recent exclusive content deals and platform bundling moves are shifting value from hardware specifications to curated, pedagogically sound experiences.
Worldwide AI Learning Machine Market -
Supply‑side constraints and sovereignty concerns are reshaping architecture choices. Controls on advanced semiconductors and equipment, combined with supplier realignment, force early decisions on cloud vs edge compute and local manufacturing partnerships.
What PW Consulting’s report delivers — practical tools for 2026 decisions
-
Transparent market model and sensitivity scenarios. We provide a revenue‑model workbook calibrated to 2020–2025 historicals and stress‑tested across three adoption scenarios for 2026–2032, enabling procurement and M&A teams to quantify upside and downside outcomes.
-
Actionable go‑to‑market playbooks. Tailored templates for hardware OEMs, platform providers, content licensors, and institutional buyers (schools, training providers) that translate strategy into 90‑ to 180‑day implementation plans.
-
Procurement and total cost of ownership (TCO) frameworks. Comparative TCO for device fleets, subscription services, content licensing, and support — designed to assist budgeting decisions and vendor negotiations in 2026.
-
Compliance & safety checklists. Practical mappings of relevant standards and regulatory expectations — from algorithmic security benchmarks to content safety boundaries — with mitigation measures and vendor audit templates.
-
Competitive diagnostic dashboards. Benchmarks and strategic profiles for incumbents and challengers, highlighting capability gaps, partnership vectors, and consolidation targets.
Market dynamics you cannot ignore
-
Policy is a demand lever. Educational authorities have started to formalize AI literacy and classroom integration policies; these mandates create institutional procurement cycles and certification requirements that suppliers must meet.
-
Content safety and model governance are table stakes. National standards on model and corpus safety and industry group norms for content review are forcing vendors to invest in runtime filters, curated corpora, and transparent review processes.
-
Hardware and chip access remain strategic chokepoints. Export controls affecting advanced semiconductors and manufacturing equipment are pushing firms to re‑architect inference strategies, with implications for product roadmaps and unit economics.
-
Market concentration is meaningful. The market displays a mid‑tier concentration profile: leading firms account for a material share of revenue but leave substantial room for specialized and regional players. This structure encourages focused differentiation strategies.
Competitive landscape: what the leaders are signaling
-
iFLYTEK — positioning through content and model depth. Recent public filings and product intelligence indicate a strategic emphasis on cognitive large models and exclusive content partnerships. A notable early‑2026 content deal positions the firm to monetize immersive language learning experiences via licensed animation and engaging IP. Their reported acceleration in smart‑education revenue in 2025 underscores the commercial traction of that approach.
-
Yuanfudao (Xiaoyuan) — hardware innovation meets emotional intelligence. Product launches in 2025 revealed an approach that combines tablet computing with an intelligent base unit, prioritizing diagnostics, interactive companionship, and emotional interaction as differentiators for the K‑12 segment.
-
Zuoyebang, TAL and other incumbents — platform breadth and curricular alignment. These market participants are iterating on device ecosystems tightly coupled with existing content libraries and tutoring services, effectively selling an integrated learning proposition rather than standalone hardware.
-
Consumer electronics entrants and legacy educational hardware suppliers — incremental upgrade play. Brands with established distribution networks are rapidly adopting AI features and curriculum‑sync capabilities to defend shelf space and margins.
Implication for partners and investors: the current competitive moves show two clear, investable pathways. One route is content‑centric differentiation — securing pedagogically strong, exclusive IP and building learning analytics to demonstrate outcomes. The other is systems‑level differentiation — integrating hardware, edge inference, and device management to lower TCO and increase deployability in constrained networks.
Scenario planning — three plausible 2026 market trajectories
-
Scenario A: Accelerated adoption. Strong policy support, robust school budgets, and rapid content ecosystem maturation lead to higher‑than‑expected device and subscription uptake. Winners are firms that can scale content licensing and supply chains quickly.
-
Scenario B: Regulated consolidation. Tightened content and model governance increases certification costs, driving out undercapitalized players and favoring larger incumbents and certified niche suppliers.
-
Scenario C: Fragmented localization. Supply constraints and localization policies fragment the market into regional clusters, benefiting players with local content partnerships and compliant manufacturing footprints.
Actionable 90‑ to 360‑day playbook for executives (prioritized)
-
Perform a compliance audit against model safety and content standards. Map gaps, budget remediation, and secure third‑party attestations where necessary.
-
Lock content pipelines. Negotiate multi‑layer licensing deals (seasonal, exclusive, classroom bundles) to protect retention and pricing power.
-
Decide the compute posture. Run an architectural decision workshop to evaluate edge vs cloud trade‑offs given chip availability and latency/affordability constraints.
-
Diversify supply and manufacturing options. Build dual sourcing and local assembly pathways to reduce geopolitical and export risk exposure.
-
Embed measurement into product cycles. Define learning outcome metrics and A/B frameworks to demonstrate educational efficacy to procurement stakeholders.
-
Prepare M&A and partnership scouting. Target assets that close capability gaps — content studios, model safety providers, regional distribution networks — and accelerate time to market.
Why this report matters for 2026 decisions
Across product development, procurement, regulatory compliance, and corporate strategy, 2026 is a make‑or‑break year for organizations aiming to capture long‑term value in the AI learning machine space. PW Consulting’s market model quantifies the trajectory and the levers that most influence upside, while our playbooks translate those levers into executable, calendar‑driven steps. Whether you are a device OEM, content studio, platform provider, or institutional buyer, the analysis equips you to prioritize investments, negotiate from an informed position, and mitigate asymmetric risks tied to regulation and supply chains.
Next steps and how to access the full intelligence
This release is a strategic preview: it highlights the core trends, competitive moves, and decision frameworks that matter for 2026 without disclosing the granular regional and product split tables that form the basis of our customer‑facing model. The full report includes proprietary datasets, scenario‑driven revenue models, vendor scorecards, and downloadable implementation templates designed for immediate operational use. For teams planning budgets, partnership strategies, or bolt‑on acquisitions in 2026, the full suite of deliverables will materially shorten time to action and reduce execution risk.
To obtain the complete report, model workbook, and executive briefing package, please refer to the official PW Consulting distribution channel. Our analysts are available to walk through tailored implications for your organization and to run a bespoke 90‑day activation workshop aligned to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com