

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Estate Agent Fees Market Poised to Expand at a 4.5% CAGR — Brokerage and Residential Services Drive Momentum

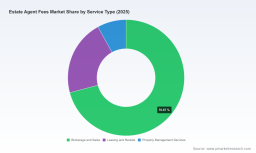
Worldwide Estate Agent Fees Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a preview of our forthcoming market study, Worldwide Estate Agent Fees Market (base year 2025). This briefing is intended as an executive-level compass for boards, CFOs, corporate development teams and private-equity sponsors planning decisions for 2026. It highlights the high-level market trajectory, the structural forces reshaping fee economics, and the pragmatic playbook items that senior leaders must address — while reserving the full segment-level tables, pricing matrices and financial models for the complete report.
Worldwide Estate Agent Fees Market
Market trajectory at a glance
The estate agent fees market shows steady, predictable expansion across our forecast window. On a global basis the market grows from approximately USD 331.6 Billion in 2025 to USD 451.2 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 4.5% over 2026–2032. Year-on-year movement in the near term remains resilient despite regulatory and structural shocks, offering a dependable aggregate revenue pool for incumbents and new entrants alike.
Worldwide Estate Agent Fees Market
Two strategic implications flow directly from this trajectory. First, modest but persistent growth favours scale and efficiency: firms that can compress cost-per-transaction and broaden ancillary revenue (leasing, property management, valuation services) will unlock disproportionate margins. Second, the predictability of top-line expansion masks high internal volatility by market and service line — reinforcing why granular segment intelligence (included in the full report) is essential before committing capital.
Worldwide Estate Agent Fees Market
Key structural drivers and headwinds
-
Regulatory reshaping of the buyer-seller fee model. 2024 and 2025 ushered in regulatory interventions that materially altered long-standing marketplace mechanics. A major antitrust settlement in the US and subsequent rule changes have accelerated decoupling of buyer-agent compensation from seller-paid listings in multiple markets, creating pricing pressure on traditional commission pools and introducing new contractual workstreams for buyer agents. Concurrently, increased disclosure and fee-display enforcement in mature markets has amplified price transparency.
-
Technology-driven disintermediation and productivity gains. Virtual brokerages and transactional platforms continue to reduce fixed overheads while enabling aggressive client-facing price points. At the same time, automation and AI-based valuation and lead qualification tools increase agent productivity, enabling alternative commission splits and subscription-based agent economics.
-
Labour-market realities. Agent remuneration, workforce availability and talent economics remain central to cost curves. Median wages and total employment dynamics in primary markets affect unit economics for traditional brokerages and the feasibility of high-touch service models.
-
Consumer habit shifts. Cost-conscious sellers and digitally empowered buyers are increasingly experimenting with fee structures, exclusive vs. multi-agency models, and fixed-fee offerings. These preferences are diversifying the pathways by which fees are negotiated and realized.
Why the 2026 planning horizon is decisive
2026 is a pivot year for market participants because regulatory, technological and consumer trends that accelerated in 2024–25 will either consolidate or fragment business models over the next 18–24 months. Strategic choices made now determine whether a franchise or brokerage becomes a fee-compressing low-cost player, a high-service premium operator, or a platform aggregator. Four practical considerations should guide boardroom debates:
-
Reassess pricing architecture. The transition to explicit buyer-side agreements and increased fee transparency mandates revisiting default commission schedules, introducing tiered offerings (basic listing vs. full-service advisory), and evaluating fixed-fee options for specific price bands.
-
Reconfigure agent economics. Consider alternative splits, capping models, and subscription-based agent participation to align incentives for higher productivity while preserving retention in competitive labour markets.
-
Invest in automation where ROI is demonstrable. Prioritise investments that shorten time-to-close, reduce manual paperwork and improve lead-to-conversion ratios. Focus on tools with measurable per-transaction cost reductions and short payback periods.
-
Adapt market entry and M&A playbooks. With growth concentrated in specific service lines and geographies, M&A should be used tactically to acquire digital capabilities, local market share, or profitable ancillary services rather than as broad roll-up strategies without integration plans.
Report practicalities: what the full study delivers
Our complete Worldwide Estate Agent Fees Market report (base year 2025, forecast 2026–2032) is built for decision-makers who need executable intelligence, not just descriptive statistics. The report includes:
-
Top-down market sizing and a seven-year forecast with sensitivity scenarios (baseline, accelerated digital adoption, and regulatory stress cases).
-
Comprehensive revenue models and downloadable financial templates that allow users to stress-test commission schedules, agent-split alternatives and subscription models.
-
Commercial playbooks: productised pricing options, channel strategies for buyer vs. seller acquisition, and retention levers for high-performing agents.
-
Regulatory risk matrix and mitigation options by jurisdiction, including play-forces where enforcement has already shifted market mechanics.
-
Primary-sourced consumer and agent surveys, plus transaction-level analytics that highlight where fee leakage occurs and how to capture recurring revenues.
Note: this preview intentionally omits the granular market splits by region, property type and service line. Those core segment tables and the transaction-level datasets are available only in the full report and the accompanying data pack.
Competitive landscape — profiles and strategic postures
The market remains fragmented at the global scale, with a mix of legacy franchise networks, tech-first virtual brokerages, and full-service consultancies. Among notable players:
-
Large franchise networks (example profile). Established franchises maintain extensive agent networks and strong brand recognition across multiple territories. Their strategic choices focus on standardising service quality, improving agent retention and selectively adopting capex-light digital capabilities.
-
Agent-centric, co-operative models. Firms adopting agent-owned economics compete on proposition flexibility and recruitment appeal. Their success depends on balancing generous agent splits with centralised marketing and technology provision to avoid margin erosion.
-
Virtual/transactional brokerages. Purely virtual platforms concentrate on low per-transaction fees and streamlined processes. They gain share where cost-sensitive consumers prioritise price over full-service advisory.
-
Consultancy-style firms. Specialist consultancies and high-end agencies defend premium fee bands by focusing on luxury and complex transactions where advisory value is tangible.
Our full report contains company-level strategic heatmaps and investment profiles for leading firms, illustrating where each player is likely to expand, retrench or double-down through 2026.
Actionable priorities for executives in 2026
For leaders preparing 2026 plans, we recommend a three-tier programme of work that can be completed within a standard financial planning cycle:
-
90-day diagnostic. Rapid review of current pricing, agent economics and digital capability gaps. Deliverable: prioritized list of low-effort, high-impact changes (e.g., contract templates, fee disclosure updates, targeted automation pilots).
-
6–9 month transformation sprint. Implement revised pricing architecture, launch pilot alternative service tiers, and roll out at least one back-office automation to reduce cost-per-transaction. Deliverable: a repeatable, measurable improvement in gross margin per transaction.
-
18–24 month strategic positioning. Build or acquire platform capabilities to lock-in recurring revenues (property management, leasing services, digital valuation tools) and revise M&A criteria to prioritise capability over scale alone. Deliverable: a defensible multiyear revenue mix that mitigates single-channel fee pressure.
Governance: monitoring and KPIs
We advise boards to require a small set of leading indicators to monitor execution: effective fee rate (net of rebates), average time-to-close, agent productivity (transactions per agent per year), churned-agent rate, and share of recurring revenue. Quarterly reviews should include scenario updates reflecting regulatory shifts and consumer pricing experiments.
Conclusion and call to action
The global estate agent fees market offers steady aggregate growth but increasing structural complexity. 2026 will reward organisations that move quickly to unbundle legacy commission models, redesign agent economics for a hybrid physical-digital world, and capture recurring revenue streams that are less exposed to transactional compression.
PW Consulting’s full Worldwide Estate Agent Fees Market report provides the granular segmentation, regional models, pricing matrices and executable playbooks required to make those choices with confidence. For boards and investors planning 2026 strategies, the full dataset and our workshop packages illuminate where to reduce risk, where to invest and how to structure deals that align incentives across the value chain.
To access the complete report, data appendices and bespoke advisory options, please visit the PW Consulting research portal or contact our Industry Practice team for a briefing and demo of the downloadable financial models.
For detailed analysis of this topic, please visit the official page: Worldwide Estate Agent Fees Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com