

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cold Ramming Paste Market to Top USD 640.9 Million by 2032, Expanding at 4.0% CAGR as Asia‑Pacific and Anthracite‑Based CRP Drive Demand

Worldwide Cold Ramming Paste (CRP) Market: Strategic Imperatives for 2026 — PW Consulting Preview
As industrial operators and upstream suppliers prepare their 2026 strategies, PW Consulting’s forthcoming Worldwide Cold Ramming Paste (CRP) Market report offers timely, action-oriented intelligence. Our analysis traces the market’s evolution from a post-2020 recovery phase through the 2025 base year and projects forward across 2026–2032, delivering a fact-based foundation for capital allocation, supplier strategy, and regulatory risk mitigation.
Worldwide Cold Ramming Paste (CRP) Market
Executive snapshot
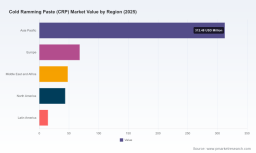
The CRP market has demonstrated resilient expansion since 2020, rising from USD 385.4 Million in 2020 to USD 487.04 Million in the 2025 base year. Our forecast models—incorporating demand drivers, raw material cost trajectories, and regulatory scenarios—project steady growth through 2032, with the total market approaching USD 640.9 Million by the end of the forecast window. This implies an expected compound annual growth rate (CAGR) of approximately 4.0% for the forecast period (2026–2032).
Worldwide Cold Ramming Paste (CRP) Market
Why this matters for 2026 decision-makers
- Investment timing: The market’s steady CAGR signals that selective capacity investments and targeted process upgrades can yield consistent returns, but timing must be aligned with supply-chain dynamics and technology transitions described below.
- Supplier strategy: The market presents a semi-concentrated supplier landscape. The three largest players account for a meaningful share of capacity (our CR3 measure), and the top five further consolidate control—an important consideration for procurement negotiation levers and dual-sourcing plans.
- Regulatory and ESG alignment: Shifts in binder technology and PAH-related controls are reshaping product specifications. Organizations that proactively adopt low- or zero-PAH CRP formulations will minimize compliance risk and protect smelter operational continuity.
Market trajectory and volatility drivers
Behind the headline growth are several compounding drivers and punctuated risks. Aluminum smelting activities and furnace maintenance cycles underpin base-level CRP demand, while commodity cycles—especially anthracite and pitch feedstocks—introduce short-term volatility. Our historical reconstruction (2020–2025) captures pandemic impacts, post-pandemic restarts, and 2024–2025 supply realignments, which inform our 2026 scenario planning.
Worldwide Cold Ramming Paste (CRP) Market
On the forecast horizon, incremental gains are expected from process optimization at smelting plants, modest capacity additions among incumbent suppliers, and progressive substitution of alternative binders in regulated jurisdictions. These forces translate into steady volume expansion coupled with periodic price sensitivity tied to feedstock swings.
Raw materials, formulations, and regulatory dynamics
- Feedstock fundamentals: CRP formulations continue to rely on calcined anthracite, artificial graphite, and traditional pitch binders. These materials determine thermal stability, electrical resistivity, and mechanical integrity in cathode and furnace linings.
- Binder evolution: Coal tar pitch—historically dominant—remains technically effective but is increasingly scrutinized due to polycyclic aromatic hydrocarbons (PAHs). Over the last decade, industry players and select smelters have accelerated adoption of alternatives (furan resins, lignin-based binders, treated pitches) to meet occupational health and environmental requirements.
- Regulatory pressure and innovation: Case studies and vendor trials demonstrate viable low- or zero-PAH CRP variants. These alternatives are no longer purely niche: they are a strategic necessity in jurisdictions with strict emissions and worker-safety regimes. Companies that integrate eco-friendly chemistry into product lines will gain market access and reduce lifecycle liabilities.
Competitive landscape — who to watch
The CRP supplier field mixes multi-national materials groups, regional specialists, and technology-focused innovators. Key company archetypes and strategic positions include:
- Global materials integrators with vertically integrated upstream operations and global distribution footprints. These players can leverage R&D and cross-border manufacturing to supply standardized CRP and specialized cathode variants.
- Regional manufacturers with localized feedstock advantage and competitive cost structures. Many of these suppliers serve nearby smelter clusters and offer rapid technical support for lining repairs and retrofit projects.
- Specialty innovators introducing eco-friendly and low-emission CRP formulations. While often smaller in scale, these companies can command strategic premium positioning by addressing PAH and other environmental constraints.
Representative firms exemplifying these archetypes include long-established multinational producers supplying cathode ramming paste variants tailored to aluminum electrolysis cells, regional manufacturers with deep technical experience in high-temperature environments, and niche developers of zero-PAH products that have been validated at industrial sites. Our full report assesses these firms across production footprint, product portfolio, R&D investments, and commercial channels—delivering a supplier scorecard essential for procurement and M&A screening.
Market concentration and strategic implications
Concentration metrics indicate a market in which a limited set of suppliers command a significant portion of capacity—our CR3 and CR5 measures show meaningful aggregate shares. For buyers, this concentration translates into two practical implications: first, the need for robust dual- or multi-sourcing strategies to mitigate single-supplier exposure; second, the opportunity to leverage scale by partnering with lead suppliers for co-development of low-emission CRP formulations.
Operational and commercial playbook for 2026
For operating companies, smelters, and midstream suppliers, the path to resilient 2026 operations should include:
- Technical validation: Run pilot trials of low-PAH and alternative-binder CRPs during scheduled maintenance windows to verify thermal, electrical, and mechanical performance under plant-specific conditions.
- Supply-security audits: Map current single points of failure in CRP supply and create contingency contracts that balance cost with delivery reliability.
- Lifecycle cost modeling: Move beyond unit price to incorporate occupational safety costs, potential emission-control capex, and downstream yield impacts when comparing CRP formulations.
- Strategic partnerships: Consider co-development agreements with suppliers that have proven eco-friendly tech or with regional producers positioned for expansion—especially where proximity to anthracite or specialized graphite sources confers logistics advantage.
Report composition — practical contents that guide action
PW Consulting’s full report (base year 2025; historical 2020–2025; forecast 2026–2032) is built for practitioners. Highlights include:
- Top-down and bottom-up market sizing with sensitivity scenarios that stress-test demand under multiple commodity and regulatory pathways.
- Supply-side mapping: production footprints, capacity estimates, and a supplier benchmarking toolkit that ranks vendors on technical breadth, environmental credentials, and commercial reach.
- Feedstock cost scenarios and stress-tests: modeled impacts of anthracite and pitch price swings on CRP margins and smelter operating costs.
- Regulatory impact analysis: jurisdictional heatmaps for PAH and VOC-related rules, and an emissions-compliance roadmap for transitioning to alternative binders.
- Commercial playbooks: procurement strategies, contractual templates for co-development, and pricing indices for index-linked supply agreements.
- M&A and partnership pipeline: screened target lists and valuation frameworks for bolt-on acquisitions or strategic JV formations (designed for acquirers seeking rapid entry into eco-friendly CRP production).
- Excel model deliverable: configurable demand and revenue model enabling users to run custom scenarios for budgeting and strategic planning.
How to use this intelligence in Q1–Q2 2026 planning cycles
Leaders should treat the report as a decision-grade toolkit. Specific short-term actions we recommend for Q1–Q2 2026 include:
- Finalize pilot schedules with two alternate CRP formulations (conventional and low-PAH) to inform procurement specs for the coming maintenance season.
- Run a supplier risk heatmap, using our benchmark outputs, to identify one incumbent supplier for expansion and one alternative supplier for contingency supply.
- Model the impact of alternative-binder adoption on total cost of ownership (TCO) across a five-year window, including potential capex offsets from lower emissions-control investments.
Concluding perspective
The CRP market’s mid-single-digit CAGR and semi-concentrated supplier structure create a predictable yet strategically rich environment. Firms that combine operational discipline with proactive supplier engagement and early adoption of low-emission chemistries will both reduce regulatory exposure and unlock incremental value. PW Consulting’s full Worldwide Cold Ramming Paste report translates this dynamic landscape into concrete, executable steps—backed by scenario-tested numbers, supplier scorecards, and tactical playbooks.
For procurement leads, plant managers, and corporate strategists planning for 2026, this is not a market to treat as a commodity. It is a technical material whose choice reverberates through safety, compliance, thermal performance, and bottom-line economics. Our full report provides the granular segmentation, regional analysis, and supplier-specific intelligence you will need to act confidently; visit our report page to access the complete study and downloadable models.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com