

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Robotic Scope Holder Market to Expand at 7.5% CAGR, Reaching USD 514.3 Million by 2032

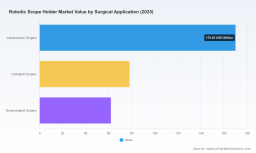
Worldwide Robotic Scope Holder Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases an executive preview of our forthcoming Worldwide Robotic Scope Holder Market report. Built on a base year of 2025 with a historical lens across 2020–2025 and a forward-looking forecast to 2032, this study synthesizes commercial, clinical, regulatory and technology signals that will shape procurement, R&D and M&A choices in 2026 and beyond. The global market for robotic scope holders has demonstrated steady expansion—rising from USD 215.94 Million in 2020 to USD 310.0 Million in 2025—and PW Consulting projects continued momentum with a compound annual growth rate of 7.5% over the 2026–2032 forecast window to reach an expected USD 514.3 Million by 2032. This preview outlines why those topline dynamics matter, the actionable frameworks our full report delivers, and a compact competitive read on the leading players influencing the space.
Worldwide Robotic Scope Holder Market
What the full report delivers (practical, actionable content)
- Rigorous market sizing and scenario-driven forecasts (base year 2025; historical 2020–2025; forecast 2026–2032, USD Million), including sensitivity analyses that isolate demand shocks, reimbursement shifts and supply constraints.
- Go-to-market playbooks for suppliers and hospitals: channel strategies, service and consumable monetization, direct vs distributor models, and field service economics for high-uptime operating-room devices.
- Regulatory and reimbursement roadmaps tailored to product and market-entry strategies—covering electrical safety standards, 510(k) pathways and CPT-level reimbursement levers relevant to scope positioning systems.
- Technology and integration matrices: interoperability requirements with surgical robots and endoscope platforms, AI-enabled positioning roadmaps, and sterilization/material constraints affecting product design and lifecycle cost.
- Buyer decision frameworks and procurement templates: clinical value dossiers, ROI calculations for hospital administrators, and pilot-program design for rapid adoption in high-volume laparoscopic centers.
- Competitive intelligence and supplier scorecards: product capability benchmarking, channel strength, geographic reach and strategic M&A targets—ranked to help prioritize partnership or acquisition targets.
- Case studies and clinical-value evidence snapshots showing typical OR time savings, staff reallocation, and infection-control benefits observed in early-adopter institutions.
Why this matters for 2026 strategic planning
After a robust recovery and expansion phase in the first half of the decade, the robotic scope holder market is entering a commercialization phase where product differentiation, interoperability and service economics will determine commercial winners. With an overall market expanding from USD 215.94 Million in 2020 to USD 310.0 Million in 2025 and projecting to exceed half a billion USD by 2032 at a 7.5% CAGR, enterprises must decide in 2026 whether to: (a) accelerate investment to capture share in the next growth wave, (b) form partnerships to extend product ecosystems into hybrid robotic procedures, or (c) pursue a defensive consolidation strategy to protect installed-base revenue.
Worldwide Robotic Scope Holder Market
The market’s structural features—moderate-to-high concentration among a small group of committed suppliers—create both entry barriers and M&A opportunities. Our concentration analysis shows that the top three providers control a meaningful portion of the market, with the top five further amplifying consolidation incentives. For manufacturers and private equity investors, this means well-executed bolt-on acquisitions, or differentiated niche plays (e.g., AI-assisted positioning, service-led revenue models), can rapidly improve profitability and scale.
Worldwide Robotic Scope Holder Market
Competitive landscape — a tactical snapshot
- Mitaka Kohki (Tokyo, Japan) — Known for clinical-grade robotic holders such as the MS-51 and MS-6A, Mitaka combines multi-axis mechanics with voice control and is actively integrating with larger robotic platforms. A recent product update announced in October 2024 emphasized AI-assisted positioning enhancements intended to speed intraoperative set-up and improve targeting precision—an area where clinical evidence and software validation will differentiate leaders.
- FreeHand Surgical (London, UK) — The company’s FreeHand 2.0 unit emphasizes voice-activated control and OR ergonomics. With regulatory clearances supporting global use and high-visibility demonstrations (notably at SAGES in March 2024), FreeHand is positioning itself around ease-of-use and hybrid-procedure integration—key selling points for ambulatory surgery centers and tertiary hospitals seeking predictable OR throughput gains.
- EndoControl / Medtronic (Rennes, France; now part of Medtronic) — The ViKY system, acquired in 2014 and supported through Medtronic’s global distribution, benefits from broader device integration and scale. Notably, expanded 510(k) clearances reported in late 2023 have improved compatibility with next-generation endoscopes and lowered friction for hospital integration projects.
- Olympus (Tokyo, Japan) — Leveraging its endoscope and imaging platforms, Olympus offers robotic positioning complements that integrate with their VISERA ELITE systems. For OEMs and hospital systems, vendor-aligned ecosystems remain attractive because they reduce integration risk and support bundled-service economics.
Collectively, these players illustrate two competing strategic models: platform-led incumbents that bundle hardware, service and consumables versus specialist innovators that compete on focused features (voice control, AI positioning, OR ergonomics). In 2026, buyers will reward proven integration with existing OR ecosystems, validated clinical outcomes, and flexible procurement models.
Regulatory, reimbursement and materials dynamics
- Electrical safety and OR compliance: Robotic scope holders must conform to IEC 60601-1 and associated IEC collateral standards to ensure safe operation in clinical environments. These standards affect design choices and lead times for verification and validation activities.
- Reimbursement pathways and clinical coding: In markets where procedure coding exists for computer-assisted positioning, such as CPT-coded pathways covering scope navigation adjuncts, the ability to demonstrate quantifiable OR time savings and clinical benefit materially improves hospital procurement economics.
- Materials and sterilization: Typical designs employ medical-grade stainless steels and titanium alloys and require autoclave-compatible architectures validated to withstand repeated sterilization cycles. Material choices drive lifecycle costs, service intervals and total cost of ownership models hospitals use in procurement.
- Regulatory classification and safety history: These devices are generally regulated under Class II pathways in major markets, often requiring 510(k)-style filings in the U.S. The field has shown a good safety record with no prominent recalls for major models since 2020—an important trust signal for hospital risk committees.
Strategic imperatives for suppliers, investors and health systems in 2026
- Prioritize interoperability: Ensure compatibility with major endoscope and robotic platforms. Integration agreements and supported interfaces are short-term enablers of scale.
- Shift to outcome-based evidence generation: Invest in multi-center pilots that quantify OR time savings, staffing efficiencies and patient safety benefits—data that unlocks procurement approvals and reimbursement discussions.
- Design for the service economy: Field service, predictive maintenance and subscription-based models can turn hardware into recurring revenue streams and improve lifetime margins.
- Optimize regulatory and clinical timelines: Early engagement with regulatory bodies and health technology assessment teams reduces time-to-market risk; plan 510(k) strategies with enough clinical evidence to broaden labels and hospital uptake.
- Pursue targeted consolidation: For acquirers, the near-term focus should be bolt-ons that extend product portfolios into AI-enabled positioning or strengthen service networks in priority geographies.
What we intentionally withhold (and why)
True to the “trailer” principle behind this preview, we have presented high-confidence market trajectories, structural insights and competitive signals while withholding the granular segmentation tables and line-by-line regional and application forecasts that drive specific go-to-market and M&A models. Those detailed regional splits, product-level revenue breakdowns and per-application forecasts—together with supplier scorecards, full financial models, and downloadable slide decks—are available in the complete PW Consulting report and accompanying data workbook. This approach preserves the strategic value of the dataset for subscribers while providing executives a clear and actionable assessment of where to focus 2026 plans.
Next steps for senior leaders
Executives preparing budgets and investment priorities for 2026 should use this preview as a trigger to: (1) validate product roadmaps against interoperability and sterilization constraints; (2) allocate modest budgets for evidence-generation pilots in target hospitals; (3) map potential partners and acquisition targets against our supplier scorecard; and (4) update procurement models to capture service and consumable revenue potential. For investors, the period through 2027 will determine which platform players can convert clinical acceptance into predictable, recurring revenues.
To obtain the full dataset, comprehensive segmentation, supplier scorecards and the downloadable financial model behind these conclusions, please visit PW Consulting’s report page or contact our Client Services team for an executive briefing and licensing options. PW Consulting’s Worldwide Robotic Scope Holder Market report is purpose-built to convert market intelligence into executable strategies for 2026—and to help leaders prioritize where to invest, partner and accelerate adoption in the OR of the future.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com