

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Intelligent Well Completion Market to Reach USD 2,810.26 Million by 2032 at 8.45% CAGR — Offshore Deepwater Segment Leads with USD 1,003.42 Million
By pmarketresearch, 2026-07-17
Worldwide Intelligent Well Completion Market: Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Intelligent Well Completion Market report (base year 2025). As operators and suppliers plan budgets and partnerships for 2026, this briefing highlights the macro trajectories, competitive dynamics, and near-term commercial risks that will shape capital allocation and technology choices—without disclosing the granular segment tables reserved for the full report.
Worldwide Intelligent Well Completion Market
Why this report matters for 2026 planning
Intelligent well completions are moving from niche demonstrations to mainstream field architectures. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 8.45% over the forecast window, supported by accelerating deployments in deepwater, electrified completions, and multi-zone control architectures. With a base-year vantage point in 2025, PW Consulting’s report synthesizes historical performance, near-term project ramps, and supplier capability to deliver actionable guidance for procurement, technology roadmaps, and partner selection in 2026.
Worldwide Intelligent Well Completion Market
- Investment timing: The sector is entering a phase of steady global revenue growth—continuity that favors multi-year supplier partnerships and staged technology rollouts rather than one-off trials.
- Risk calibration: Near-term cost inflation and trade-policy shifts mean that procurement processes must embed scenario modeling for materials and logistics.
- Value capture: Operators can improve EUR and recovery through digital-first completions, but capture requires integrated lifecycle plans combining downhole hardware, telemetry, and software services.
Market trajectory—what the topline numbers indicate
From our base year lens, the intelligent completion market has moved beyond early-adopter volatility into a structurally growing industry. Market revenues show a multi-year upward path reflecting a steady compound growth profile. This growth is being driven by continued investment in deepwater pre-salt plays, migration toward electric completions and multi-zone control, and the increasing use of permanent downhole sensing and fiber-optic systems for production optimization.
Worldwide Intelligent Well Completion Market
For executives, the message is clear: the market is large enough and growing fast enough that technology decisions made in 2026—platform selection, architecture standardization, and supplier contracting model—will materially influence portfolio performance for the remainder of the decade.
Competitive landscape—who is shaping standards and supply
The market structure demonstrates meaningful concentration among a handful of global systems suppliers and specialized technology firms. Top-tier energy services companies have the scale to deliver integrated intelligent completion packages, while niche and regional providers focus on differentiated components, autonomous control systems, and intervention tools.
- Global integrators: Major service groups—companies with deep completion systems portfolios and global project footprints—continue to win large-scale deepwater contracts and to invest in electric and telemetry-enabled platforms. Their offerings bundle permanent gauges, interval control valves, wet-mate connectors, and surface-to-subsurface integration services.
- Specialists and independents: Technology-focused firms are advancing inflow control devices, downhole robotics, and wireless/autonomous control solutions that simplify installations and reduce running costs—creating modular alternatives for field architects.
- Service partners and regional houses: Regional service firms and national oilfield providers are increasingly important in local market access, running expertise, and operator-specific interface adaptations, particularly in the Middle East and Latin America.
Recent contract awards and deployments illustrate these dynamics. In late 2025, several large completions contracts were awarded for ultra-deepwater pre-salt projects and multi-zone developments, underscoring the strategic importance of scale and bundled delivery capability. In parallel, milestone deployments of long-lateral, high-zone-count intelligent completions have set new operational benchmarks and validated all-electric and fiber-enabled architectures in challenging environments.
Report coverage—practical, transaction-focused deliverables
PW Consulting’s full report is designed for commercial teams, CTO offices, and asset managers who need executable intelligence rather than academic summaries. Key operational outputs include:
- Multi-scenario revenue and demand models through the forecast window, allowing sensitivity testing against oil-price curves, electrification adoption rates, and drilling activity scenarios.
- Procurement playbooks that map risk allocation options for CapEx vs. OpEx delivery models, warranty frameworks, and incentive-aligned contracting structures for long-term monitoring services.
- Vendor evaluation frameworks and contract checklists to weigh trade-offs between turnkey systems from global integrators and component-level sourcing from specialist suppliers.
- Engineering-to-commercial alignment guides that translate downhole architecture choices into surface system requirements, intervention plans, and contingency budgets.
- Case studies of recent field-scale deployments highlighting technical pitfalls, OPEX impacts of permanent sensing, and lessons in running and intervention logistics for multi-zone completions.
To preserve the utility of this preview and adhere to the “trailer” principle, detailed segment-level forecasts and supplier share tables are embargoed to the full report. PW Consulting’s proprietary models, including component-level cost curves and regional demand scenarios, are made available in the complete deliverable.
Dynamics and near-term supply-side risks
Several material and regulatory trends are compressing margins and reshaping vendor selection criteria in 2026:
- Raw material inflation: Supply disruptions in metals markets have driven sharp price growth for aluminum and steel inputs in early 2026. These swings materially affect the bill-of-materials for completion hardware and encourage procurement teams to lock prices or adopt hedging strategies.
- Trade policy and tariffs: Expanded tariff measures on certain non-compliant steel and aluminum products raise landed costs and increase the attractiveness of localized manufacturing or near-shore sourcing for critical components.
- Standards and qualification: Industry standardization efforts advanced in 2025 around control valve qualification and electric-completion interfaces. Participation in these standards bodies is now a strategic lever—shaping interoperability and influencing long-term adoption curves for proprietary systems.
- Operator adoption patterns: High-value pre-salt and deepwater fields remain adoption leaders, with operators scaling intelligent completions into large portfolios. As adoption broadens, suppliers must prove lifecycle reliability and low-intervention performance to win repeat business.
Strategic implications for executives in 2026
Executives making 2026 decisions should orient around four practical priorities:
- Lock the supply chain and cost base: Negotiate multi-year material procurement and explore near-shore fabrication partnerships to mitigate tariff and freight volatility. Include material-cost pass-through clauses that are index-linked to producer-price or metal-spot indices.
- Prioritize systems that lower lifecycle interventions: Favor technologies and vendors with demonstrable reductions in well intervention frequency. The economic value of reduced intervention is often greater than incremental upfront hardware cost.
- Standardize interfaces and participate in specs: Engage in API and industry working groups to influence interoperability standards—reducing vendor lock-in risk while accelerating field-scale rollouts.
- Design contracts for performance alignment: Move beyond pure supply agreements toward outcome-linked models (availability, production uplift, or reduced intervention). Incorporate digital twin and data-sharing terms to unlock joint optimization opportunities.
Vendor watch—what to watch for among market leaders
Large service integrators continue to command a meaningful portion of market activity through bundled systems and global execution capability. At the same time, targeted innovations from independents—wireless autonomous control, advanced inflow control devices, downhole robotics—are reshaping the supplier value ladder. Our report profiles the strategies, recent wins, and technical roadmaps of the sector’s leading players, evaluating their ability to deliver scale, reliability, and software-enabled services.
Notably, several major contract awards and deployments announced in late 2025 validate both scale and technology shifts. These include multi-well, ultra-deepwater contracts for intelligent completion packages and high-zone-count deployments that demonstrate the practicality of all-electric and fiber-based monitoring solutions in long-lateral wells. Such wins are instructive: they signal which supplier capabilities will be essential for large offshore developers and which technologies are maturing into repeatable field solutions.
Next steps and how to access the full intelligence
PW Consulting’s full Worldwide Intelligent Well Completion Market report delivers the detailed segment forecasts, supplier market shares, and procurement templates needed for 2026 decision-making. The public preview you have read is intended to frame the strategic choices and near-term risks; it intentionally withholds the granular forecasts and company-by-company market share tables that underpin commercial negotiations.
For executives preparing 2026 budgets or negotiating multi-year completion contracts, the full report is a practical tool—combining scenario-ready financial models, supplier scorecards, and contract language recommendations. To request an executive briefing and obtain access to the full deliverable, contact PW Consulting’s Industry Research Desk or visit our reports page.
PW Consulting’s analysts remain available to run tailored sensitivity scenarios for your asset base, provide supplier due-diligence workshops, and support negotiation strategy for intelligent completion programs being tendered in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent Well Completion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Zero‑Drift Op Amp Market to Rise from USD 468.25 Million in 2025 to USD 794.7 Million by 2032 at a 7.85% CAGR — Asia‑Pacific Leads with USD 216.71M
By pmarketresearch, 2026-07-17
Worldwide Zero-Drift Op Amp Market — Strategic Outlook for 2026
PW Consulting’s newest market research release delivers a focused, practitioner-ready view of the global zero-drift operational amplifier (op amp) market to inform executive decision-making in 2026. Built on an analyzed base year of 2025 and a detailed forecast through 2032, the study quantifies a continued expansion of the addressable market at a compound annual growth rate of 7.85%. The market’s trajectory from the 2020–2025 historical window into the 2026–2032 forecast period creates a clear decision horizon for product strategy, supply-chain positioning, compliance roadmaps, and M&A activity.
Worldwide Zero-Drift Op Amp Market
Why this report matters for 2026 decision-makers
- Market timing: Determines when to accelerate product launches or postpone costly qualifications based on a multi-scenario demand outlook.
- Technology choice: Clarifies trade-offs between chopper-stabilized and auto-zero topologies across target end markets and power profiles.
- Supply resilience: Quantifies exposure to raw-material and manufacturing lead-time pressures, enabling defensible inventory and sourcing decisions.
- Regulatory & trade risk mitigation: Reconciles evolving RoHS and export-control regimes with qualification plans and regional go-to-market strategies.
- Commercial playbook: Provides a template for pricing, contract terms, and design-in incentives that preserve margin while accelerating adoption.
Report scope and practical deliverables
The study is designed for product leaders, supply-chain executives, corporate development teams, and board-level strategists who need operational recommendations, not just descriptive statistics. Deliverables include:
Worldwide Zero-Drift Op Amp Market
- Top-down market sizing and bottom-up forecast models by technology, application cluster, and region (interactive Excel models included).
- Scenario analysis (baseline, optimistic, downside) that stress-tests demand under alternate lead-time, pricing, and regulatory assumptions.
- Competitive benchmarking: capability maps, go-to-market posture, and product-family gap analysis for the leading vendors.
- Supply-chain risk matrix covering raw materials, wafer supply, packaging constraints, and typical lead-time volatility with mitigation playbooks.
- Regulatory impact assessment and redesign checklist for compliance with upcoming packaging and chemical content rules.
- Commercial toolkit: price-band modelling, NDAs and volume-discount templates, and a prioritized list of design-in incentives by OEM segment.
- M&A and partnership heatmap identifying target profiles for tuck-in acquisitions, IP buys, or JV candidates to accelerate access to niche capabilities.
Macro and supply dynamics that will shape 2026
The market’s healthy mid-single-digit-to-high-single-digit CAGR is real but will be moderated by several structural dynamics that the report models explicitly:
Worldwide Zero-Drift Op Amp Market
- Raw-material pressure: High-purity silicon wafer costs rose materially in early 2025, creating margin and sourcing stress for precision analog manufacturers. Companies that lock multi-quarter supply or adopt longer-term purchase agreements will gain competitive stability.
- Lead-time normalization: Precision analog lead times reached industry highs in late 2025. Extended procurement cycles and phased inventory strategies are now part of the commercial equation; the report provides a playbook for tiered buffer policies across product life-cycle stages.
- Regulatory tightening: New EU packaging directives with stricter halogen requirements take effect in 2026, forcing early qualification of compliant packaging and potential requalification of existing part numbers. The study includes a compliance timeline and cost buckets for package redesign and retesting.
- Export controls and geopolitics: Restrictions on the transfer of sub-10 µV-offset devices to certain markets introduce technology-class trade risk. The analysis recommends architecture-level adjustments and licensing strategies to preserve market access without compromising IP or performance.
Competitive landscape — profiles and strategic implications
The zero-drift op amp market exhibits meaningful concentration among a small number of large analog specialists. The top-three vendors control a majority of the market, and the top-five capture more than three-quarters of revenue—an important structural reality for firms planning to enter or expand in this space. Our report’s competitive chapter synthesizes public product portfolios, go-to-market posture, and recent product activity to identify durable competitive advantages and exploitable gaps.
- Texas Instruments (Dallas, TX) — A broad zero-drift offering, driven by chopper-stabilized architectures and deep channels into industrial and instrumentation segments. Recent product introductions underscore TI’s focus on lower-offset parts for high-accuracy current sensing.
- Analog Devices (Wilmington, MA) — Strong in auto-zero topologies and high-performance sensor interfaces, with a roadmap that prioritizes ultra-low offset and bridge-amplifier targeted devices. New sampling programs indicate aggressive product refresh cadence.
- STMicroelectronics (Geneva) — Focused efforts on automotive qualification and consumer-adjacent measurement modules, with AEC-Q100 product updates that reduce time-to-adoption in automotive OEM programs.
- Infineon Technologies (Neubiberg, Germany) — Automotive and industrial controls specialist with product families optimized for noise rejection and CMRR in harsh environments.
- Microchip Technology (Chandler, AZ) — Emphasizes low-power, battery-friendly chopper-stabilized devices for portable instrumentation and embedded measurement systems.
- NXP Semiconductors (Eindhoven) — Integrates precision analog into broader automotive and IoT offerings, layering diagnostics and system-level integration to accelerate adoption in complex platforms.
Recent vendor moves—product launches and catalog updates—signal an intensifying product race at both the ultra-low-offset end and the more cost-sensitive segments. The market concentration metrics highlight barriers to entry at scale but also indicate opportunity windows for focused niche players and acquirers looking for differentiated IP or customer access.
Strategic implications by application cluster
- Automotive (BMS & sensors) — Qualification timelines and AEC standards dominate decisions. Prioritize supply agreements with automotive-qualified fabs and early packaging compliance to avoid launch slippage.
- Industrial process control — Reliability and noise immunity sell; value-based pricing anchored to long-term service-level agreements and field-reliability metrics will win deals.
- Medical instrumentation — Certification and traceability are table stakes. Vendors should bundle design support, qualification labs access, and extended lifecycles into commercial proposals.
- Test & measurement — Performance delta is the primary purchase driver. Speed-to-market with incremental performance improvements and bundled calibration services creates differentiation.
Five actionable recommendations for 2026 planning
- Adopt a dual-architecture product strategy: Retain both chopper-stabilized and auto-zero offerings or partnerships to cover the widest set of performance/power trade-offs and to reduce single-technology risk.
- Lock strategic supply: Negotiate multi-quarter wafer and packaging contracts with escalator clauses, and establish prioritized allocation terms for critical SKUs to shield design wins from lead-time shocks.
- Accelerate compliance engineering: Begin packaging and substance requalification now to meet new EU packaging requirements and to preempt downstream customer requalification costs.
- Design market-access workarounds: For constrained export scenarios, pursue modular architectures that allow lower-risk functional swaps or controlled sell-through with licensing where necessary.
- Be opportunistic on M&A and partnerships: Target small IP-rich firms offering unique offset reduction techniques or packaging process advantages that shorten qualification timelines and widen addressable OEM relationships.
What’s inside the full PW Consulting report — and what we intentionally withhold
The full study provides the granular datasets, segmented forecasts, supplier-cost breakouts, and interactive models that enable transaction-grade diligence and product-business planning. In keeping with our role as an intelligence gatekeeper, this executive release demonstrates our analytical depth but deliberately withholds the detailed regional and subsegment share tables and raw numerical splits that are reserved for licensed report holders. This approach allows potential buyers to validate strategic hypotheses here while preserving the structured data and scenario files that accelerate execution when you engage.
Next steps for executive teams
If you are recalibrating product roadmaps, drafting 2026 supply agreements, evaluating acquisition targets, or preparing for compliance-driven redesigns, PW Consulting’s Worldwide Zero-Drift Op Amp Market report offers the actionable models and proprietary vendor benchmarking to shorten decision cycles and de-risk execution. Licensed purchasers receive the full data annex, vendor scorecards, and the interactive forecast model we use to stress-test executive scenarios.
PW Consulting stands ready to translate these findings into a bespoke strategy workshop for product line leaders, procurement heads, or corporate development teams. Contact our industry specialists to unlock the full dataset and schedule a strategy session that aligns the report’s insights with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-Drift Op Amp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Structural Conductive Polymer Market Poised to Reach USD 1.04 Billion by 2032, Growing at an 8.12% CAGR
By pmarketresearch, 2026-07-17
Worldwide Structural Conductive Polymer Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, Worldwide Structural Conductive Polymer Market (base year 2025), delivers a focused, actionable intelligence product designed to inform capital allocation, product strategy, and supply-chain decisions through 2026 and beyond. Grounded in a six‑year historical analysis (2020–2025) and a forward-looking forecast (2026–2032), the report models market expansion at a compound annual growth rate (CAGR) of 8.12%. The global structural conductive polymer market reached an estimated USD 603.36 Million in 2025 and, under our central scenario, is projected to surpass USD 1.04 Billion by 2032. This briefing highlights the report’s strategic value for executives preparing decisions in 2026 while deliberately preserving the detailed segment tables and proprietary outputs that are available in the full report.
Worldwide Structural Conductive Polymer Market
Why this report matters for 2026 decisions
-
Timing and scale: With an 8.12% CAGR over the forecast horizon, structural conductive polymers are moving from niche specialty materials toward broader structural and functional integration across automotive, electronics, medical, and defense value chains. 2026 is a pivotal planning year for manufacturers and investors: technology selection, capital investment, and supplier commitments made in 2026 will determine competitiveness through the rest of the decade.
Worldwide Structural Conductive Polymer Market -
Cross‑domain relevance: These materials serve simultaneous requirements—mechanical strength, electrical functionality (EMI management, conductivity), and weight reduction—making them integral to electrification, miniaturization, and sensorization trends. Decisions in 2026 must therefore balance materials engineering with system‑level tradeoffs.
Worldwide Structural Conductive Polymer Market -
Market structure and consolidation signals: The market presents moderate concentration: our analysis shows a top‑three concentration that leaves room for differentiated suppliers and a top‑five composition that reflects both established chemical majors and highly specialized compounders. This structure creates opportunities for targeted partnerships and M&A to secure scale or unique capabilities.
What the report delivers (practical assets for immediate use)
-
Proprietary market model: a dynamic revenue and volume model (2020–2032) with scenario toggles for adoption curves, raw material price shocks, and application substitution—built so finance teams can plug in internal assumptions and generate bespoke forecasts.
-
Go‑to‑market playbooks: differentiated routes for compounders, OEMs, and tier suppliers including pricing strategies, qualification roadmaps, and sample‑to‑production timelines for high‑confidence applications (e.g., EMI shielding, structural battery housings, bio‑compatible sensors).
-
Supply‑chain and raw‑material playbook: supplier maps, risk heatmaps, and hedging levers for monomers (aniline, pyrrole, EDOT, thiophene) and key dopants. The package includes sensitivity analyses showing margin erosion points tied to raw‑material cost movements and lead‑time disruption scenarios.
-
Regulatory and safety matrix: practical compliance checklists for working with toxic or flammable monomers, recommended worker‑protection investments, and environmental controls that reduce certification risk and accelerate customer acceptance.
-
Technology and IP landscape: vendor capability profiles, materials readiness levels, and licensing/partnering templates to accelerate integration of PEDOT:PSS, carbon‑nanotube, and conductive‑filler systems into structural formulations.
-
M&A and partnership scorecards: a screening framework with valuation multipliers for revenue growth, margin expansion potential, and strategic fit—designed to reduce diligence cycles in competitive processes.
Key strategic insights for 2026
1) Demand inflection points are application‑specific. Electrification (battery housings and conductive structural components) and high‑performance consumer and industrial electronics continue to be primary drivers, with medical sensors and defense systems providing premium, low‑volume opportunities. The upshot for 2026 planning: prioritize development and qualification resources on two parallel tracks—high‑volume, cost‑sensitive grades and low‑volume, high‑value specialty grades that command higher margins.
2) Raw‑material dynamics will shape near‑term economics. Conductive polymers rely on a constrained set of monomers and dopants; production costs are sensitive to both feedstock prices and the availability of specialized dopants such as ammonium persulfate and ferric chloride. Notably, certain aniline market cycles have recently eased—we observed a downward movement in Chinese aniline prices into late 2024—however, volatility remains. Procurement strategies including longer‑term offtakes, geographic diversity, and selective vertical integration will materially affect cost competitiveness in 2026.
3) Regulatory and occupational safety requirements are non‑negotiable. Several commonly used monomers carry toxicity and flammability risks that trigger stringent controls. Firms that invest early in compliant production lines and transparent safety data packages will accelerate customer qualification and reduce time‑to‑market, particularly for medical and aerospace contracts.
4) Differentiation through formulation and processing is decisive. Competitive advantage is increasingly derived from the ability to maintain mechanical integrity while delivering consistent electrical performance through processing and across temperature and humidity ranges. Companies capable of supplying off‑the‑shelf masterbatches as well as bespoke engineered compounds will capture broader wallet share across OEMs and tier suppliers.
Competitive landscape: positioning and tactical moves
The market is populated by global chemical majors, specialist compounders, and materials innovators. Established players bring scale and channel access; specialists provide formulation depth and rapid customization. Key archetypes we profile include:
-
Integrated chemical majors that offer conductive polymer grades as part of broader resin portfolios, focusing on automotive electrification and energy storage components.
-
Engineering compounders that excel at custom conductive formulations and rapid qualification cycles for electronics and EMI shielding.
-
Specialty materials innovators advancing high‑purity conductive systems (e.g., PEDOT:PSS) and enabling sensor and biomedical applications.
Recent strategic moves underscore these archetypes: a European specialist expanded U.S. production capacity in 2025 to shorten lead times and support North American demand growth; a global resin producer launched a new series of conductive polycarbonate grades targeting battery system integration in 2024; and a compounder introduced carbon‑nanotube‑reinforced conductive plastics for advanced EMI shielding in 2023. These actions signal that both capacity buildouts and differentiated product introductions are active levers for market share gains.
Recommended actions for corporate leaders in 2026
-
For chemical and compound manufacturers: prioritize a two‑track investment model—scale production for cost‑sensitive grades while funding pilot lines for high‑value specialty formulations. Use our scenario model to size break‑even points under raw‑material stress tests.
-
For OEMs and tier suppliers: deploy a materials qualification portfolio that shortlists dual‑source suppliers across the function/mechanical matrix and require supplier transparency on raw‑material sourcing and safety controls.
-
For investors and M&A teams: apply the PW Consulting scorecard to prioritize targets that combine proprietary formulations with near‑term revenue traction in electrification or medical sensing; value candidates not only on current sales but on qualification pipelines and IP defensibility.
-
For procurement and operations: implement hedging and supplier diversification strategies for monomers and dopants, and accelerate transition plans that reduce dependency on single‑source feedstocks.
-
For R&D leaders: focus on formulation robustness (moisture/thermal stability), processing tolerance, and scalable compounding routes—these attributes are decisive in converting engineering samples into production parts.
How PW Consulting’s report reduces execution risk in 2026
Our deliverables are built to shorten decision cycles. The market model can be recalibrated with internal assumptions to produce tailored investment cases in hours instead of weeks. The supplier and raw‑material playbooks translate to practical procurement actions (term sheet language, KPI sets, and qualification milestones). The regulatory matrix reduces certification time by clearly identifying the control points that most frequently delay acceptance in medical and aerospace programs. Collectively, these tools reduce technical, commercial, and regulatory uncertainty at the critical moment when 2026 budgets and capital plans are being finalized.
Invitation to explore the full intelligence set
This briefing is intended as a concise strategic orientation. The full PW Consulting report contains the granular segmentation tables, proprietary demand‑by‑end‑use and by‑type models, supplier scorecards, and executable playbooks that corporate teams and investors need to execute with confidence. To access the detailed datasets, scenario workbooks, and workshop‑ready materials, please visit the PW Consulting report page or contact our industry analysts. For clients who commission bespoke engagements, we offer accelerated due diligence and a 48‑hour decision kit that maps our findings directly to your business case.
Prepared by PW Consulting’s Advanced Materials Practice — our team combines market economists, polymer scientists, and senior M&A advisors to help organizations convert materials strategy into profitable products and defensible market positions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Structural Conductive Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Bird Detection System for Airports Market Set to Expand at 8.01% CAGR from 2026 to 2032
By pmarketresearch, 2026-07-17
Worldwide Bird Detection System for Airports Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on Worldwide Bird Detection Systems for Airports delivers an executive-grade intelligence package designed to inform capital allocation, product strategy, and partnership decisions for 2026 and beyond. This preview surfaces the study’s strategic implications, synthesizes market momentum, and profiles the competitive landscape — while intentionally reserving the report’s granular segment-level metrics and procurement benchmarks for subscribers and licensed clients.
Worldwide Bird Detection System for Airports Market
Why this market matters to aviation decision‑makers in 2026
Bird strikes remain a persistent operational and financial risk for airports and airlines. Regulatory and operational forces are converging to make advanced detection a prioritized capital investment across commercial, military, and training-airfield portfolios. Our modeled market trajectory shows a sustained expansion from the 2020 baseline through the forecast window (2026–2032), driven by recurring investment cycles, retrofits at legacy airfields, and deployment of new solutions as part of broader smart‑airport programs. PW Consulting’s top-line projection incorporates historical data, technology adoption curves, and regulatory headwinds to produce a forward view grounded in measurable trends: the market rebounds strongly into the mid-2020s and continues on an upward course through the early 2030s, reflecting a compounded annual growth trend that decision-makers should treat as the baseline planning assumption for next‑stage strategy.
Worldwide Bird Detection System for Airports Market
Macro dynamics shaping vendor and buyer behavior
-
Regulatory pressure and standards: Aviation authorities worldwide, including the FAA, increasingly embed advanced detection requirements into Wildlife Hazard Management Plans and best‑practice guidance. Compliance timelines and audit expectations are creating a near‑term procurement pipeline for airports seeking to demonstrate modernized mitigation capabilities.
Worldwide Bird Detection System for Airports Market -
Operational focus on low‑altitude exposure: More than four out of five bird strikes worldwide occur in runway and approach/departure corridors below 800 feet. That operational reality is accelerating demand for sensors and analytics optimized for low‑altitude and ground‑level coverage — not only perimeter radars but also ground‑level thermal and acoustic solutions tailored to runway incursion windows.
-
Economic drivers: Bird strikes impose recurring direct and indirect costs in the aviation ecosystem, prompting risk managers and procurement teams to justify technology investments through measurable reductions in strike incidence and improved operational availability. This dynamic favors vendors who can present verifiable ROI cases and post‑installation performance monitoring.
-
Technology convergence: The fastest-moving procurements are for multi‑sensor solutions that fuse radar, electro‑optical/infrared imaging, acoustic sensing, and AI classification. Buyers are prioritizing systems that can deliver both tactical alerts (real‑time tower notification and patrol guidance) and strategic outputs (ecological trend analysis and seasonal forecasting).
What the market movement means for 2026 corporate strategy
-
Procurement leaders should treat 2026 as a window to convert pilots into scaled deployments. With regulatory expectations rising and a maturing vendor field, procurement strategies must move beyond single‑sensor pilots toward procurement frameworks that include integration, services, and lifecycle performance guarantees.
-
Product and R&D leaders need to prioritize sensor fusion, AI classification accuracy, and systems that reduce false alarms while preserving detection sensitivity at low altitudes. Investing in software platforms that offer remote configuration, predictive activity models, and API connectivity to airport operational systems will be a competitive differentiator.
-
Service and business model innovation is central. As airports seek predictable operational outcomes, vendors that offer outcome‑based contracts, managed detection-as-a-service, or hybrid capital‑plus‑subscription models will expand market access, particularly with regional airports and training facilities where capital budgets are constrained.
-
M&A and partnership opportunities are concentrated around two plays: acquired capabilities that accelerate multi‑sensor fusion and go‑to‑market partnerships that extend distribution into complex airport procurement processes and integrator ecosystems.
Competitive landscape — who’s shaping the field
The vendor field combines specialist radar makers, imaging/thermal system developers, integrators, and software-first entrants. Several established players set the performance and deployment benchmarks industrywide; PW Consulting’s assessment highlights their strategic positioning rather than absolute market shares.
-
DeTect, Inc. (Panama City, Florida) — A long-standing specialist in avian radar with a large installed base and products designed for True3D coverage and high update rates. DeTect’s emphasis on all‑weather performance and tower integration makes it a go‑to for airfields prioritizing persistent situational awareness. Recent deployments continue to validate demand in training and commercial contexts.
-
Robin Radar Systems B.V. (Netherlands) — Known for 3D avian radar products with fast scan speeds and classification capabilities. Robin’s technology is notable for deployments at major international hubs and for its emphasis on size and velocity discrimination, helping customers reduce nuisance alerts while preserving safety margins.
-
Accipiter Radar (Canada / USA) — Delivers software‑definable radar platforms and networked intelligence frameworks that enable multi‑sensor scalability. Their approach appeals to customers seeking expandable systems that can integrate future sensor types and distributed processing.
-
Volacom (Bulgaria) — Focused on thermal imaging and automated detection systems for ground‑level bird and wildlife management, offering continuous all‑weather detection and deterrence automation important for runway safety zones.
-
Xsight Systems (Israel) — Positions a fused millimeter‑wave radar and electro‑optical suite for runway threat detection, emphasizing automatic recognition and integrated auditory deterrence for rapid response at the ground level.
-
NEC Corporation (Japan) — Integrates S‑band radar with high‑sensitivity cameras and enterprise processing for airports pursuing broader smart‑airport architectures. NEC’s strength lies in systems engineering and integration with airport operational platforms.
-
AscendXYZ (Europe) — Provides mobile, end‑to‑end avian radar services with trailer‑mounted systems and real‑time risk modeling for coverage of large areas. This service model is attractive to airports requiring flexible or seasonal capacity without permanent infrastructure investment.
Each vendor brings a differentiated mix of hardware capability, data processing, and service model. Tactical procurement choices increasingly hinge on system openness, integration APIs, and the vendor’s ability to deliver demonstrable reductions in strike risk — not just technical specifications.
Practical deliverables in PW Consulting’s full report
The full study is constructed to be directly actionable for 2026 planning cycles. Key practical deliverables include:
-
Transparent market sizing and forecast methodology calibrated to market signals, procurement cycles, and regulatory timelines — providing a defensible financial baseline for capital planning.
-
Scenario analysis and sensitivity testing for alternative adoption rates, pricing trajectories, and regulatory tightening to stress-test investment cases.
-
Vendor scorecards and capability matrices that evaluate performance across detection range, low‑altitude sensitivity, classification accuracy, integration capabilities, and lifecycle support. (Note: detailed scorecard data and segment-level splits are available only in the full report to preserve competitive confidentiality.)
-
Procurement playbooks and contract language templates for fixed, mobile, and managed‑service deployments — including verification protocols for post‑installation performance guarantees.
-
Operational case studies documenting before/after metrics for strike incidence and patrol responsiveness, plus a checklist for tower integration and airfield operations alignment.
-
Integration and data architecture guidance for fusing sensor feeds into airport operational databases, C2 systems, and ecological monitoring platforms.
Rapid intelligence: a tactical checklist for 2026 procurement
-
Require proof points: insist on site‑specific performance verification and a minimum observation period before final acceptance.
-
Prioritize fusion: evaluate vendors on their ability to fuse radar with EO/IR and acoustic data, and to reduce false positives while preserving detection coverage below 800 ft.
-
Account for services: include maintenance, software updates, and data‑analytic subscriptions in total cost of ownership models rather than comparing hardware sticker prices alone.
-
Plan for scale: choose architectures that allow incremental sensor addition and networked multi‑site deployments to support regional airport groups or military bases.
Concluding strategic recommendations
Entering 2026, airport operators, integrators, and technology investors face an inflection point. Regulatory expectations, concentrated low‑altitude strike exposure, and a maturing vendor ecosystem create a window where timely investments can materially reduce operational risk and deliver sustainable value. PW Consulting’s study quantifies the market’s expansion through the forecast horizon and prescribes tactical steps to convert strategic intent into measurable operational outcomes.
For procurement officers and C‑level strategists, the imperative is clear: move beyond pilot projects to procurement structures that embed performance metrics, integration pathways, and service continuity. For vendors and investors, the opportunity is to differentiate through verifiable outcomes, open architectures, and business models that lower the barrier to adoption.
This preview highlights core directional insights; the full PW Consulting report contains the granular regional and technology splits, supplier scorecards, pricing benchmarks, and deployment case studies required to execute on the 2026 agenda. Access to the complete dataset and actionable annexes is available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Bird Detection System for Airports Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Chromium Salt Market Set for 3.15% CAGR Through 2026–2032, Says New Report
By pmarketresearch, 2026-07-17
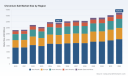
Worldwide Chromium Salt Market — Strategic Outlook and Actionable Insights for 2026
Executive synopsis
PW Consulting’s latest Worldwide Chromium Salt Market report delivers a disciplined, decision-focused view of a market transitioning from volume-driven cycles to value- and compliance-driven dynamics. The industry returned from cyclical troughs in the early 2020s and, after recovering to roughly USD 3.42 billion in our 2025 base year, is projected to expand to the mid-single‑digit billions by the end of the 2026–2032 forecast window — reaching approximately USD 4.25 billion by 2032 at a compound annual growth rate of 3.15% (2026–2032). For executives making capital allocation, sourcing, and regulatory-compliance choices in 2026, the report translates these macro trajectories into pragmatic, stage‑gated actions that reduce downside and capture premium upside.
Worldwide Chromium Salt Market
Why this report matters for 2026 decision-makers
- Timing: 2026 will be a hinge year — market momentum is modest but structural drivers (regulatory tightening, feedstock concentration, and targeted capacity additions) create distinct windows for premium capture or margin compression depending on strategy.
- Actionability: The report converts market forecasts into playbooks for procurement, manufacturing footprint, product-mix optimization, and M&A screening — not just high-level charts but executable next steps and decision templates.
- Risk-to-reward clarity: We quantify scenarios where price movements, regulatory restrictions, or regional supply interruptions materially affect margin pools across the value chain — enabling CFOs and business unit leaders to stress-test 2026 budgets.
Market dynamics: what is changing and why it matters
Three structural vectors define the near-term strategic landscape.
Worldwide Chromium Salt Market
- Regulatory acceleration: European and international authorities have intensified scrutiny of hexavalent chromium. Notably, ECHA concluded in 2025 that certain Cr(VI) substances warrant EU-wide restrictions, and the European Commission’s December 2025 guidance accelerated timelines toward a horizontal restriction that could enter into force between late‑2027 and early‑2028. That regulatory pathway compresses time for compliance investments and creates an early-mover premium for low‑Cr(VI) alternatives and certified supply chains.
- Feedstock concentration and price pressure: Global chromite ore production recovered in 2025 (an estimated ~3% increase year-on-year), with South Africa remaining the dominant producer. Tighter concentrate availability and upward pressure on ore benchmarks in early 2026 — with quoted South African concentrate trading at roughly $315/ton CIF in reported market checks — mean upstream volatility will continue to transmit to producers and buyers. Hedging, diversified procurement, and vertical integration become strategic levers.
- Capacity dynamics and regional moves: Targeted capacity additions and strategic expansions are being executed by incumbents and new entrants. These moves are selective and frequently accompanied by pricing actions or integration plays that reshape regional competitive intensity. The net effect is a market that is not simply growing but being re‑shaped in terms of where value and compliance capability sit.
Competitive landscape — what to watch
The chromium salts sector remains moderately concentrated: the largest three producers account for roughly half of global capacity, while the top five push the concentration higher. This concentration creates both oligopolistic pricing power in certain product streams and competitive opportunity in niche, high‑purity, or compliant segments.
Worldwide Chromium Salt Market
- Lanxess AG (Germany) — A global integrator with a diversified portfolio in chrome chemicals, Lanxess remains a strategic bellwether for Western‑market product availability and compliance trajectories. Its European footprint and technical capability make it a critical partner for companies seeking certified low‑Cr(VI) solutions.
- Vishnu Chemicals Limited (India) — An example of capacity-led growth in emerging market supply. The company’s recent program to increase sodium dichromate capacity is a reminder that cost-competitive manufacturing bases in Asia will continue to be price anchors for bulk product lines, even as higher‑value, compliance‑oriented demand shifts elsewhere.
- Hubei Zhenhua Chemical (China) — Active on both price and acquisition fronts, recent moves include substantial price adjustments for metal chromium and strategic acquisitions that expand salt capacity. Such integrated playbooks show how Chinese producers are consolidating supply chains to capture margins across feedstock-to-product flows.
- New and regional entrants — From planned new metal chromium plants in the United States to additional lines in Turkey and Kazakhstan, smaller incumbents and greenfield projects are reshaping regional access. North American on‑shoring initiatives, in particular, will have outsized strategic impact on specialty and high‑purity segments.
- Specialty and laboratory suppliers — Companies focused on high‑purity salts and analytical reagents remain differentiated from bulk producers, commanding margin premiums and acting as suppliers to electronics, research, and specialty manufacturing sectors.
Recent strategic moves and tactical implications
- Increased metal chromium prices and phased price rises by some producers underscore the susceptibility of midstream and downstream margins to upstream swings. Buyers should plan for tiered procurement strategies that combine short-term contracts with selective forward coverage.
- Capacity additions and acquisitions among major producers create localized oversupply risk in select product streams while tightening supply elsewhere — a divergence that favors firms that can dynamically adjust product mix and route to market.
- Regulatory timelines compress capital expenditure cycles: companies that defer compliance investments risk both market exclusion in key regions and higher retrofitting costs. Early compliance and certified supply chain programs open premium channels, especially with large industrial buyers and OEMs that have strong ESG requirements.
What the PW Consulting report contains (practical, implementable modules)
Designed for C-suite and functional leaders, the report moves beyond descriptive analysis to provide tools you can use in 2026:
- Market sizing and forward scenarios calibrated to 2026 planning cycles — including a base, accelerated‑regulation, and feedstock‑shock scenario set that maps to profit-and-loss and cash‑flow sensitivity templates.
- Supply‑chain heat maps that identify single‑point failures at the mine, converter and salt‑processing stages, with mitigation playbooks (dual-sourcing templates, inventory policy triggers, and near‑shoring decision trees).
- Regulatory readiness roadmaps tailored to EU, North American and key Asian jurisdictions — detailing timelines, investment ranges, testing protocols, and supplier certification checklists without prescriptive legal advice but with operationally focused action steps.
- Commercial playbooks for producers and buyers: pricing models, contract clause templates for pass‑throughs and force majeure, and channel segmentation strategies that segregate bulk from specialty flows.
- M&A and capital allocation screening: target archetypes, due‑diligence scorecards emphasizing feedstock security and environmental liabilities, and integration checklists to preserve margins post‑acquisition.
- Company briefs and plant‑level intelligence on leading players and notable greenfield/expansion projects, coupled with a ranked list of supply partners for different risk profiles. (Note: granular, downloadable tables and line‑item breakdowns are reserved for the full dataset.)
Strategic recommendations for executive teams in 2026
- Producers: Prioritize compliance-enabled product differentiation. Invest selectively in emissions and effluent controls to unlock access to regulated markets and secure long‑term offtake arrangements with OEMs and industrial users who will penalize non‑compliant suppliers.
- Buyers (large consumers, OEMs): Re‑architect contracts to combine shorter rolling volumes with strategic long‑term lots from certified suppliers. Implement a two‑tier procurement model that protects against upstream shocks while optimizing price for stable bulk needs.
- Investors and financial sponsors: Seek assets with defensible feedstock access or clear pathways to regulatory compliance. Distinguish between scale plays in bulk commodity salts and margin-rich specialty niches where consolidation and technical expertise drive value.
- Risk and sustainability officers: Accelerate chromium‑specific supplier audits and map potential liabilities from legacy operations. A proactive remediation and certification program will become a table stake in tendering processes by late 2027.
How PW Consulting’s forecast informs near-term capital and commercial choices
The market’s projected CAGR of 3.15% over the 2026–2032 forecast period signals modest top‑line expansion but significant structural churn beneath the aggregate numbers. In practice, that means the best returns in 2026 will come from reallocating capital to compliance-enabled capacity, securing feedstock with flexible contractual terms, and executing targeted commercial moves rather than broad-based capacity builds. Companies that treat the 2026 planning cycle as a strategic reset — optimizing for regulatory resilience and supply security — will outperform peers even in a low‑growth, moderately concentrated market.
Next steps and where to find the detailed intelligence
This release is a strategic précis intended to highlight the report’s decision‑centric value. The full PW Consulting Worldwide Chromium Salt Market report includes the complete dataset, company profiles, scenario spreadsheets, regulatory timelines, and downloadable procurement templates that operational teams can implement immediately. To access the detailed segment tables, plant‑level capacities, and the proprietary risk scores used in our M&A screening, please visit the PW Consulting report page linked in our distribution materials.
Closing observation
2026 will reward clarity of strategy more than scale of ambition. With regulatory timetables accelerating and feedstock dynamics tightening, the companies that combine disciplined compliance investments, adaptive procurement, and targeted commercial plays will convert a moderate market expansion into outsized strategic advantage. PW Consulting’s report is designed to make those choices measurable, repeatable, and actionable.
For detailed analysis of this topic, please visit the official page: Worldwide Chromium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cellulose Thickener Market Reaches USD 5,820 Million in 2025, Poised to Hit USD 8,511 Million by 2032 at a 5.58% CAGR
By pmarketresearch, 2026-07-17
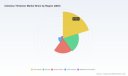
Worldwide Cellulose Thickener Market 2026: Strategic Imperatives from PW Consulting
PW Consulting today publishes an executive preview of our new Worldwide Cellulose Thickener Market report, designed to inform C-suite and investment decisions as companies prepare for 2026. The cellulose ether thickeners market has moved from an estimated USD 4,450.5 million in 2020 to approximately USD 5,820.0 million in 2025, and our proprietary model forecasts continued expansion into the next decade—reaching an estimated USD 8,511.3 million by 2032 under a central-case compound annual growth rate (CAGR) of 5.58% for the forecast window. This release synthesizes the strategic implications of that trajectory while deliberately reserving the report’s full segmentation detail for subscribers and report purchasers.
Worldwide Cellulose Thickener Market
Why this matters for 2026 planning
-
Timing and resource allocation: With sustained mid-single-digit CAGR through the forecast window, companies that align capex, R&D, and procurement cycles to 2026 market dynamics will protect margin and capture share as customer formulations evolve.
Worldwide Cellulose Thickener Market -
Regulatory and trade inflection points: 2024–2025 saw material regulatory and trade changes that reshape sourcing, compliance, and near-term product eligibility—making early compliance and supply diversification a high-return activity for 2026.
Worldwide Cellulose Thickener Market -
Consolidation pressure: Market concentration metrics in our study indicate a market structure where a handful of large players maintain meaningful aggregate share, yet significant opportunities remain for niche and regional specialists.
Macro dynamics shaping the market
From a top-line perspective, demand drivers remain diversified across industrial and consumer-facing end markets—construction, paints and coatings, food and beverage, pharmaceuticals and personal care, and energy-sector uses such as drilling. The combination of continued infrastructure activity in several regions and product reformulation trends in food and personal care underpins the baseline growth we model.
However, a complex overlay of supply-side shocks and regulation has re-weighted near-term risk:
-
Raw material cost volatility: Key upstream inputs—pulp and caustic soda—experienced notable price appreciation in recent quarters, tightening margins for commoditized grades and favoring vertically integrated or long-contracted producers.
-
Regulatory tightening: Updates to chemical safety frameworks and food/contact monographs have narrowed compliance windows for certain impurity profiles and compositional tolerances. Companies that preemptively validate manufacturing and documentation will avoid time-to-market slippage in 2026.
-
Trade friction and tariffs: Recent tariff adjustments on imports from certain regions have materially changed landed cost calculus for some buyers, accelerating local sourcing and regional production expansion discussions.
Competitive landscape — what incumbents are doing
The industry is characterized by a mix of global majors and specialized regional producers. Major players continue to pursue a multi-pronged strategy of product differentiation, capacity optimization, and regulatory positioning:
-
Dow: Continuing to leverage its Methocel™ franchise, Dow has introduced lower-VOC cellulose ether grades targeted at waterborne coatings—an example of how product innovation is now closely linked to sustainability and regulatory narratives.
-
Ashland: Capacity expansions for key HEC lines underscore a strategy to secure supply for formulation-driven customers in personal care and building chemicals, where service reliability is a competitive moat.
-
Shin‑Etsu Chemical and other established Asian producers: Certification and market-eligibility moves—such as food-grade and religious certification—are being used to unlock higher-margin channels and broaden geographical footprints.
-
Specialty and regional suppliers: European and smaller global players are leaning into application expertise for paints, tile adhesives, and specialty personal care formulations, offering formulation advisory and co-development as differentiation.
Our company profiles and competitor playbooks examine product portfolios, margin drivers, capacity maps, and recent transactions. We track notable recent events—new low-VOC product rollouts, targeted capacity investments, and certification updates—to show how these firms are positioning for 2026.
Operational themes and tactical implications for 2026
-
Procurement: Adopt layered sourcing strategies combining long-term contracts for pulp/caustic feedstocks with spot-market overlays. Hedging and strategic inventory build before expected seasonal cost peaks can be accretive to gross margin.
-
Product development: Prioritize low-impurity grades and formulations that address evolving regulatory thresholds and low-VOC preferences. Fast-track applications that can command premium pricing in food and pharma channels where compliance burdens create entry barriers.
-
Manufacturing footprint: Consider modular capacity expansions and toll-manufacturing partnerships in tariff-affected regions. For many buyers and suppliers, nearshoring offers an insurance policy against trade disruption.
-
M&A and alliances: Bolt-on acquisitions remain an efficient route to gain formulation expertise and localized customer access; joint ventures can be the fastest path to mitigate tariff exposure without full greenfield outlay.
-
Commercial strategy: Value-selling around regulatory compliance, supply reliability, and formulation support will be differentiated versus competing purely on price.
What PW Consulting’s full report delivers
The published report is constructed as a hands-on playbook for executives entering 2026 planning cycles. Highlights include:
-
Proprietary market-sizing and forecasting model spanning 2020–2032 with scenario-based outputs and sensitivity analysis tied to raw material and trade-policy scenarios.
-
Segment and application-level demand drivers, with growth outlooks and risk stratification to prioritize GTM efforts (note: fine-grained segment allocations and values are reserved for the full report).
-
Supply-side intelligence: plant-by-plant capacity mapping, utilization benchmarks, and a capacity pipeline tracker capturing announced expansions and likely commissioning timelines.
-
Regulatory and trade impact assessment, including practical compliance checklists and accelerated certification roadmaps for food, pharma, and cosmetics customers.
-
Commercial playbooks for procurement, pricing, and product launch—complete with negotiation levers, contract templates, and case studies from recent transactions.
-
Vendor and customer segmentation frameworks to help sales and R&D prioritize accounts and formulate channel strategies.
-
Strategic M&A scouting lists and valuation benchmarks for target identification, alongside integration risk matrices to guide post-merger value capture.
Strategic recommendations — a 90‑day action plan for 2026 readiness
-
Conduct an immediate supply‑chain stress test: map single‑source exposures, tariff vulnerabilities, and raw-material contract expiries that occur in 2026.
-
Fast-track regulatory audits for product families likely to face tightened impurity or composition limits; allocate a small cross-functional team to pursue certifications where required.
-
Prioritize one or two premium applications (e.g., food-grade or low-VOC architectural coatings) for which you can develop a differentiated product and pricing strategy within 12 months.
-
Evaluate opportunistic M&A or toll-manufacturing partnerships in tariff-impacted geographies to preserve cost competitiveness without overcommitting capital.
-
Design a customer-facing sustainability narrative tied to measurable product attributes (VOC, biodegradability, supply-chain transparency) to capture the growing willingness-to-pay in several end markets.
On market transparency and next steps
PW Consulting’s preview intentionally omits the granular regional and application-specific dollar splits found in the full study. This “trailer” approach is designed to demonstrate analytical depth while directing teams to the complete dataset and tools required to operationalize 2026 strategies—our interactive model, downloadable playbooks, and proprietary scenario matrices.
To receive the complete report, access the interactive forecast model, or schedule a briefing with PW Consulting’s cellulose ether practice, visit our report page. For clients preparing board-level briefings or investment memoranda for 2026, PW’s analysts are available to deliver tailored slide decks and one‑on‑one strategy sessions.
About PW Consulting: PW Consulting is a strategy advisory firm specializing in industrial chemicals and specialty materials. Our market intelligence combines bottom-up supply mapping, primary interviews across value chains, and scenario-based financial modeling to provide actionable guidance for executives and investors.
For detailed analysis of this topic, please visit the official page: Worldwide Cellulose Thickener Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Homosalate Market to Grow from USD 124.5 Million in 2025 to USD 173.09 Million by 2032 at a 4.82% CAGR — Cosmetic Grade and Sunscreen Products Lead, North America Dominates; Top‑3 Firms Hold 48.65%
By pmarketresearch, 2026-07-17
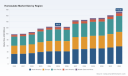
Worldwide Homosalate Market — Strategic Briefing for 2026 Decision Makers
Executive snapshot
PW Consulting’s new market study on Homosalate—anchored on a 2025 base year with a historical review covering 2020–2025 and a forecast window through 2032—translates complex supply, regulatory and demand dynamics into a compact set of strategic levers for 2026 corporate planning. The market exhibits an overall mid-single-digit compound annual growth rate (CAGR) of 4.82% across the forecast period. After a modest near-term plateau around the 2025–2026 inflection, our projections show a clear recovery and expansion toward the end of the decade, underscoring an important planning horizon for procurement, R&D and M&A activity.
Worldwide Homosalate Market
Why this matters to corporate leaders in 2026
- Regulatory uncertainty is now a core supply‑chain risk. Regulatory reviews and public scrutiny can abruptly change permitted uses and labeling requirements—altering formulation strategies and inventory valuation within quarters.
- Supplier concentration and strategic positioning among incumbent producers mean access to reliable volumes and technical support will be a differentiator in new product launches and time‑to‑market.
- End‑market demand is resilient but nuanced: sunscreen and daily care remain the largest consumption vectors, while adjacent applications (color cosmetics, hair care and industrial uses) create diversification opportunities for manufacturers and contract formulators.
- Ahead of 2026 budgeting cycles, companies that convert macro forecasts into procurement hedges, formulation roadmaps and regulatory scenario plans will preserve margin and protect revenue streams.
Market trajectory — what the headline numbers tell us
Using 2025 as the analytical base, PW Consulting models a short-term cooling into 2026 followed by a steady expansion through 2032. This shape is driven by three interacting forces: near-term regulatory reassessments that temper purchasing, a rebound in end‑consumer demand linked to SPF and daily‑use personal care, and price normalization as suppliers adapt capacity and contractual terms. The 4.82% CAGR in the forecast period reflects this combination of temporary headwinds and structurally positive demand for UV protection chemistries.
Worldwide Homosalate Market
Drivers, constraints and structural shifts
- Demand drivers: rising awareness of daily UV protection, premiumization of sun‑care formulations, and expanded use in multifunctional personal care products continue to underpin demand.
- Regulatory and environmental constraints: ongoing evaluations under major chemical regulations, continued scrutiny in ecologically sensitive zones, and unresolved safety assessments in some jurisdictions introduce timing and product‑use risk.
- Supply-side dynamics: the supplier base is moderately consolidated, with a few global players controlling a significant share of commercial supply and technical know‑how. This creates both bottlenecks and strategic partnership opportunities for firms that lock in long‑term supply and co‑development agreements.
- Innovation pressure: formulators face technical tradeoffs between photostability, sensory properties and regulatory-compliant profiles. The relative scarcity of drop-in, unrestricted substitutes for Homosalate in certain functional roles elevates the value of formulation IP.
Competitive landscape — how the incumbents are positioned
Global supply is anchored by four principal suppliers with distinctive strategic postures:
Worldwide Homosalate Market
- Symrise AG (Holzminden, Germany) — a market leader with established branded ingredient positioning and strong customer technical service capabilities. Its Neo Heliopan branded chemistry is positioned as a reliable, widely recognized UVB filter for sun protection formulations.
- BASF SE (Ludwigshafen, Germany) — a diversified chemical conglomerate that supplies Homosalate through its care-chemicals channels, leveraging wide distribution networks and integration into larger formulation portfolios.
- dsm‑firmenich AG (Kaiseraugst, Switzerland) — following the DSM and Firmenich consolidation, the combined entity has reinforced its supply chain and expanded offerings in specialty UV filters, enhancing its ability to provide formulation support at scale.
- Hallstar (Chicago, IL, USA) — a specialist supplier that focuses on salicylate‑based UV filter chemistry and positions itself as a responsive partner for niche and mid‑scale contract formulators.
Our competitive analysis maps each supplier across technical support, geographic reach, cost competitiveness and exposure to regulatory risk. The recent industry consolidation events (notably the completion of the DSM–Firmenich merger) increase the strategic importance of supplier selection: large suppliers are better able to absorb compliance costs and support global launches, but they also concentrate supply risk for buyers. Market concentration metrics in the report quantify this balance and show it to be material for procurement strategy.
What the PW Consulting report gives you — practical, executable content
This study was designed as a hands‑on operational toolkit for decision makers. Highlights include:
- Scenario‑based forecasts that translate regulatory outcomes into volume and price trajectories so procurement and finance teams can stress‑test budgets.
- Supplier scorecards and a short‑list playbook to evaluate vendors across continuity risk, technical co‑development capability, pricing flexibility and geographic coverage.
- Regulatory heatmaps and a rolling monitoring framework that prioritize markets and timeframes where compliance action is most likely to affect commercial availability.
- Formulation compatibility matrices and substitution risk assessments for product development teams seeking alternative architectures or multi‑filter strategies.
- Price sensitivity models and contract negotiation templates that quantify the benefits of fixed‑term supply, indexation clauses and dual‑sourcing approaches.
- Opportunity maps for downstream manufacturers and private labels that identify white‑space applications, premiumization pockets and routes to capture higher margin through value‑added formulations and claims.
Strategic recommendations for 2026 planning cycles
- Adopt a tiered supplier strategy: combine long‑term agreements with one or two established global suppliers and agile spot arrangements with regional specialists to balance security and cost.
- Make regulatory scenario planning a board‑level priority: build three operational playbooks covering (a) status quo, (b) tightened restrictions in major markets, and (c) rapid phase‑outs in sensitive jurisdictions.
- Accelerate formulation diversification: invest in R&D for multi‑filter architectures and sensory optimization that allow graceful substitution without compromising product positioning.
- Use commercial levers to trade price vs. service: early commitment and volume guarantees can reduce unit cost and secure technical service; short‑duration flex contracts preserve agility.
- Prioritize traceability and EHS credentials: eco‑profiling and reef‑safety communications are increasingly material to consumer purchasing and regulatory scrutiny in tourism‑sensitive geographies.
- Scan M&A and partnership targets: consider specialty chemical players and regional toll‑manufacturers that can expand capacity or provide differentiated supply into prioritized markets.
- Embed market concentration monitoring into procurement KPIs: set threshold triggers tied to supplier market share and supply‑risk indicators to prompt strategic sourcing reviews.
Regulatory and environmental “noise”: what to watch now
Three issues generate most of the market’s asymmetric risk and should be monitored continuously:
- Regulatory re‑evaluations under major frameworks that examine endocrine disruption potential—outcomes can alter permitted uses, labeling and testing requirements in key jurisdictions.
- Unresolved determinations in some regulatory agencies which have, to date, stopped short of full approval pending additional safety data—these keep formulation risk elevated.
- Environmental scrutiny in marine‑protected and tourism‑sensitive regions: while not uniformly banned like certain other UV filters in specific states, Homosalate is subject to local restrictions and growing consumer interest in “reef‑friendly” claims.
How to use this briefing with your stakeholders
Senior leaders should use the report as the foundation for three focused 2026 initiatives:
- Procurement risk mitigation sprint (3–6 months): quantify exposure, secure conditional commitments, and implement fallback supply routes.
- Product resilience program (6–12 months): adapt existing SKUs to multi‑filter or alternative chemistries where feasible and prioritize launch pipelines that are robust to regulatory stress.
- Investor and M&A diligence playbook (ongoing): incorporate the report’s supplier scorecards and market concentration analytics into target screening and valuation adjustments.
Next steps — access and engagement
This article highlights the strategic frames and operational levers embedded in PW Consulting’s full Worldwide Homosalate Market report. The document contains the proprietary models, supplier scorecards, scenario simulations and contract templates that teams will need to translate headline forecasts into executable 2026 plans. For Boards, procurement leaders, R&D heads and M&A teams preparing 2026 budgets, the report is engineered to accelerate confident decision‑making under uncertainty.
Contact and availability
To download the full report, access the complete datasets and view supplier profiles and regulatory heatmaps, please visit our report landing page. PW Consulting stands ready to run bespoke workshops to map the report’s scenarios onto your P&L and operational plans for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Homosalate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Truck Mirror System Market Poised for 7.5% CAGR Through 2026–2032
By pmarketresearch, 2026-07-17
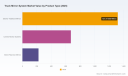
Worldwide Truck Mirror System Market — Strategic Preview for 2026 Decision‑Making
Executive summary
PW Consulting’s forthcoming market research brief on the Worldwide Truck Mirror System Market synthesizes seven years of historical observation (2020–2025) and a seven‑year forecast horizon (2026–2032) to deliver actionable findings for senior executives, procurement leads, R&D chiefs and corporate strategy teams. The industry is in a transitionary phase: traditional exterior mirrors remain fundamental, but digitally enabled camera monitor systems (CMS) and hybrid solutions are scaling rapidly. Our analysis shows the total market expanding from roughly USD 1.55 billion in 2020 to about USD 2.22 billion in 2025, and—at a compound annual growth rate (CAGR) of 7.5%—to an estimated USD 3.68 billion by 2032. Market concentration is moderate: the top three firms account for approximately 38.5% of value, and the top five for about 52.1%, leaving space for targeted challengers and vertical integration plays.
Worldwide Truck Mirror System Market
Why this matters for 2026 planning
- Capital allocation: forecasted mid‑single‑digit to high‑single‑digit growth supports continued investment in digital vision technologies, while still protecting legacy mirror manufacturing capacity for several years.
- Product strategy: OEMs and Tier‑1 suppliers must balance short‑term compliance and customer preferences for mirrors with medium‑term commitments to CMS platforms that deliver fuel efficiency and advanced safety features.
- M&A and partnership timing: moderate concentration and active regulatory windows create opportunistic timing for bolt‑on acquisitions, tech licensing, and strategic JV formation through 2026 and beyond.
Market trajectory and structural drivers
The mirror systems market is being reshaped by three mutually reinforcing forces. First, regulatory evolution—both exemptions that permit camera systems and standards that define field‑of‑vision requirements—has opened pathways for digital alternatives while preserving performance and safety baselines. Second, OEM aerodynamic and fuel‑efficiency programs are creating a halo effect that favors lower‑drag camera solutions in long‑haul and heavy‑duty applications. Third, supplier capability convergence (optics + electronics + software) is accelerating innovation cycles and changing supplier competitiveness from purely mechanical competence to systems integration capability.
Worldwide Truck Mirror System Market
These forces are reflected in the numbers: the market grew materially from 2020 to 2025 and our model—driven by technology substitution, replacement cycles, and increasing penetration of digital systems—projects sustained growth through 2032 at a 7.5% CAGR. That trajectory implies expanding addressable spend for vision subsystems, aftercare and retrofitting services, and software/maintenance revenue streams tied to camera ecosystems.
Worldwide Truck Mirror System Market
Technology and product dynamics
- Camera Monitor Systems (CMS): Rapid maturation of CMS hardware and human‑machine interface design is delivering demonstrable safety and aerodynamic benefits. ISO 16505 and parallel standards provide a technical route for regulatory acceptance, and several high‑profile OEM integrations and exemption filings demonstrate momentum.
- Hybrid approaches: Many operators prefer redundancy—retaining optical mirrors while adding camera-based close‑range views or blind‑spot overlays—so hybrid architectures remain strategically important in the medium term.
- Software, calibration and servicing: The "mirror" is increasingly a software‑centric platform. Calibration, OTA updates, image processing and maintenance contracts will be meaningful profit pools beyond hardware margins.
- Materials and supply chain: Specialized mirror glass, coatings and heated glass remain non‑commoditized inputs. Supply chain resilience for glass, optics and electronic components must be managed as part of procurement strategy.
Regulatory and standards landscape
Policy developments are a central determinant of adoption timing and are therefore a core scenario planning variable for 2026 decisions. In North America, time‑limited exemptions to traditional mirror requirements have allowed early commercial deployments of CMS platforms while regulators study long‑term rule updates. Internationally, UNECE and related regulations continue to raise field‑of‑vision expectations and carve technical paths for electronic alternatives. NHTSA research into camera systems and standards such as ISO 16505 are additional anchors for market acceptance.
For strategy teams, the practical implication is to treat regulatory trajectories as dynamic constraints: exemption programs enable pilots and early OEM integrations, but broad adoption will accelerate only as permanent regulatory clarity and harmonized standards emerge. Companies that engage proactively in standards work and exemption pilots will be advantaged in product validation and aftermarket certification.
Competitive landscape — capabilities and moves to watch
The market’s competitive topology blends global Tier‑1 suppliers, specialized mirror specialists, and technology‑centric entrants. Key players include mature systems integrators with multi‑modal portfolios, long‑standing OEM mirror manufacturers, and newer CMS specialists. Important dimensions of competitive advantage are systems integration, regulatory relationships, OEM platform access, aftermarket distribution and modular service offerings.
- Magna International (Aurora, Canada): A global integrator with advanced vision systems and hybrid camera‑mirror technologies. Strengths include deep OEM relationships and systems engineering capabilities that enable platform‑level integration on heavy‑duty vehicles.
- Samvardhana Motherson Reflectec (SMR) (Stuttgart/India operations): A specialist in exterior/interior mirrors with strong manufacturing scale and electric actuation expertise. Their hybrid and electrically extendable systems are a fit for fleets requiring durability and retrofittable solutions.
- Ficosa (Barcelona, Spain): Focused on rear‑view systems across trucks and light commercial vehicles, with product breadth that spans prismatic interior mirrors to full exterior ranges—positioned to serve OEMs seeking single‑source suppliers.
- Stoneridge, Inc. (Novi, Michigan): A CMS pioneer with regulatory progress and OEM integrations (e.g., deployment on major truck platforms). Their MirrorEye® product portfolio illustrates the route to substituting mirrors under regulatory exemptions.
- Specialized manufacturers (RETRAC, Rosco, Lucerix, K Source, INMESA, Muth, Tokai Rika, Murakami): These firms combine legacy OEM relationships, aftermarket distribution and niche product leadership. They are attractive partners for retrofit programs, regional distribution and targeted product innovations.
Recent industry moves—vehicle integrations announced by OEMs, CMS exemptions and renewals, and product showcases at sector events—signal that 2025–2026 is a high‑velocity window for product validation and commercial rollouts. Firms that secure OEM platform access and regulatory endorsments during this window will gain a durable lead.
Strategic implications and recommended actions for 2026
PW Consulting recommends a portfolio approach for decision‑makers in 2026, balancing near‑term revenue capture with longer‑term platform bets. Key actions include:
- Prioritize modular CMS capability: Invest in modular, software‑upgradable camera platforms that can be certified regionally and function across vehicle classes—this preserves optionality as regulations harmonize.
- Engage in regulatory processes: Allocate resources to participate in exemption pilots, standardization bodies and regulatory comment cycles to shape technical definitions and secure early approvals.
- Secure supply chain resilience: Lock multi‑source agreements for critical optics and coatings, and develop contingency plans for electronics and semiconductor supply to minimize production disruptions.
- Design aftermarket and service streams: Build calibration, update and servicing offerings as premium revenue lines tied to CMS installations and fleets’ uptime requirements.
- Pursue targeted M&A: Use the moderate concentration and active technology shifts to acquire niche CMS capabilities, software know‑how or regional distribution networks that accelerate time‑to‑market.
- Pilot hybrid installations: For risk‑averse fleets and regions with regulatory uncertainty, offer hybrid mirror + camera solutions to capture early revenue while enabling gradual technology migration.
What the PW Consulting report delivers
The full report is designed as a strategic toolkit for 2026 action. It includes:
- Scenario‑driven market forecasts through 2032 with sensitivity analyses and adoption curves by technology pathway.
- Competitive benchmarking and detailed vendor dossiers that assess engineering depth, OEM access, aftermarket channel strength and M&A posture.
- Regulatory mapping across major jurisdictions, including exemption timelines, standards alignment and recommended engagement strategies.
- Supply chain stress tests for key components (glass, coatings, cameras, electronics) and recommended mitigation playbooks.
- Commercial playbooks: go‑to‑market templates for OEM partnership negotiations, retrofit programs, pricing strategies and fleet conversion scenarios.
- Investment and M&A frameworks prioritizing targets by strategic fit, integration complexity and expected return windows.
How PW Consulting supports implementation
Beyond the report, PW Consulting offers tailored advisory packages to convert insight into execution: due‑diligence support for acquisitions, pilot design and measurement for exemption applications, supplier selection and contract negotiation support, and commercial rollout planning for OEMs and fleets. Our advisory engagement is structured to bridge boardroom strategy with the operational workstreams required to capture the forecasted growth.
Conclusion — a strategic teaser
The truck mirror systems market in 2026 sits at an inflection point: the total addressable market has expanded meaningfully since 2020, and sustained growth at a 7.5% CAGR through 2032 will create new value pools for hardware, software and services. The competitive field favors incumbents with systems integration capabilities and new entrants that can move fast on regulatory pathways and software differentiators. For leaders assessing capital deployment, partnership, or M&A in 2026, the window to act is now—but the tactical choices are nuanced and regionally contingent.
PW Consulting’s full Worldwide Truck Mirror System Market report provides the complete datasets, granular segmentation, and proprietary scenario matrices needed to finalize 2026 strategies. To access the in‑depth analysis, vendor profiles, and executable playbooks referenced here, please visit our official report page and request the full briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Truck Mirror System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com