

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Chromium Salt Market Set for 3.15% CAGR Through 2026–2032, Says New Report

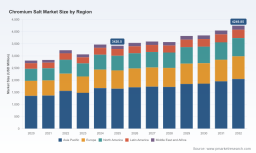
Worldwide Chromium Salt Market — Strategic Outlook and Actionable Insights for 2026
Executive synopsis
PW Consulting’s latest Worldwide Chromium Salt Market report delivers a disciplined, decision-focused view of a market transitioning from volume-driven cycles to value- and compliance-driven dynamics. The industry returned from cyclical troughs in the early 2020s and, after recovering to roughly USD 3.42 billion in our 2025 base year, is projected to expand to the mid-single‑digit billions by the end of the 2026–2032 forecast window — reaching approximately USD 4.25 billion by 2032 at a compound annual growth rate of 3.15% (2026–2032). For executives making capital allocation, sourcing, and regulatory-compliance choices in 2026, the report translates these macro trajectories into pragmatic, stage‑gated actions that reduce downside and capture premium upside.
Worldwide Chromium Salt Market
Why this report matters for 2026 decision-makers
- Timing: 2026 will be a hinge year — market momentum is modest but structural drivers (regulatory tightening, feedstock concentration, and targeted capacity additions) create distinct windows for premium capture or margin compression depending on strategy.
- Actionability: The report converts market forecasts into playbooks for procurement, manufacturing footprint, product-mix optimization, and M&A screening — not just high-level charts but executable next steps and decision templates.
- Risk-to-reward clarity: We quantify scenarios where price movements, regulatory restrictions, or regional supply interruptions materially affect margin pools across the value chain — enabling CFOs and business unit leaders to stress-test 2026 budgets.
Market dynamics: what is changing and why it matters
Three structural vectors define the near-term strategic landscape.
Worldwide Chromium Salt Market
- Regulatory acceleration: European and international authorities have intensified scrutiny of hexavalent chromium. Notably, ECHA concluded in 2025 that certain Cr(VI) substances warrant EU-wide restrictions, and the European Commission’s December 2025 guidance accelerated timelines toward a horizontal restriction that could enter into force between late‑2027 and early‑2028. That regulatory pathway compresses time for compliance investments and creates an early-mover premium for low‑Cr(VI) alternatives and certified supply chains.
- Feedstock concentration and price pressure: Global chromite ore production recovered in 2025 (an estimated ~3% increase year-on-year), with South Africa remaining the dominant producer. Tighter concentrate availability and upward pressure on ore benchmarks in early 2026 — with quoted South African concentrate trading at roughly $315/ton CIF in reported market checks — mean upstream volatility will continue to transmit to producers and buyers. Hedging, diversified procurement, and vertical integration become strategic levers.
- Capacity dynamics and regional moves: Targeted capacity additions and strategic expansions are being executed by incumbents and new entrants. These moves are selective and frequently accompanied by pricing actions or integration plays that reshape regional competitive intensity. The net effect is a market that is not simply growing but being re‑shaped in terms of where value and compliance capability sit.
Competitive landscape — what to watch
The chromium salts sector remains moderately concentrated: the largest three producers account for roughly half of global capacity, while the top five push the concentration higher. This concentration creates both oligopolistic pricing power in certain product streams and competitive opportunity in niche, high‑purity, or compliant segments.
Worldwide Chromium Salt Market
- Lanxess AG (Germany) — A global integrator with a diversified portfolio in chrome chemicals, Lanxess remains a strategic bellwether for Western‑market product availability and compliance trajectories. Its European footprint and technical capability make it a critical partner for companies seeking certified low‑Cr(VI) solutions.
- Vishnu Chemicals Limited (India) — An example of capacity-led growth in emerging market supply. The company’s recent program to increase sodium dichromate capacity is a reminder that cost-competitive manufacturing bases in Asia will continue to be price anchors for bulk product lines, even as higher‑value, compliance‑oriented demand shifts elsewhere.
- Hubei Zhenhua Chemical (China) — Active on both price and acquisition fronts, recent moves include substantial price adjustments for metal chromium and strategic acquisitions that expand salt capacity. Such integrated playbooks show how Chinese producers are consolidating supply chains to capture margins across feedstock-to-product flows.
- New and regional entrants — From planned new metal chromium plants in the United States to additional lines in Turkey and Kazakhstan, smaller incumbents and greenfield projects are reshaping regional access. North American on‑shoring initiatives, in particular, will have outsized strategic impact on specialty and high‑purity segments.
- Specialty and laboratory suppliers — Companies focused on high‑purity salts and analytical reagents remain differentiated from bulk producers, commanding margin premiums and acting as suppliers to electronics, research, and specialty manufacturing sectors.
Recent strategic moves and tactical implications
- Increased metal chromium prices and phased price rises by some producers underscore the susceptibility of midstream and downstream margins to upstream swings. Buyers should plan for tiered procurement strategies that combine short-term contracts with selective forward coverage.
- Capacity additions and acquisitions among major producers create localized oversupply risk in select product streams while tightening supply elsewhere — a divergence that favors firms that can dynamically adjust product mix and route to market.
- Regulatory timelines compress capital expenditure cycles: companies that defer compliance investments risk both market exclusion in key regions and higher retrofitting costs. Early compliance and certified supply chain programs open premium channels, especially with large industrial buyers and OEMs that have strong ESG requirements.
What the PW Consulting report contains (practical, implementable modules)
Designed for C-suite and functional leaders, the report moves beyond descriptive analysis to provide tools you can use in 2026:
- Market sizing and forward scenarios calibrated to 2026 planning cycles — including a base, accelerated‑regulation, and feedstock‑shock scenario set that maps to profit-and-loss and cash‑flow sensitivity templates.
- Supply‑chain heat maps that identify single‑point failures at the mine, converter and salt‑processing stages, with mitigation playbooks (dual-sourcing templates, inventory policy triggers, and near‑shoring decision trees).
- Regulatory readiness roadmaps tailored to EU, North American and key Asian jurisdictions — detailing timelines, investment ranges, testing protocols, and supplier certification checklists without prescriptive legal advice but with operationally focused action steps.
- Commercial playbooks for producers and buyers: pricing models, contract clause templates for pass‑throughs and force majeure, and channel segmentation strategies that segregate bulk from specialty flows.
- M&A and capital allocation screening: target archetypes, due‑diligence scorecards emphasizing feedstock security and environmental liabilities, and integration checklists to preserve margins post‑acquisition.
- Company briefs and plant‑level intelligence on leading players and notable greenfield/expansion projects, coupled with a ranked list of supply partners for different risk profiles. (Note: granular, downloadable tables and line‑item breakdowns are reserved for the full dataset.)
Strategic recommendations for executive teams in 2026
- Producers: Prioritize compliance-enabled product differentiation. Invest selectively in emissions and effluent controls to unlock access to regulated markets and secure long‑term offtake arrangements with OEMs and industrial users who will penalize non‑compliant suppliers.
- Buyers (large consumers, OEMs): Re‑architect contracts to combine shorter rolling volumes with strategic long‑term lots from certified suppliers. Implement a two‑tier procurement model that protects against upstream shocks while optimizing price for stable bulk needs.
- Investors and financial sponsors: Seek assets with defensible feedstock access or clear pathways to regulatory compliance. Distinguish between scale plays in bulk commodity salts and margin-rich specialty niches where consolidation and technical expertise drive value.
- Risk and sustainability officers: Accelerate chromium‑specific supplier audits and map potential liabilities from legacy operations. A proactive remediation and certification program will become a table stake in tendering processes by late 2027.
How PW Consulting’s forecast informs near-term capital and commercial choices
The market’s projected CAGR of 3.15% over the 2026–2032 forecast period signals modest top‑line expansion but significant structural churn beneath the aggregate numbers. In practice, that means the best returns in 2026 will come from reallocating capital to compliance-enabled capacity, securing feedstock with flexible contractual terms, and executing targeted commercial moves rather than broad-based capacity builds. Companies that treat the 2026 planning cycle as a strategic reset — optimizing for regulatory resilience and supply security — will outperform peers even in a low‑growth, moderately concentrated market.
Next steps and where to find the detailed intelligence
This release is a strategic précis intended to highlight the report’s decision‑centric value. The full PW Consulting Worldwide Chromium Salt Market report includes the complete dataset, company profiles, scenario spreadsheets, regulatory timelines, and downloadable procurement templates that operational teams can implement immediately. To access the detailed segment tables, plant‑level capacities, and the proprietary risk scores used in our M&A screening, please visit the PW Consulting report page linked in our distribution materials.
Closing observation
2026 will reward clarity of strategy more than scale of ambition. With regulatory timetables accelerating and feedstock dynamics tightening, the companies that combine disciplined compliance investments, adaptive procurement, and targeted commercial plays will convert a moderate market expansion into outsized strategic advantage. PW Consulting’s report is designed to make those choices measurable, repeatable, and actionable.
For detailed analysis of this topic, please visit the official page: Worldwide Chromium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com