

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Structural Conductive Polymer Market Poised to Reach USD 1.04 Billion by 2032, Growing at an 8.12% CAGR

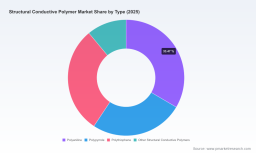
Worldwide Structural Conductive Polymer Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, Worldwide Structural Conductive Polymer Market (base year 2025), delivers a focused, actionable intelligence product designed to inform capital allocation, product strategy, and supply-chain decisions through 2026 and beyond. Grounded in a six‑year historical analysis (2020–2025) and a forward-looking forecast (2026–2032), the report models market expansion at a compound annual growth rate (CAGR) of 8.12%. The global structural conductive polymer market reached an estimated USD 603.36 Million in 2025 and, under our central scenario, is projected to surpass USD 1.04 Billion by 2032. This briefing highlights the report’s strategic value for executives preparing decisions in 2026 while deliberately preserving the detailed segment tables and proprietary outputs that are available in the full report.
Worldwide Structural Conductive Polymer Market
Why this report matters for 2026 decisions
-
Timing and scale: With an 8.12% CAGR over the forecast horizon, structural conductive polymers are moving from niche specialty materials toward broader structural and functional integration across automotive, electronics, medical, and defense value chains. 2026 is a pivotal planning year for manufacturers and investors: technology selection, capital investment, and supplier commitments made in 2026 will determine competitiveness through the rest of the decade.
Worldwide Structural Conductive Polymer Market -
Cross‑domain relevance: These materials serve simultaneous requirements—mechanical strength, electrical functionality (EMI management, conductivity), and weight reduction—making them integral to electrification, miniaturization, and sensorization trends. Decisions in 2026 must therefore balance materials engineering with system‑level tradeoffs.
Worldwide Structural Conductive Polymer Market -
Market structure and consolidation signals: The market presents moderate concentration: our analysis shows a top‑three concentration that leaves room for differentiated suppliers and a top‑five composition that reflects both established chemical majors and highly specialized compounders. This structure creates opportunities for targeted partnerships and M&A to secure scale or unique capabilities.
What the report delivers (practical assets for immediate use)
-
Proprietary market model: a dynamic revenue and volume model (2020–2032) with scenario toggles for adoption curves, raw material price shocks, and application substitution—built so finance teams can plug in internal assumptions and generate bespoke forecasts.
-
Go‑to‑market playbooks: differentiated routes for compounders, OEMs, and tier suppliers including pricing strategies, qualification roadmaps, and sample‑to‑production timelines for high‑confidence applications (e.g., EMI shielding, structural battery housings, bio‑compatible sensors).
-
Supply‑chain and raw‑material playbook: supplier maps, risk heatmaps, and hedging levers for monomers (aniline, pyrrole, EDOT, thiophene) and key dopants. The package includes sensitivity analyses showing margin erosion points tied to raw‑material cost movements and lead‑time disruption scenarios.
-
Regulatory and safety matrix: practical compliance checklists for working with toxic or flammable monomers, recommended worker‑protection investments, and environmental controls that reduce certification risk and accelerate customer acceptance.
-
Technology and IP landscape: vendor capability profiles, materials readiness levels, and licensing/partnering templates to accelerate integration of PEDOT:PSS, carbon‑nanotube, and conductive‑filler systems into structural formulations.
-
M&A and partnership scorecards: a screening framework with valuation multipliers for revenue growth, margin expansion potential, and strategic fit—designed to reduce diligence cycles in competitive processes.
Key strategic insights for 2026
1) Demand inflection points are application‑specific. Electrification (battery housings and conductive structural components) and high‑performance consumer and industrial electronics continue to be primary drivers, with medical sensors and defense systems providing premium, low‑volume opportunities. The upshot for 2026 planning: prioritize development and qualification resources on two parallel tracks—high‑volume, cost‑sensitive grades and low‑volume, high‑value specialty grades that command higher margins.
2) Raw‑material dynamics will shape near‑term economics. Conductive polymers rely on a constrained set of monomers and dopants; production costs are sensitive to both feedstock prices and the availability of specialized dopants such as ammonium persulfate and ferric chloride. Notably, certain aniline market cycles have recently eased—we observed a downward movement in Chinese aniline prices into late 2024—however, volatility remains. Procurement strategies including longer‑term offtakes, geographic diversity, and selective vertical integration will materially affect cost competitiveness in 2026.
3) Regulatory and occupational safety requirements are non‑negotiable. Several commonly used monomers carry toxicity and flammability risks that trigger stringent controls. Firms that invest early in compliant production lines and transparent safety data packages will accelerate customer qualification and reduce time‑to‑market, particularly for medical and aerospace contracts.
4) Differentiation through formulation and processing is decisive. Competitive advantage is increasingly derived from the ability to maintain mechanical integrity while delivering consistent electrical performance through processing and across temperature and humidity ranges. Companies capable of supplying off‑the‑shelf masterbatches as well as bespoke engineered compounds will capture broader wallet share across OEMs and tier suppliers.
Competitive landscape: positioning and tactical moves
The market is populated by global chemical majors, specialist compounders, and materials innovators. Established players bring scale and channel access; specialists provide formulation depth and rapid customization. Key archetypes we profile include:
-
Integrated chemical majors that offer conductive polymer grades as part of broader resin portfolios, focusing on automotive electrification and energy storage components.
-
Engineering compounders that excel at custom conductive formulations and rapid qualification cycles for electronics and EMI shielding.
-
Specialty materials innovators advancing high‑purity conductive systems (e.g., PEDOT:PSS) and enabling sensor and biomedical applications.
Recent strategic moves underscore these archetypes: a European specialist expanded U.S. production capacity in 2025 to shorten lead times and support North American demand growth; a global resin producer launched a new series of conductive polycarbonate grades targeting battery system integration in 2024; and a compounder introduced carbon‑nanotube‑reinforced conductive plastics for advanced EMI shielding in 2023. These actions signal that both capacity buildouts and differentiated product introductions are active levers for market share gains.
Recommended actions for corporate leaders in 2026
-
For chemical and compound manufacturers: prioritize a two‑track investment model—scale production for cost‑sensitive grades while funding pilot lines for high‑value specialty formulations. Use our scenario model to size break‑even points under raw‑material stress tests.
-
For OEMs and tier suppliers: deploy a materials qualification portfolio that shortlists dual‑source suppliers across the function/mechanical matrix and require supplier transparency on raw‑material sourcing and safety controls.
-
For investors and M&A teams: apply the PW Consulting scorecard to prioritize targets that combine proprietary formulations with near‑term revenue traction in electrification or medical sensing; value candidates not only on current sales but on qualification pipelines and IP defensibility.
-
For procurement and operations: implement hedging and supplier diversification strategies for monomers and dopants, and accelerate transition plans that reduce dependency on single‑source feedstocks.
-
For R&D leaders: focus on formulation robustness (moisture/thermal stability), processing tolerance, and scalable compounding routes—these attributes are decisive in converting engineering samples into production parts.
How PW Consulting’s report reduces execution risk in 2026
Our deliverables are built to shorten decision cycles. The market model can be recalibrated with internal assumptions to produce tailored investment cases in hours instead of weeks. The supplier and raw‑material playbooks translate to practical procurement actions (term sheet language, KPI sets, and qualification milestones). The regulatory matrix reduces certification time by clearly identifying the control points that most frequently delay acceptance in medical and aerospace programs. Collectively, these tools reduce technical, commercial, and regulatory uncertainty at the critical moment when 2026 budgets and capital plans are being finalized.
Invitation to explore the full intelligence set
This briefing is intended as a concise strategic orientation. The full PW Consulting report contains the granular segmentation tables, proprietary demand‑by‑end‑use and by‑type models, supplier scorecards, and executable playbooks that corporate teams and investors need to execute with confidence. To access the detailed datasets, scenario workbooks, and workshop‑ready materials, please visit the PW Consulting report page or contact our industry analysts. For clients who commission bespoke engagements, we offer accelerated due diligence and a 48‑hour decision kit that maps our findings directly to your business case.
Prepared by PW Consulting’s Advanced Materials Practice — our team combines market economists, polymer scientists, and senior M&A advisors to help organizations convert materials strategy into profitable products and defensible market positions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Structural Conductive Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com