

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Child Rehabilitation Market to Grow at 7.21% CAGR, Surpassing USD 20.34 Billion by 2032 as North America and Physical Therapy Lead
By pmarketresearch, 2026-07-17
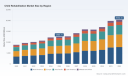
Worldwide Child Rehabilitation Market: Strategic Imperatives for 2026 — PW Consulting
Executive summary
PW Consulting’s latest Worldwide Child Rehabilitation Market report (base year 2025, forecast 2026–2032) frames a fast-evolving clinical, commercial, and regulatory landscape that will shape executive decision-making throughout 2026. The global market—valued at approximately USD 12,503.7 Million in 2025—is projected to grow to roughly USD 20,342.4 Million by 2032, representing a compound annual growth rate (CAGR) of 7.21% across the forecast period. These headline metrics capture a market that is sizable, growing steadily, and characterized by a persistent balance between clinical specialization and enterprise fragmentation.
Worldwide Child Rehabilitation Market
Why this matters for 2026 strategy
-
Rapid but uneven growth: Steady mid-single-digit-plus expansion means growth alone will not guarantee success; leaders must choose which levers to pull—scale, specialization, or partnerships—to outpace peers in important subdomains.
Worldwide Child Rehabilitation Market -
Fragmented provider base: Market concentration remains low (CR3 ≈ 14.85%, CR5 ≈ 21.3%), signaling opportunity for consolidation, differentiated service models, and roll-up strategies that combine clinical depth with operational scale.
Worldwide Child Rehabilitation Market -
Policy and reimbursement pressure: Regulatory and payer shifts are actively reshaping service delivery and revenue models; organizations that embed regulatory foresight into product and service roadmaps will substantially reduce execution risk.
Market trajectory and macro drivers
The market trajectory reflected in our report balances demographic and clinical demand drivers—such as rising detection of developmental and neurological conditions, increased survivorship of complex pediatric conditions, and broader acceptance of early-intervention therapies—against cost, workforce, and regulatory constraints. From a revenue perspective, the market’s advance from an estimated USD 12.5 billion in 2025 to an estimated USD 20.3 billion in 2032 underlines both the size of opportunity and the need for disciplined strategic choices.
Key demand-side accelerants include advances in assistive technologies and robotics, greater integration of community- and school-based rehabilitation models, and caregiver-centered service designs. On the supply side, workforce scarcity—illustrated by rising compensation levels for specialized clinicians—along with capital investments in specialized facilities, will be decisive determinants of competitive advantage in 2026 and beyond.
What the PW Consulting report contains (practical, action-oriented)
-
Proprietary demand forecasts and scenario analysis that allow users to model base, upside, and downside outcomes across the 2026–2032 horizon.
-
Go-to-market playbooks for providers, device manufacturers, payers, and digital therapy platforms, with prioritized tactics for customer acquisition, reimbursement negotiations, and service bundling.
-
Regulatory and payer mapping specific to pediatric rehabilitation—covering accreditation requirements, reimbursement mechanisms, and common payer denial patterns—paired with remediation checklists and stakeholder engagement templates.
-
Operational blueprints for workforce optimization, including staffing models, telehealth integration strategies, and skills-development roadmaps for multidisciplinary teams.
-
Technology and product assessment: comparative evaluations of robotics, wearables, tele-rehab platforms, and mobility devices, plus a risk matrix that flags device classes subject to heightened regulatory scrutiny.
-
M&A and partnership playbook: target attributes, valuation heuristics, and integration risk mitigations tailored for roll-ups, joint ventures with school districts, and cross-border expansion.
Competitive landscape — who to watch in 2026
The provider landscape is a mix of national hospital networks, specialized pediatric systems, regional therapy groups, and pure-play pediatric therapy clinics. Several organizations are executing visible growth and capability plays that every board should monitor:
-
Kindred Healthcare — Operating both inpatient and outpatient pediatric rehabilitation footprints, Kindred’s model emphasizes specialized multidisciplinary programs for neurological and orthopedic conditions. Their integrated continuum approach is a blueprint for scaling clinical protocols across facility types.
-
Encompass Health — With investments in hospital-based pediatric rehab programs and strategic community partnerships (including recent collaborations with school districts), Encompass is testing hybrid delivery models that distribute care closer to where children live and learn.
-
Select Medical — Through its pediatric-focused subsidiary, Select Kids, the organization is consolidating expertise in brain injury and complex neurorehabilitation, and is well-positioned to translate acute-care relationships into longitudinal rehabilitation pathways.
-
Children’s Specialized Hospital — As a leading pediatric inpatient rehabilitation center, the organization is expanding capacity and capabilities (including a recent pediatric brain injury unit opened in late 2025), highlighting the premium value attached to high-acuity specialty services.
-
Shriners Children’s — A global network focused on orthopedic and burn rehabilitation, Shriner’s recent adoption of robotic exoskeletons for pediatric gait training demonstrates the accelerating integration of advanced assistive technologies into clinical workflows.
-
AbilityPlus Therapy Services — A multi-clinic therapy operator focused on developmental delays and autism spectrum disorders, AbilityPlus exemplifies the regional clinic growth model optimized for outpatient volume and caregiver engagement.
Recent moves and tactical signals
-
Facility and capability expansion: Children’s Specialized Hospital opened a new pediatric brain injury unit in October 2025, indicating continued investment in high-complexity inpatient services.
-
Technology adoption: Shriners Children’s integrated robotic exoskeletons into gait training programs during mid-2025—an early signal that capital-intensive digital therapeutics will increasingly complement human-delivered therapy.
-
Community integration: Encompass Health’s 2025 partnerships with school districts signal a pragmatic shift toward co-located and community-based service models that improve access while controlling per-patient costs.
Regulatory, reimbursement, workforce and device risk dynamics
-
Regulatory and accreditation: Pediatric rehabilitation programs must adhere to children’s hospital standards and family-centered care mandates; Joint Commission guidance requires deliberate investments in child life and family engagement services.
-
Payer environment: Reimbursement complexity persists. For example, outpatient therapy reimbursement frameworks include fee schedules with therapy cap considerations and pediatric-specific exemptions that require active management at the billing and contract negotiation levels.
-
Workforce scarcity: Labor market pressure is significant—average compensation for specialized clinicians has risen materially, creating margin and capacity challenges for growth. Staffing models that leverage telehealth, cross-training, and per-diem networks will be essential stopgaps in 2026.
-
Device safety and compliance: Rising device sophistication brings regulatory risk. Some pediatric mobility devices face Class III risk profiles absent growth-adjustable safety standards—an area where procurement and clinical teams must enforce stricter vendor qualification criteria.
-
Privacy and telehealth: Child-specific privacy rules (including parental consent requirements for minors in telehealth) add operational complexity to remote-delivery models and must be embedded in vendor contracts and clinical workflows.
Strategic actions for 2026 — a practical checklist
-
Prioritize high-ROI service lines: Identify 1–2 specialty programs (e.g., neurorehab, gait/orthopedics, or integrated developmental clinics) to scale as centers of excellence, while using partnerships to fill gaps.
-
Operationalize payer intelligence: Implement a payer-playbook that standardizes authorization pathways, documents pediatric-specific billing exceptions, and trains front-line teams on denial appeals.
-
Design workforce resilience: Deploy blended delivery models combining onsite specialists with tele-rehab and regional floating clinician pools to mitigate recruitment bottlenecks and control labor cost inflation.
-
De-risk technology adoption: Establish an internal technology governance committee to vet robotics, digital therapeutics, and devices against regulatory and pediatric-safety checklists before capital deployment.
-
Explore targeted M&A and alliances: Use selective bolt-on acquisitions to gain clinical depth or geographic coverage, and pursue strategic alliances with schools and community health systems to extend pathways to care.
How PW Consulting helps
Our report is purpose-built for executives needing to convert market trajectory into executable plans for 2026. Beyond headline forecasts, the deliverable contains customizable financial models, commercial playbooks, regulatory compliance templates, and integration checklists that accelerate decision cycles and reduce execution risk. We combine clinician-informed operational insights with market-level scenario work so that leaders can prioritize investments with clarity.
Conclusion and next step
The child rehabilitation market presents durable growth and mission-driven opportunity—but winning in 2026 will require more than optimism. It calls for targeted investments in specialty programs, a disciplined approach to reimbursement and regulation, and operational innovations that stretch scarce clinical resources. Our Worldwide Child Rehabilitation Market report delivers the analytic rigor and tactical guidance needed to make those choices with confidence.
To access the full intelligence brief, customizable models, and the complete set of strategic playbooks and annexes, please visit PW Consulting’s report page or contact our advisory team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Child Rehabilitation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ferric Oxide Market at USD 2,400.8 Million in 2025, Poised to Reach USD 3,184.8M by 2032 at 4.12% CAGR — Asia Pacific, Synthetic Oxides Lead
By pmarketresearch, 2026-07-17
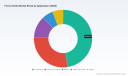
Worldwide Ferric Oxide Market — Strategic Imperatives for 2026: A PW Consulting Preview
PW Consulting today publishes an executive preview of our forthcoming Worldwide Ferric Oxide Market study — a practitioner-focused intelligence product built to arm corporate leaders with the decision frameworks they need in 2026. Anchored in a rigorous historical base (2020–2025) and a detailed forecast horizon (2026–2032), the analysis demonstrates why ferric oxide is no longer a simple pigment commodity but a strategically important material across construction, coatings, plastics and emerging battery applications. Our model shows the global ferric oxide market expanding at a compound annual growth rate (CAGR) of 4.12% from the 2025 base year (2025 market size: USD 2,400.76 Million) through 2032 (2032 projection: USD 3,184.84 Million). This preview outlines why those headline numbers matter — and how leading firms should convert insight into action in 2026.
Worldwide Ferric Oxide Market
Why 2026 Is a Strategic Pivot
-
Demand quality is shifting. Mature demand in construction and paints remains volume-driven, but premiumization — higher-performance pigments with UV resistance, thermal stability and tailored surface chemistry — is accelerating. A growing slice of ferric oxide demand is being redefined by functional requirements rather than color alone.
Worldwide Ferric Oxide Market -
Battery material opportunities are real and material. Recent product and partnership announcements show major pigment manufacturers positioning ferric oxide variants for lithium-iron-phosphate (LFP) cathodes and other specialty battery uses. These moves change margin profiles and capital allocation priorities for producers that choose to compete in this adjacent space.
Worldwide Ferric Oxide Market -
Regulation and upstream volatility are tightening the operating envelope. Policymaker action on emissions standards and ongoing shifts in iron-feedstock markets (linked to global steel and scrap dynamics) are increasing both compliance costs and supply-side risk premiums for producers and users alike.
What the PW Consulting Report Delivers — Practical, Actionable, and Transaction-Ready
We designed the full report as a toolkit for executives, not an academic exercise. Highlights include:
-
Integrated demand and price models: bottom-up demand build from 2020–2025, cross-checked with top-down macro drivers to produce scenario-driven forecasts across 2026–2032.
-
Commercial scorecards for suppliers and technologies: objective supplier KPIs, capacity maps, and product-grade comparators that enable rapid benchmarking during procurement or due diligence.
-
Regulatory & ESG playbooks: mapping of emissions rules, permitting risks and decarbonization levers with prioritized capex and OPEX options to meet common corporate net-zero timelines.
-
M&A and partnership frameworks: target screening criteria and valuation levers for bolt-on acquisitions, joint ventures and technology partnerships, including sensitivity testing for price swings and raw-material stress scenarios.
-
Operational levers and implementation roadmaps: actions to reduce product carbon intensity, optimize grade mix, and capture margin uplift through product differentiation or downstream integration.
Competitive Landscape — Consolidation, Differentiation, and Strategic Positioning
The ferric oxide sector sits between commodity-scale capacity and pockets of specialty innovation. Market concentration metrics indicate a moderate level of concentration (CR3 approximately 38.4%; CR5 approximately 52.15%) — enough scale among leading players to shape pricing and technical standards, but with room for mid‑market specialists and regional producers to retain influence.
Key strategic archetypes emerge from our company review:
-
Global integrated majors (e.g., LANXESS AG, BASF SE) — invest in application development, sustainability technologies and strategic partnerships to move into high-value specialty segments and battery materials.
-
Specialty-focused firms (e.g., Cathay Industries / Oxerra, Venator, Huntsman) — pursue technical differentiation and global distribution networks to capture premium coatings and plastics demand.
-
High-capacity regional operators (e.g., select Chinese and Indian producers) — compete on scale and low-cost supply while selectively upgrading product portfolios for export markets.
-
Natural pigment and niche suppliers (e.g., Applied Minerals, Alabama Pigments) — maintain strong positions in specific applications and leverage unique feedstocks where synthetics cannot easily displace demand.
Recent competitive moves reinforce these archetypes. Examples include partnerships targeting nanopowder development for battery cathodes, acquisitions that add specialty process capacity, and operational awards tied to energy-recovery technologies. These actions point to a bifurcating market where scale remains important, but technical capability and sustainability performance create outsized commercial value.
Supply-Chain and Raw-Material Dynamics to Watch
-
Feedstock sensitivity: ferric oxide production is tied closely to iron-ore derivatives (hematite, magnetite) and the broader health of the steel sector. Volatility in scrap and upstream ore pricing can compress producer margins quickly; procurement and hedging strategies must reflect that exposure.
-
Regulatory headwinds: policymakers are revisiting emission standards in key markets. For example, recent reconsideration of certain U.S. emissions standards elevates permitting and compliance risk for integrated operations and exposes non-compliant assets to prospective shutdown or retrofit costs.
-
Tariff and trade nuances: recent tariff adjustments in major jurisdictions underscore the importance of modeling tariff sensitivity into sourcing strategies — iron oxides were not broadly exempted in the latest revisions, and localized protection can re-route trade flows with little warning.
Strategic Recommendations for Decision-Makers in 2026
Based on our synthesis of demand projections, supplier capabilities and regulatory context, PW Consulting recommends that executives prioritize the following actions this year:
-
Re-run portfolio allocation under three regulatory scenarios (status quo; moderate tightening; aggressive tightening) using stress-tested price and margin inputs. Use these scenarios to rank plants and product lines for capex prioritization.
-
Pursue selective vertical partnerships for battery applications. Pilots with nanopowder producers and LFP OEMs can de-risk market entry while giving R&D insight into grade-performance trade-offs.
-
Accelerate low‑carbon process investments where payback is demonstrable — waste‑heat recovery and emissions reductions not only lower operating cost but materially improve M&A and tender outcomes in sustainability-driven end markets.
-
Introduce supplier diversification and forward contracts for critical iron feedstocks. Multi-sourcing from geographically disaggregated suppliers reduces single‑point risk and strengthens negotiating positions as demand tightens.
-
Embed our supplier scorecards and price-elasticity matrices into commercial negotiations to capture margin on differentiated grades and to defend against commoditization in mature applications.
-
Deploy a focused M&A playbook: prioritize acquisitions that add specialty grades, proprietary process technology, or footprint in logistics-constrained regions, and value them using scenario-adjusted discounted cash flows reflecting raw-material volatility.
How to Use This Preview — And Where to Find the Full Intelligence
This preview demonstrates the strategic utility of our full report: it provides the quantified market trajectory (drawn from the 2020–2025 historical series and extended through 2032), the commercial playbooks and the targeted operational checklists buyers and producers need for 2026 decision cycles. The full report contains the proprietary segmentation matrices, regional and application-level demand splits, price decks, supplier scorecards, and downloadable financial models that we intentionally do not disclose here.
If you are leading procurement, corporate strategy, M&A, or R&D in coatings, construction materials, plastics, or battery materials, the full PW Consulting Worldwide Ferric Oxide Market report will equip your team with:
-
Detailed regional and application-by-type demand breakdowns and sensitivity tables (proprietary data).
-
Transaction-ready valuation templates and playbooks for acquisitions and joint ventures.
-
Implementation roadmaps for decarbonization investments and compliance planning.
-
Technical assessment frameworks for battery-grade and specialty pigment development.
Closing — Convert Forecasts into Competitive Advantage
The ferric oxide market’s headline growth (CAGR 4.12% from the 2025 base) masks important structural shifts: rising technical requirements, evolving regulatory expectations, and the emergence of higher-margin applications. In 2026, the companies that translate market intelligence into prioritized capital allocation, targeted partnerships and resilient supply-chain design will materially outperform. PW Consulting’s full study is calibrated to be a decision-acceleration tool — not just a forecast. For access to the complete segmentation data, financial models and implementation playbooks referenced in this preview, visit our report page and contact our industry practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Ferric Oxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Elbow Splint Market Valued at USD 513.75 Million in 2025, Poised to Reach USD 777.6 Million by 2032 at a 6.1% CAGR
By pmarketresearch, 2026-07-17
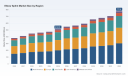
Worldwide Elbow Splint Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As health systems, device manufacturers, and investors position for growth in the upper-limb orthotics space, PW Consulting’s newest market study provides a focused, decision-ready view of the global elbow splint market through a strategic 2026 lens. Our analysis synthesizes five years of historical performance, near-term inflection points and a seven-year forecast, delivering the commercial intelligence leaders need to prioritize product development, reimbursement engagement, and M&A activity ahead of the next procurement and clinical cycles.
Worldwide Elbow Splint Market
Why 2026 Matters: A Market at a Strategic Inflection
The global elbow splint market demonstrated steady expansion between 2020 and 2025, with overall market value rising from a solid base and reaching approximately USD 513.8 million in 2025. PW Consulting’s scenario modelling projects continued expansion at a compound annual growth rate of 6.1% through our forecast window, taking the market to the high hundreds of millions by 2032. That trajectory reflects converging dynamics: aging populations and growing post-operative caseloads, broader clinical adoption of orthotic management for trauma and nerve entrapments, and incremental product innovation in adjustable/dynamic solutions.
Worldwide Elbow Splint Market
For corporate strategists, 2026 is the year to move from passive observation to execution. The market’s predictable growth creates opportunities—but also narrows windows for first-mover advantage in premium segments, and for consolidation plays that can meaningfully shift competitive positioning.
Worldwide Elbow Splint Market
What the Report Delivers: Practical, Transactional Insights
- Robust market sizing and validated forecasts (historical 2020–2025, base year 2025, forecast 2026–2032), including alternative scenarios to stress-test strategy under different reimbursement and regulatory assumptions.
- Actionable segmentation frameworks across product types, clinical applications and geographic groupings, with a focus on where margin pools and unit volume growth are most likely to emerge (note: this brief intentionally omits the granular split tables reserved for the full report).
- Comprehensive reimbursement mapping and coding impact analysis covering recent HCPCS updates and their likely influence on device utilization, pricing elasticity and rental vs. purchase economics.
- Regulatory pathways and risk matrices for major markets, including pragmatic checklists for 510(k) and CE compliance strategies that reduce time-to-market risk for iterative and next-generation devices.
- Commercial playbooks tailored to three go-to-market archetypes—premium-brand manufacturers, contract manufacturers/ODM partners, and value-focused regional suppliers—each with prioritized tactical recommendations for 12–36 month execution cycles.
- M&A and partnership scouting dossiers, highlighting target profiles that offer scale, channel extension or technical differentiation to accelerate growth with defensible margins.
- Supplier and materials outlook, addressing the sourcing risks and cost levers tied to hinges, lightweight composites, moisture-wicking fabrics and modular engineering for dynamic splints.
Competitive Landscape: Who’s Moving the Needle
The market exhibits moderate concentration: the top three players account for roughly a third of global revenues, while the top five approach near-majority share. That balance creates a competitive environment where established OEMs co-exist with specialized niche players and vertically integrated soft-goods suppliers. Our competitive profiles in the report combine product portfolios, channel footprints, innovation trajectories and near-term catalysts.
- Breg, Inc. — A North American leader with a broad portfolio spanning post-operative immobilizers and rehabilitation braces; strength lies in integrated product lines that support continuum-of-care selling to ASCs and hospitals.
- DJO Global / Enovis — Leveraging established DonJoy and Aircast brand equity, Enovis maintains competitive presence across sport-protection and clinical-grade supports; recent global catalogue updates underscore ongoing investment in portfolio refresh and channel enablement.
- Bauerfeind AG — Differentiates around premium, medical-grade compression and orthotic materials with a strong value proposition for pain management and activity-preserving supports in outpatient and retail channels.
- Thuasne USA — Focused on prescription-quality orthoses and PDAC-recognized product lines that facilitate reimbursement pathways for post-operative and chronic care markets.
- Mid-sized and niche suppliers (Corflex Global, Össur, Hely & Weber, Comfy Splints, AliMed, Orthomerica) — These players compete across customization, comfort, and specialized clinical indications; many serve as attractive acquisition candidates for companies seeking route-to-market or product-line expansion.
Reimbursement & Regulatory Developments: Near-Term Game Changers
Two developments deserve immediate attention from commercial teams planning 2026 initiatives. First, coding and reimbursement revisions that came into effect in 2025 change the payment dynamics for dynamic adjustable elbow devices and influence device modality selection by clinicians and durable medical equipment providers. Second, the ongoing need for robust evidence to support claims—especially for dynamic devices marketed for contracture management and post-op rehabilitation—means that clinical and economic dossiers must be strengthened before major payer negotiations.
- HCPCS/Coding shifts — Recent updates introduced device-specific codes for extension-only and flexion-only dynamic devices and adjusted rental/payment categorizations. These updates materially affect the economic calculus for reimbursement-dependent devices and the structuring of rental vs. sale models.
- Regulatory pathways — Most elbow splints and orthoses fall under Class I or II device pathways, requiring 510(k) or equivalent documentation in major markets. Strategic product changes (e.g., motorized or sensor-enabled actuators) will trigger more rigorous regulatory and clinical evidence requirements.
Implications for 2026 Corporate Strategy
PW Consulting’s analysis identifies five priority moves that should be considered by market incumbents and entrants alike when planning budgets and roadmaps for 2026:
- Prioritize reimbursement-first product development. Design features that map cleanly to newly revised codes and payer policies to accelerate adoption and preserve price realization.
- Invest in targeted clinical and health-economic evidence. Short-cycle RCTs and real-world evidence programs that demonstrate reduced reoperation, faster functional recovery, or lower total cost of care create commercial defensibility in procurement conversations.
- Evaluate bolt-on M&A to fill capability gaps. With a moderate level of market concentration, selective acquisitions—especially of customized-fit soft-goods manufacturers or niche dynamic-device innovators—can rapidly improve market access and margin profiles.
- Optimize channel strategy for hybrid distribution. Blended approaches that leverage clinical channels for prescription orthoses and retail/digital channels for consumer-oriented supports will maximize reach without eroding premium pricing for clinically certified devices.
- Hedge supply-chain risk and control material inputs. Sourcing strategies for hinges, padding and breathable textiles will materially influence unit costs and customer-perceived comfort—both critical in provider purchasing decisions.
What We Withhold — And Why You Should Download the Full Report
In line with our “trailer” approach, this briefing surfaces the strategic insights that will shape 2026 decision-making while reserving full, tabulated segmentation (by region, application and product type), granular price-volume matrices, and the proprietary list of prioritized M&A targets for the full report. These granular elements are intentionally controlled to preserve the actionable advantage clients derive from our primary data synthesis and scenario modelling.
Next Steps for Senior Executives
If your 2026 strategic plan includes product launches, pricing revisions, market entry, or M&A, PW Consulting’s full Worldwide Elbow Splint Market report is structured to accelerate execution. The report’s blend of validated market sizing, reimbursement playbooks, regulatory checklists and competitor dossiers turns macro visibility into operational decisions—helping you choose where to invest, where to partner, and which moves to defer.
Contact PW Consulting to request the full report and access our proprietary data tables, scenario models and a confidential briefing tailored to your company’s positioning and growth ambitions in the elbow splint market.
For detailed analysis of this topic, please visit the official page: Worldwide Elbow Splint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Carboprost Tromethamine Market to Reach USD 218.05 Million by 2032 at a 6.78% CAGR — 250 mcg/mL Injection Leading with USD 123.91M
By pmarketresearch, 2026-07-17
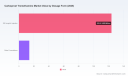
Worldwide Carboprost Tromethamine Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to release an executive synopsis of our latest market research on the Worldwide Carboprost Tromethamine market. Synthesizing five years of historical performance (2020–2025) and a seven-year forecast (2026–2032), the report delivers decision-grade insights and executable strategies for pharmaceutical manufacturers, API suppliers, hospital procurement teams, private equity investors, and specialty CDMOs. Measured in USD Million and anchored to a 2025 base year, the market exhibits a mid-single-digit compound annual growth rate (CAGR) of 6.78% across the forecast window — a rate that masks dynamic pockets of opportunity and episodic volatility that will shape commercial and supply‑chain choices in 2026 and beyond.
Worldwide Carboprost Tromethamine Market
Why this market matters for 2026 strategy
-
Clinical criticality: Carboprost tromethamine remains a clinically essential option for postpartum hemorrhage and second‑trimester abortion management. Its place in acute care pathways means demand is concentrated in institutional settings where product availability directly affects patient outcomes and hospital risk management.
Worldwide Carboprost Tromethamine Market -
Regulatory and reimbursement inflection points: With multiple generic versions AP-rated to the reference listed drug and no substantive US patent barriers remaining, pricing dynamics and formulary placement are now primary battlegrounds. Recent payer behaviours — including case‑by‑case TAR requirements emerging in some US health plans — are already influencing hospital procurement and manufacturer contracting strategies.
Worldwide Carboprost Tromethamine Market -
Supply chain concentration and API specialization: The molecule is manufactured via specialized prostaglandin synthesis routes. API production is concentrated among a narrow set of global producers with regulated filings (USDMF, CEP/COS), which creates both supplier leverage and a strategic runway for entrants that can guarantee validated supply and quality-compliant documentation.
Top‑line market trajectory and implications
Our topline modelling — expressed in USD Million — shows the market continuing to expand from the 2025 base into 2026 and across the forecast period, with intermittent year‑to‑year fluctuations driven by supply disruptions, product launches, and institutional stocking practices. The 6.78% CAGR captures an environment where steady clinical need intersects with episodic competitive shifts (new ANDA approvals and differentiated presentations) and payer dynamics. For corporate strategists, this profile translates into a dual imperative: secure resilient supply and develop differentiated commercial propositions that are defensible in procurement negotiations.
Competitive landscape: what the current players reveal about strategy
-
Originator and branded positioning: The reference listed drug continues to exert influence on clinical adoption and payer perceptions, underlining the value of brand recognition in acute care settings. Branded stewardship remains relevant where institutional protocols and prescriber familiarity matter.
-
Generics and product differentiation: The market has transitioned to multiple FDA‑approved generics (several ANDA approvals across 2019–2024). These competitors pursue volume through institutional channels, tendering, and portfolio bundling. Notably, tactical product differentiation — for example, single‑pack presentations or specialized institutional packaging — has demonstrated commercial value in tender outcomes and procurement convenience.
-
API and CDMO strategic value: API specialists and CDMOs with certified documentation and prostaglandin synthesis expertise are strategic linchpins. Control over validated API supply and localized manufacturing footprint reduces lead time risk and supports regulatory filings. For companies evaluating vertical integration or secure-sourcing agreements in 2026, API partner dossiers and USDMF/CEP status are high‑value due diligence items.
Company profiles: strategic takeaways (non‑exhaustive)
-
Originator profile — Pfizer: As the originator of the reference product, Pfizer’s branded stewardship continues to shape clinical perception and formulary references. For acquirers or licensors, originator legacy offers channel access and an evidence base that can be leveraged in combination strategies.
-
Established generics — Dr. Reddy’s, Amneal, Long Grove, Eugia (Aurobindo), Micro Labs: These firms represent the competitive core in finished dosage supply. Their ANDA approvals and commercial launches over recent years have increased supply diversity and exerted downward pricing pressure in institutional tenders. Tactical differentiation (e.g., single‑pack offerings) has proven a useful lever for negotiating hospital contracts.
-
API specialists — Century Pharmaceuticals, Chirogate, BrightGene, EUROAPI, TIEN: The API base is specialized and geographically concentrated. These suppliers’ regulatory filings and manufacturing certifications are critical enablers for finished dose producers. Strategic partnerships, multi‑sourcing clauses, and long‑term offtake agreements are effective mitigants against supply shocks.
Recent developments shaping near‑term tactics
-
ANDA approvals and launches: The wave of new ANDA approvals and product launches since 2019 has altered procurement dynamics and increased price competition in institutional segments. New entrants are moving quickly to secure hospital formularies and group purchasing agreements.
-
Packaging innovation: Commercial differentiation through packaging (for example, single‑pack presentations) has demonstrable procurement appeal, streamlining pharmacy workflows and reducing dosing errors.
-
Payer behaviour: Emerging TAR requirements in select payers underscore the rising influence of reimbursement policy on product utilization — a factor that sellers must account for in contracting and evidence generation strategies.
What the PW Consulting report delivers — practical, actionable components
-
Granular demand forecasting: High‑resolution topline forecasts by year (2026–2032), scenario analyses that quantify downside risk from supply interruptions, and upside capture from differentiated product launches.
-
Commercial playbooks: Tender and formulary playbooks for institutional sales, contract negotiation templates, pricing sensitivity matrices, and bundling strategies that preserve margin while winning volume.
-
Supply‑chain blueprints: Supplier risk heatmaps, validated supplier shortlists, API qualification checklists (USDMF/CEP status and audit readiness), and recommended multi‑sourcing strategies to secure continuity.
-
Regulatory and reimbursement mapping: Detailed trackers of ANDA approvals, labeling considerations, and payer access constraints (including TAR trends), with recommended evidence and contracting responses to accelerate formulary uptake.
-
M&A and partnership screening: Target scoring for acquisitions, licensing, or CDMO partnerships using a custom valuation framework that weights regulatory filings, manufacturing compliance, and commercial channel access.
-
Risk and contingency planning: Playbooks for rapid response to supply shortfalls, including tactical domestic fill‑rate programs, prioritized allocation frameworks for institutional customers, and communications templates for clinicians and payers.
Strategic recommendations for 2026
-
Prioritize supply resilience now: Secure validated API supply lines and execute at least one alternate‑sourcing contract with an API supplier holding regulated filings. The cost of inaction is measured not only in lost sales but in reputational risk for hospital customers.
-
Invest in differentiated product formats: Even modest investments in packaging or single‑use presentations can materially influence tender outcomes in institutional settings and justify premium pricing in constrained supply environments.
-
Align commercial strategy to payer dynamics: Build a payer intelligence function to monitor TAR adoption and institutional contracting trends. Prepare evidence packages and value dossiers that address payer questions ahead of negotiation windows.
-
Use M&A selectively to accelerate capability: For companies seeking rapid scale or entry, prioritize targets that supply regulated API, own validated manufacturing capacity, or hold strong institutional sales channels.
-
Adopt scenario planning: Incorporate supply disruption scenarios into 2026 budgeting and inventory policies. Maintain a dynamic allocation model that optimizes between contractual obligations and strategic customer retention.
Why PW Consulting’s report is a strategic purchase
The report couples robust quantitative forecasts (anchored to a 2025 base and modelled through 2032) with pragmatic commercial and supply‑chain tools that directly map to 2026 decision calendars. We provide the investment‑grade datasets (time‑series topline values, concentration metrics, and scenario outputs) plus executable playbooks and supplier dossiers — enabling rapid translation from insight to action. In line with our “trailer” approach, this briefing highlights the depth and utility of our analysis while reserving proprietary, line‑level segmentation tables, company share matrices, and contract‑level price curves for report purchasers and subscription clients.
Next steps
For manufacturers, API suppliers, hospital procurement teams, CDMOs, and investors preparing 2026 plans, PW Consulting’s full report delivers the datasets and operational playbooks required to de‑risk execution and identify value capture. To gain full access to the detailed segmentation, competitive share tables, and supplier dossiers referenced here, please contact PW Consulting or visit our report landing page to request the complete Worldwide Carboprost Tromethamine Market report and associated advisory packages.
For detailed analysis of this topic, please visit the official page: Worldwide Carboprost Tromethamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Stainless Steel Fermenter Market to Reach USD 3,323.14 Million by 2032, Expanding at a 6.45% CAGR
By pmarketresearch, 2026-07-17
Worldwide Stainless Steel Fermenter Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on the Worldwide Stainless Steel Fermenter Market (base year 2025) is designed as a decision‑grade briefing for executives, procurement leads and M&A teams preparing strategy for 2026. The market has grown from roughly USD 1,560 million in 2020 to USD 2,145.5 million in 2025 and our forecast shows continued momentum — an expected rise to USD 2,381.9 million in 2026 and to USD 3,323.1 million by 2032, implying a compound annual growth rate (CAGR) of 6.45% over the 2026–2032 forecast window. This briefing distills where the value pools are forming, what operational and regulatory forces will determine winners, and which tactical levers should be prioritized this year.
Worldwide Stainless Steel Fermenter Market
Market trajectory and implication for 2026 planning
The current market trajectory combines steady organic growth in established end‑markets with punctuated investment driven by biopharma capacity expansions and industrial fermentation projects. After accelerating through 2024–2025, the sector is entering a phase where regulatory compliance, raw‑material inflation and supply‑chain sovereign risk will materially influence supplier selection, capex timing and procurement strategies. Put simply: 2026 will be the year many buyers transition from cost‑first procurements to value‑risk balanced decisions that explicitly factor standards, lifecycle costs, and service footprints.
Worldwide Stainless Steel Fermenter Market
What PW Consulting’s report delivers — the practitioner’s toolkit
- Proprietary market model: an integrated top‑down and bottom‑up model reconciling historical shipments and revenue (2020–2025) with scenario forecasts through 2032. The model is designed for rapid sensitivity testing (e.g., nickel price shocks, tariff changes, regulatory compliance costs).
- Decision frameworks: target operating models for OEMs, IDPs and end‑users — including CapEx prioritization matrices and payback analyses for retrofit vs greenfield options.
- Procurement playbooks: supplier shortlists, negotiation anchors, standard contract clauses for warranty and spare‑parts logistics, and a scoring template to compare total cost of ownership (TCO) across multiple build‑and‑buy scenarios.
- Regulatory impact module: quantified cost and time implications of recent standards updates on material, finishing and testing requirements for sterile and non‑sterile fermenters.
- Competitive benchmarking: vendor scoring across technical fit, compliance credentials, engineering throughput and after‑sales service capability (confidential scorecards included).
- Actionable deliverables: ROI calculators, manufacturing footprint optimization maps, 24–36 month supplier risk heatmaps and a playbook for rapid compliance upgrades.
Competitive landscape — who matters and why
The market shows moderate concentration: the top three suppliers account for roughly one‑third of revenue while the top five approach half of the market — a structure that rewards both niche specialization and scale. Our competitive review synthesizes product positioning, geographic strengths and strategic moves from established players and strong regional suppliers.
Worldwide Stainless Steel Fermenter Market
- ABEC (USA): Specialist in custom stainless‑steel fermenters with large capacity capability (up to 100,000 L). Their recent ASME certification for a high‑pressure fermenter line (Nov 2024) signals a deliberate move into higher‑value, regulated applications where certification shortens customer‑onboarding time. For 2026, ABEC’s play is to convert regulatory compliance into faster time‑to‑revenue for industrial and biofuel customers.
- Applikon Biotechnology (Getinge, Netherlands): Strong in lab‑to‑production scale continuity — a go‑to for customers needing seamless scale‑up. Their positioning favors biotech firms seeking reproducible scale pathways and supplier continuity across R&D and production.
- Biotech GmbH (Germany): Known for SIP/CIP enabled systems for microbial and cell culture applications. Their engineering focus aligns well with manufacturers prioritizing sterility and automated cleaning regimes.
- Eppendorf (Germany): Supplier of smaller production fermenters (e.g., BioBLU series) with tight integration into bioprocess workflows. Their strength is in turnkey adoptability for production suites up to mid‑scale.
- GEA Group (Germany): Traditional strength in large‑scale fermenter design and a recent capacity expansion (Italian facility, Mar 2025) points to aggressive pursuit of biopharma volume orders. GEA is positioning for tier‑one supply to major food and pharma integrators.
- Sartorius (Germany): Focus on upstream bioprocessing with a strategic emphasis on sensor integration. Their 2025 launch of upgraded stainless systems featuring enhanced single‑use sensor integration (Jun 2025) highlights the convergence of stainless steel robustness with single‑use analytics — an important hybrid trend.
- Vinci Technologies (France): Specialist in both aerobic and anaerobic fermenters for research and industry; often selected for niche process needs requiring experienced engineering customization.
- Zhengzhou Keda Machinery (China): Competitive cost position for beer, bioethanol and pharma fermentation. Their presence should be considered in any sourcing diversification or low‑cost manufacturing scenario, with tariff exposure (see dynamics) part of the commercial calculus.
Regulatory, raw‑material and trade dynamics shaping 2026
- Surface‑finish and sterile process standards: The EU GMP Annex 1 update effective August 2025 raised surface finish expectations for sterile bioprocessing (target Ra < 0.5 μm). This has immediate implications for fabrication methods, passivation and validation cycles for stainless fermenters destined for sterile pharma production.
- Pressure vessel testing requirements: ASME BPVC Section VIII Division 1 updates in 2025 require pressure vessel testing for stainless fermenters above specified volumes. Buyers should expect longer validation windows and elevated factory testing costs for larger vessels.
- Raw‑material inflation: Nickel — a key alloy element for 304/316L stainless steels — rose roughly 15% to around USD 18,500/tonne in Q1 2026 due to supply constraints; chromium prices increased ~12% amid production disruptions. These moves feed directly into BOM inflation and will pressure smaller OEM margins unless hedging or surcharge mechanisms are deployed.
- Trade policy: U.S. Section 232 tariffs on stainless steel imports from China rose to 25% in Feb 2026. Buyers sourcing components internationally need to reassess landed cost assumptions and near‑term supplier risk, especially for heavy or custom components where domestic sourcing is limited.
Strategic playbook for 2026 — tactical moves that preserve value
- Re‑price and renegotiate with transparency: Implement dual‑track contracts that decouple raw‑material surcharges and exchange‑rate clauses from base equipment prices. Our report includes clause language and benchmarking data for negotiation.
- Prioritize compliance‑ready suppliers: For projects targeting sterile biotech customers, prefer suppliers with demonstrable EU GMP Annex 1 and ASME testing compliance; the up‑front premium pays back in faster validation and reduced rework.
- Hedge critical commodities: Consider structured hedges for nickel and chromium exposures or long‑lead time purchasing commitments to stabilize BOM costs for multi‑year projects.
- Localize critical supply elements: Where tariffs or logistics risk raise landed costs, evaluate partial localization — for example, retaining specialist heads and instrumentation from global suppliers while sourcing tanks and piping domestically.
- Invest in hybrid sensor strategies: The market is moving toward hybrid stainless/advanced sensor ecosystems; allocating 1–2% of project capex to integrated process analytics can reduce batch variability and lower downstream validation costs.
- Use M&A selectively: Small bolt‑on acquisitions that bring certifications, local approvals, or after‑sales networks can compress time‑to‑market in regulated geographies.
How to use this report in board and procurement forums
Executives should treat the report as both an intelligence asset and an execution manual. For boards, the executive summary provides the risk‑reward view and capsulized scenario outcomes needed for capital allocation debates. For procurement and engineering teams, the TCO models, compliance checklists and supplier scorecards translate strategy into a prioritized project pipeline. PW Consulting’s modular deliverables let teams plug quantitative results directly into capex approval templates and 12–24 month sourcing plans.
Next steps and where to find the full datasets
This briefing intentionally surfaces the strategic implications and high‑impact levers while withholding the granular segmentation tables and vendor scorecards that form the core of the report’s proprietary value. Clients and subscribers who require the full breakdown — including our supplier scoring matrices, region/application segmentations, and downloadable scenario model — can access the complete report and supporting Excel model via the official report page or by contacting PW Consulting for a tailored briefing session. For transaction teams, we also offer an expedited diligence package that includes factory‑level compliance verification and price‑benchmarked cost build‑ups.
In a market growing at a mid‑single digit CAGR but facing concentrated regulatory and commodity shocks, 2026 will be the year that separates opportunistic buyers from strategic winners. Our study equips management teams with the market intelligence and operational tools to make those distinctions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Fermenter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Refsum Disease Treatment Market Set to Expand at 5.41% CAGR, New Report Reveals
By pmarketresearch, 2026-07-17
Worldwide Refsum Disease Treatment Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on the Worldwide Refsum Disease Treatment Market (base year 2025; forecast 2026–2032) synthesizes epidemiology, service delivery economics, reimbursement patterns, and competitive positioning into a single actionable briefing for executives planning investments and partnerships in 2026. The market has expanded from an estimated USD 173.2 million in 2020 to roughly USD 224.2 million in 2025, and PW projects continuation of steady growth through 2032 (reaching an estimated USD 324.0 million) at a compound annual growth rate of approximately 5.41% (USD, Million). This preview distills the strategic implications of those top-line dynamics without publishing the granular splits and proprietary models reserved for the full report.
Worldwide Refsum Disease Treatment Market
Why this matters for 2026 strategic planning
-
Orphan-disease investments need a different calculus: modest absolute market scale, but structurally defensible demand and high lifetime value per patient. Our modelling shows a steady top-line expansion driven by better diagnosis rates, standardized long-term care pathways, and wider adoption of specialized removal therapies.
Worldwide Refsum Disease Treatment Market -
2026 is a pivotal decision year: reimbursement frameworks and clinical practice patterns that crystallize in 2025–2026 will determine which commercialization routes (devices/service delivery vs. pharmacologic R&D vs. diagnostics and RWE programs) produce differentiated returns over the next 6–7 years.
Worldwide Refsum Disease Treatment Market -
Competitive concentration is moderate: the sector is neither a fragmented local market nor a tightly monopolized one. PW’s concentration metrics indicate meaningful incumbent advantages in core channels but also clear white-space for new entrants with complementary assets or superior go-to-market strategies.
Market trajectory and what the headline numbers hide
The global treatment market for Refsum disease has displayed resilience through recent years. After incremental year‑on‑year growth from 2020 through 2022, we observed a small plateau in 2023 followed by a rebound in 2024–2025 that reflects improved diagnostic throughput and the normalization of elective service delivery in specialized centers. The forecast to 2032 assumes a sustained CAGR near 5.4%, resulting in a market that is materially larger in nominal terms by the end of the decade.
Importantly, those headline totals do not reveal the differential economics across therapeutic approaches, care settings, or geographic reimbursement regimes — all of which are core components of the full report. In other words, while the aggregate opportunity is modest relative to many rare-disease markets, the long-duration treatment model and recurring service revenue create attractive unit economics for targeted strategies.
Key growth drivers and constraints
-
Diagnostics and recognition: Improved genetic testing access and clinician awareness are increasing the diagnosed prevalence pool; early diagnosis materially improves lifetime care pathways and drives demand for both acute and maintenance interventions.
-
Service-centered treatment model: The therapeutic paradigm today relies on lifelong dietary management complemented by extracorporeal phytanic acid reduction for eligible patients. That creates durable demand across a small but steady patient base.
-
Reimbursement tailwinds coupled with regulatory gaps: Orphan‑disease reimbursement protocols in major markets often cover specialized removal therapies, creating payer acceptance for certain high‑cost procedures. At the same time, the absence of any FDA‑approved pharmacologic agents for Refsum disease leaves an open pathway for therapeutic innovation — but also raises execution risk for companies pursuing drug development.
-
Operational and logistical constraints: Delivery of extracorporeal therapies depends on concentrated capacity in specialized clinics and trained staff; scaling requires careful planning across supply chain, workforce, and payer contracting.
Dynamics: regulatory, reimbursement and clinical practice (evidence-backed)
-
Regulatory landscape: There are currently no pharmacologic agents with specific FDA approval for Refsum disease; lifelong dietary restriction of phytanic acid precursors remains the clinical standard (NIH Genetic and Rare Diseases Information Center, Oct 2022).
-
Reimbursement realities: Plasmapheresis and other extracorporeal approaches used to reduce phytanic acid are commonly reimbursed under orphan-disease protocols in major markets for eligible patients—this provides a commercial pathway for service providers and device firms (National Organization for Rare Disorders, Mar 2023).
-
Drug development context: There are no dedicated, commercially approved drugs; some experimental or off‑label agents (for example, fibrates) have been used in investigational settings, but remain outside routine practice (Orphanet, Jan 2024).
Competitive landscape — what incumbents and new entrants should know
PW’s analysis frames competition not just as a list of corporate names but as an ecosystem of capability clusters: specialty clinics and hospital networks delivering apheresis services; diagnostic laboratories providing genetic confirmation and monitoring; manufacturers of extracorporeal equipment and disposables; nutritional supplement and medical food providers; and a small but growing cohort of biotechs exploring pharmacologic approaches. Market concentration metrics signal that the top few players capture a meaningful share of current revenue, but the majority of the market remains accessible through differentiated clinical networks, superior outcomes data, or focused reimbursement strategies.
For investors and corporate strategists, the key practical takeaway is capability adjacency. Firms that can combine diagnostics, durable real‑world evidence programs, and payer-focused value dossiers will outcompete those that rely solely on product sales. PW’s full report maps probable M&A targets by capability—diagnostic labs with centralized sample flows, regional apheresis centers with payer contracts, and device suppliers with compatible disposables—enabling pragmatic portfolio design for 2026 executions.
Strategic options and tactical playbook for 2026
-
Pharma/Biotech (R&D focus): Prioritize small‑population trial designs, accelerated regulatory pathways, and early payer engagement. Because no agents are specifically approved today, a successful pharmacologic candidate would address a high unmet need — but must be paired with RWE programs that demonstrate long‑term benefits vs. standard-of-care dietary and extracorporeal approaches.
-
Device and service providers: Invest in hub-and-spoke models that extend extracorporeal therapy capacity through partnerships with regional clinics and telehealth-enabled monitoring. Negotiate bundled reimbursement for acute removal + follow-up care to secure predictable revenue streams.
-
Diagnostics and labs: Focus on rapid confirmatory testing and longitudinal monitoring that enable earlier initiation of structured care pathways. Differentiation through speed, integrated reporting, and payer-accepted validation will lift conversion rates from diagnosis to treatment.
-
Payers and health systems: Expect to see proposals for shared-savings programs tied to adherence to dietary management and minimized acute admissions. Investment in patient education and coordination reduces long-term cost and should be implemented in 2026 pilot programs.
What PW Consulting’s full report delivers (practical, transaction-ready content)
-
Proprietary market model (2020–2032) with scenario analysis and sensitivity to diagnosis rates, uptake of extracorporeal therapies, and potential introduction of pharmacologic agents.
-
Reimbursement playbook by major jurisdiction and payer archetype (practical contracting language, billing codes, and utilization benchmarks).
-
Commercialization blueprints — go‑to‑market for devices, services, diagnostics and small‑molecule/biologic candidates, including pricing and channel strategies.
-
Partner and acquisition screening: prioritized target lists with valuation overlays and integration risk profiles.
-
Real-world evidence and HEOR templates that align clinical endpoints with payer value drivers.
Risk matrix and mitigation priorities
Key risks include uncertain therapeutic innovation timelines, concentrated delivery capacity for extracorporeal therapies, and variability in national orphan-disease reimbursement policies. PW recommends a multi-layered mitigation approach for 2026: (1) dual-track investments that preserve optionality between services and drug development, (2) staged geographic expansion tied to local payer pilots, and (3) accelerated RWE initiatives to lock in cost-effectiveness narratives.
How to use this intelligence in your 2026 planning cycle
-
Board-level strategy: Use the market model’s scenarios to stress-test capital allocation decisions and M&A prioritization through 2032.
-
Business development: Leverage PW’s partner-screening frameworks to fast-track 100‑day integration plans for acquisition targets in diagnostics and service networks.
-
Commercial teams: Apply the reimbursement playbook in payer negotiations and to structure outcome‑based agreements that reflect the long‑term nature of Refsum care.
-
R&D and clinical: Design Phase II/III strategies with early payer engagement and pragmatic endpoints that payers will accept as proxies for long-term benefit.
Frequently asked practical questions (short answers)
-
Are there approved drugs for Refsum disease? No — current clinical management centers on lifelong dietary restriction and, where indicated, extracorporeal phytanic acid removal. (NIH Genetic and Rare Diseases Information Center, Oct 2022)
-
Is plasmapheresis reimbursed? Yes — in key markets, plasmapheresis for phytanic acid removal is commonly covered under orphan-disease protocols for eligible patients, creating an established reimbursement route for service providers. (National Organization for Rare Disorders, Mar 2023)
-
Are off‑label drugs a realistic near‑term substitute? Experimental use of agents such as fibrates has been reported but remains investigational and outside standard practice; they do not replace diet and apheresis at present. (Orphanet, Jan 2024)
Closing — the strategic inflection in 2026
For 2026, firms that treat the Refsum disease market as a predictable, service‑driven ecosystem—rather than a conventional product market—will outperform. The top-line growth through 2032 offers an attractive, low‑volatility platform for companies that combine clinical capability, payer engagement, and disciplined RWE generation. PW’s full report provides the granular segmentation, pricing models, payer dossiers, and partner maps that translate the broad numbers into executable playbooks. We have intentionally withheld detailed regional and therapy-type breakdowns in this public preview; those elements are essential tactical inputs for execution and are available in the purchased report.
To access the full dataset, scenario models, and transaction-ready recommendations for the Worldwide Refsum Disease Treatment Market, please visit our report page or contact PW Consulting’s rare-disease practice for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Refsum Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Super Applications Market Poised for 20.04% CAGR, Set to Reach USD 662.89 Billion by 2032
By pmarketresearch, 2026-07-17
Super Applications Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive summary
As enterprises plan their 2026 priorities, the Super Applications Market will be a central battleground for customer engagement, platform-led monetization, and embedded financial services. Our new Super Applications Market report — based on a 2025 technical baseline and a seven-year forecast horizon (2026–2032) — shows a market expanding from USD 185.0 Billion in 2025 to an expected USD 662.9 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 20.04%. This growth creates outsized opportunities for incumbent digital platforms, challenger fintechs, telecoms, and enterprise technology suppliers, but it also concentrates strategic risk around regulation, data residency, and compute cost structures.
Super Applications Market
Why 2026 is an inflection year for enterprise decision-makers
Two converging dynamics make 2026 a decision point for product, investment, and partnership roadmaps. First, market momentum: the super app category is scaling rapidly and predictably; year-on-year expansion is already visible into 2026 and beyond. Second, policy and infrastructure shocks: the regulatory landscape and energy/compute economics are crystallizing obligations that materially change operating models for cross-border platforms and the vendors that support them.
Super Applications Market
-
Accelerated adoption. A ~20% CAGR signals not only density in user engagement but also mounting expectations for platform interoperability, embedded payments, and contextual services that enterprises must meet or risk erosion of customer share.
Super Applications Market -
Regulatory inflection. With major regulatory milestones taking effect in 2026—most notably AI governance frameworks and expanding privacy and data localization obligations—business models premised on unfettered personalization and cross-border data flows will need redesigns.
-
Cost and reliability constraints. Increasing attention to data center grid allocations and compute cost pass-throughs requires firms to reassess cloud architecture, edge strategies, and total cost of ownership for AI-enabled features.
Competitive landscape: platform leadership and tactical moves to watch
The competitive map remains dominated by a relatively small set of multi-service platforms, with market concentration indicators showing the top three and five players controlling a significant portion of market activity. This concentration presents both partner opportunities and competitive pressures for enterprises evaluating alliances or distribution strategies.
-
Tencent Holdings Ltd. continues to fortify its mini-program and payments ecosystem, deepening integration across messaging, commerce, and government services. Enterprises looking to access high-frequency consumer touchpoints should assess Tencent’s ecosystem rules and technical integration paths early in project planning cycles.
-
Ant Group’s Alipay-focused assets remain a model for payment-led platform monetization, particularly where financial services are used as customer acquisition and retention levers. Its playbook demonstrates how embedded finance can turbocharge transaction volumes without proportional increases in marketing spend.
-
Grab Holdings has accelerated a platform-to-financial-services transformation through a mix of product innovation and M&A. Recent acquisitions and an extensive AI experience launch position Grab as an archetype for regional expansion executed via capability-build plus selective asset buys—an important model for enterprises that prefer inorganic pathways to new markets.
-
Regional champions such as GoTo (Gojek), Paytm, Kakao, Revolut, Rappi, and Tata Neu illustrate diverse strategic archetypes—from mobility-led ecosystems to conglomerate-backed, retailer-integrated super apps. Studying each reveals repeatable design patterns for service bundling, regulatory mitigation, and monetization routing.
Recent corporate moves that reshape strategic choices
2025–2026 company actions illustrate practical templates for growth and risk management that advanced teams should study:
-
Grab’s product launches and acquisitions in 2026 show how product diversification (AI-enabled experiences) and targeted geographic expansion can be sequenced to deliver scale while maintaining local relevance.
-
Tencent’s ongoing enhancement of its mini-program ecosystem highlights the role of platform openness versus control. Enterprises must decide whether to pursue deep native integrations (higher control, higher lock-in) or to adopt a lighter, cross-platform approach.
-
Partnerships such as Rappi’s wallet integrations underscore an emerging playbook for currency and payment interoperability—especially important for enterprises operating across borders or in multi-currency trade corridors.
Regulation, data sovereignty and infrastructure: risk becomes a strategic variable in 2026
Enterprise architects and legal teams must treat regulatory and infrastructure constraints as design parameters, not afterthoughts. Four practical implications arise from the regulatory and infrastructure environment:
-
AI governance is now operational: with advanced AI legislation reaching implementation, personalization engines and automated decisioning modules will require explainability, impact assessments, and potentially constrained model behaviors. Product roadmaps must allocate budget and time for compliance engineering and auditability.
-
Data localization is mainstream: an expanding set of jurisdictions now demand in-country processing or storage, affecting cloud footprints and dataflow designs. Firms should re-evaluate vendor SLAs, encryption regimes, and cross-border transfer mechanisms.
-
Privacy fragmentation increases integration friction: U.S. state-level privacy laws and global privacy standards fragment consent and handling requirements; enterprises must modularize consent management and invest in robust privacy orchestration layers.
-
Compute and grid economics matter: as data centers draw policy scrutiny, the long-term unit economics of AI features will be a competitive battleground. Organizations should consider hybrid edge-cloud architectures and consumption-based procurement to retain flexibility.
Strategic implications for enterprise leaders in 2026
For C-suite and product leaders, the report distills practical choices into three priority tracks that should guide investment allocations and partnership decisions this year:
-
Platform-based distribution vs. owned channels: Evaluate where to prioritize native integrations with dominant super apps and where to double down on proprietary channels. Successful firms will adopt a portfolio approach—striking a balance between reach through partners and control over critical customer journeys.
-
Embedded finance and modular monetization: Evaluate how payments, lending, insurance, and savings can be embedded into your product to boost lifetime value. The right modular architecture for financial services can open incremental revenue while preserving compliance boundaries.
-
Compliance-by-design and cost-conscious AI: Technical roadmaps must bake in regulatory requirements alongside cloud cost controls. Delivering differentiated AI experiences at scale requires a disciplined stack that separates inference from training, optimizes model size, and leverages localized compute to limit data movement.
What the PW Consulting Super Applications Market report delivers (practical contents)
Our report is built to be immediately actionable for teams planning 2026 initiatives. Highlights include:
-
Market trajectory and scenario modelling: robust baseline and three alternative scenarios through 2032 that quantify strategic sensitivities to regulation, monetization models, and platform openness.
-
Decision-ready vendor and M&A playbooks: criteria matrices for partnership selection, diligence checklists for acquisitions of localized assets, and integration roadmaps that minimize churn and regulatory exposure.
-
Commercial models and pricing frameworks: practical templates for revenue-sharing, merchant fee structures, embedded finance economics, and break-even analysis tailored for super app distribution.
-
Technology architecture blueprints: reference architectures for hybrid deployment, consent orchestration, and cost-optimized AI delivery, including procurement considerations for cloud, edge, and colo providers.
-
Regulatory readiness toolkits: compliance playbooks aligned to the latest 2026 legislation and jurisdictional requirements, plus a gap-assessment workbook to prioritize remediation efforts.
-
Executive dashboards and KPIs: recommended measurement frameworks to track user engagement, monetization efficiency, and regulatory posture without exposing sensitive segment-level inputs in this summary.
How enterprises should use this intelligence in 2026
We recommend a three-step program to convert market intelligence into defensible advantage in 2026:
-
Immediate triage (0–3 months): map your current exposures to dominant super app platforms, data residency rules, and compute cost vectors. Use the report’s gap-assessment to prioritize fast wins.
-
Capability build (3–12 months): implement modular payments/identity stacks, deploy privacy orchestration, and pilot lightweight AI experiences optimized for cost and compliance.
-
Scale and defend (12–36 months): execute partnership or M&A plays to secure distribution, harden compliance processes for ongoing regulation, and adopt hybrid infrastructure to control long-term economics of platform features.
Why this report matters to boardrooms and strategy teams
The Super Applications Market is not just a consumer-facing phenomenon; it alters the economics of customer acquisition, the architecture of digital services, and the policy perimeter enterprises must navigate. With a projected rise to roughly USD 662.9 Billion by 2032 and sustained ~20% annual growth, the category will determine whether firms win at scale or become marginal channel partners.
PW Consulting’s analysis blends quantitative forecasting with playbooks grounded in recent market moves—illustrated by notable 2025–2026 developments among platform leaders—and prescriptive guidance for mitigating regulatory and infrastructure risks. The report delivers strategic clarity while preserving confidential segment-level forecasts and proprietary benchmarks for subscribers.
Next steps
For senior leaders preparing budgets, partnership strategies, or platform roadmaps in 2026, this report is designed to be the practical north star. To access the full dataset, granular segmentation analysis, and downloadable implementation tools referenced here, please visit our Super Applications Market report landing page for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Super Applications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Composite Slate Roofing Market to Expand at a 6.4% CAGR in 2026–2032 Outlook
By pmarketresearch, 2026-07-17
Worldwide Composite Slate Roofing Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest market study on the worldwide composite slate roofing market synthesizes five years of historical performance (2020–2025) and delivers a seven‑year forecast (2026–2032) designed to inform executive decisions in 2026. The sector expanded from roughly USD 1.12 billion in 2020 to USD 1.54 billion in 2025 and, under our base forecast, is positioned to reach nearly USD 2.38 billion by 2032 — implying a steady mid-single‑digit trajectory consistent with a 6.4% CAGR across the forecast window. This report is built for boardrooms, corporate strategy teams, private equity sponsors, and infrastructure investors who must convert climate risk, regulatory compliance, and raw‑material volatility into strategic advantage without losing operational agility.
Worldwide Composite Slate Roofing Market
Why 2026 is a pivotal year for corporate strategy
-
Convergence of macro drivers — climate extremes, underwriting dynamics, and labor constraints — is compressing decision windows for roofing OEMs, distributors, and installers. Insurers and homeowners are increasingly favoring impact‑resistant coverings, creating differentiated demand pockets that reward certified products and documented out‑performance.
Worldwide Composite Slate Roofing Market -
Raw material and input price volatility is now a strategic variable, not just an operational one. For example, polypropylene resin — a key feedstock for polymer composites — experienced an 8% year‑over‑year rise to roughly USD 1,050 per metric ton in early 2025 amid feedstock constraints. That movement materially influences product cost ladders, margin planning, and hedging strategies for 2026 procurement cycles.
Worldwide Composite Slate Roofing Market -
Contractor availability and installation economics are reshaping routing and go‑to‑market models. Reported skilled labor shortages have accelerated adoption of lighter composite systems that can reduce installation time by 20–30%, but they also raise the bar for supplier‑led training, warranty enforcement, and quality assurance programs.
Key market dynamics and implications
-
Demand drivers: Rising frequency of severe hail and wind events has increased appetite for Class 4 impact‑rated products; our field and insurer interviews indicate material growth in regions where regulatory or underwriting incentives exist. Several U.S. insurers currently provide premium discounts for homes that install Class 4 impact‑rated composite slate systems, creating a measurable ROI story that accelerates homeowner replacement cycles.
-
Regulatory and standards environment: Compliance with polymer‑specific standards (e.g., ASTM D7053 and related classifications) is now a gating factor for large commercial projects and for inclusion on insurer preferred‑vendor lists. Certification timelines and lab pipeline capacity therefore represent a potential bottleneck for new product introductions.
-
Supply‑side dynamics: The interplay of resin pricing, recycled content premiums, and logistics costs is driving a two‑track supplier response: (1) product premiumization — higher warranties, impact and wind certifications, and broader color/texture ranges; and (2) cost optimization — vertical integration of feedstock, longer term multi‑year resin contracts, and localized compounding/repurposing of recycled streams.
-
Competitive structure: The market exhibits modest concentration. The top three participants account for a meaningful share of industry revenue, and the top five consolidate a little more than half of the market — a structure that permits scale players to set commercial standards while leaving structural space for niche innovators and regional specialists.
What the PW Consulting report delivers — practical, actionable modules
Our report is intentionally operational. It combines large‑sample primary research, granular price‑and‑cost modeling, and scenario planning so that executives can move from insight to action. Key components include:
- Bottom‑up market sizing and growth modeling for 2020–2032 (base year: 2025), including sensitivity tests to raw material price swings and accelerated climate scenarios.
- Segmentation frameworks across region, material type, and application with interactive dashboards. (Note: segment‑level revenue and share details are available in the full report.)
- Competitive heat maps and capability matrices that evaluate product attributes (impact, wind, fire rating, warranty, recycled content) and go‑to‑market footprints.
- Supplier and contractor ecosystem maps that identify high‑leverage partnerships, training needs, and channel gaps.
- Transaction and valuation playbooks tailored to M&A and minority investment deliberations — including a checklist for technical, commercial, and regulatory due diligence that matters most to acquirers in 2026.
- Implementation guides for three strategic archetypes: scale consolidation, premium product leadership, and asset‑light channel acceleration.
Competitive landscape — profiles and strategic takeaways
The landscape blends legacy roofing players expanding into composites with dedicated composite specialists. Leading names in the sector are pursuing different, but complementary, strategic plays:
-
DaVinci Roofscapes (Kansas City, KS) — focuses on premium polymer composite slate with differentiated sizing options and long warranties, leveraging trade‑show visibility to maintain brand premium and spec adoption among architects and high‑end resi contractors. Recent trade show activity underscores a go‑to‑market emphasis on color and aesthetic differentiation.
-
Brava Roof Tile (Morgan Hill, CA) — positions around high wind ratings and recyclable content, signaling an appeal to sustainability‑minded developers and retrofit programs that target coastal and high‑wind zones.
-
Euroshield (Reno, NV) — leverages recycled rubber chemistry to emphasize severe‑weather durability and algae resistance, a proposition that resonates in high‑maintenance climates.
-
CeDUR (West Jordan, UT) — driving market access through approvals, including high‑velocity hurricane zone certification updates, which materially lower friction for adoption in regulated storm zones.
-
Metro Roof Products (Calhan, CO) and GAF (Parsippany, NJ) — represent two complementary strategies: Metro as a niche product innovator for specified performance bands, and GAF as an incumbent leveraging integrated system sales and distribution reach.
Strategic takeaway: incumbents with distribution scale and system integration capabilities can defend volume and channel access, while agile product‑centric players can capture margin through certification, recyclability, and installation efficiency. This dynamic creates attractive targets for bolt‑on acquisitions that deliver either channel reach or differentiated IP.
Strategic playbook for 2026
-
Cost management and procurement: Lock in multi‑year resin contracts or pursue strategic JV’s with compounders to stabilize input costs. Evaluate partial vertical integration for recyclate streams where available.
-
Certification and insurer engagement: Prioritize ASTM and regional approvals tied to insurer incentives. Creating documented case studies that quantify insurance premium savings for homeowners materially shortens sales cycles in residential retrofit markets.
-
Channel and contractor strategy: Invest in contractor certification programs and modular installation kits to reduce skilled‑labor dependency. Explore “installer as a service” pilots to secure quality control and warranty economics.
-
Product and portfolio choices: Balance premium aesthetic SKUs with streamlined, lower‑cost ranges targeted at insurance‑driven replacements. Use color and texture differentiation as an upsell lever to offset raw material inflation.
-
M&A and partnerships: Look for targets that either plug distribution gaps in key geographies or add technical differentiation (e.g., recycled rubber chemistry, polymer compounding, or patented attachment systems).
Methodology and data integrity
The study synthesizes primary interviews with suppliers, distributors, and insurers, combined with a bottom‑up revenue model cross‑checked against trade data and public filings. We apply a three‑scenario approach (base, upside, downside) to stress test the impact of input‑cost shocks, regulatory tightening, and accelerated climate‑driven replacement cycles. All technical spec references are aligned with prevailing standards such as ASTM D7053 and recognized certification pathways. The base year for all benchmarking is 2025; historical trend analysis covers 2020–2025 and forecasting spans 2026–2032 under a 6.4% CAGR assumption in the base case.
How to use the report in 2026 decision-making
-
Capital allocation: Use our ROI matrices to prioritize capacity expansion versus NPD investments based on local insurer economics and certification lead times.
-
Commercial planning: Align product launches with insurer rebate programs and contractor training rollouts to maximize early adoption.
-
Risk management: Implement hedging or supplier diversification for polymer feedstocks and prepare alternate supply plans for recycled inputs.
-
M&A and partnerships: Leverage our target‑screening criteria and valuation compressions to identify accretive acquisitions that offer immediate channel or technical synergies.
Trailer: what we hold back — and why you’ll want the full dossier
To preserve commercial sensitivity and to encourage direct engagement, this release highlights macro market sizing, growth trajectory, and the strategic playbook while intentionally withholding detailed segment‑level revenue splits and region/application share tables. The full report contains interactive segment dashboards, granular regional forecasts, and supplier‑level revenue estimates that are essential for valuation work and market‑entry modelling. If you are preparing capex requests, M&A diligence memos, or 2026 GTM plans, those tables materially reduce execution risk and accelerate decision timelines.
Next steps
For access to the full dataset, interactive dashboards, and a tailored briefing with our senior analysts, visit the PW Consulting Worldwide Composite Slate Roofing Market project page. Our analysts are available to run bespoke scenario models that align the report findings with your specific balance sheet, product portfolio, and distribution footprint — enabling you to convert market momentum into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Slate Roofing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com