

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ferric Oxide Market at USD 2,400.8 Million in 2025, Poised to Reach USD 3,184.8M by 2032 at 4.12% CAGR — Asia Pacific, Synthetic Oxides Lead

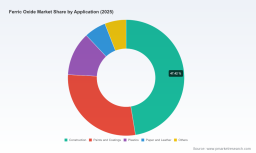
Worldwide Ferric Oxide Market — Strategic Imperatives for 2026: A PW Consulting Preview
PW Consulting today publishes an executive preview of our forthcoming Worldwide Ferric Oxide Market study — a practitioner-focused intelligence product built to arm corporate leaders with the decision frameworks they need in 2026. Anchored in a rigorous historical base (2020–2025) and a detailed forecast horizon (2026–2032), the analysis demonstrates why ferric oxide is no longer a simple pigment commodity but a strategically important material across construction, coatings, plastics and emerging battery applications. Our model shows the global ferric oxide market expanding at a compound annual growth rate (CAGR) of 4.12% from the 2025 base year (2025 market size: USD 2,400.76 Million) through 2032 (2032 projection: USD 3,184.84 Million). This preview outlines why those headline numbers matter — and how leading firms should convert insight into action in 2026.
Worldwide Ferric Oxide Market
Why 2026 Is a Strategic Pivot
-
Demand quality is shifting. Mature demand in construction and paints remains volume-driven, but premiumization — higher-performance pigments with UV resistance, thermal stability and tailored surface chemistry — is accelerating. A growing slice of ferric oxide demand is being redefined by functional requirements rather than color alone.
Worldwide Ferric Oxide Market -
Battery material opportunities are real and material. Recent product and partnership announcements show major pigment manufacturers positioning ferric oxide variants for lithium-iron-phosphate (LFP) cathodes and other specialty battery uses. These moves change margin profiles and capital allocation priorities for producers that choose to compete in this adjacent space.
Worldwide Ferric Oxide Market -
Regulation and upstream volatility are tightening the operating envelope. Policymaker action on emissions standards and ongoing shifts in iron-feedstock markets (linked to global steel and scrap dynamics) are increasing both compliance costs and supply-side risk premiums for producers and users alike.
What the PW Consulting Report Delivers — Practical, Actionable, and Transaction-Ready
We designed the full report as a toolkit for executives, not an academic exercise. Highlights include:
-
Integrated demand and price models: bottom-up demand build from 2020–2025, cross-checked with top-down macro drivers to produce scenario-driven forecasts across 2026–2032.
-
Commercial scorecards for suppliers and technologies: objective supplier KPIs, capacity maps, and product-grade comparators that enable rapid benchmarking during procurement or due diligence.
-
Regulatory & ESG playbooks: mapping of emissions rules, permitting risks and decarbonization levers with prioritized capex and OPEX options to meet common corporate net-zero timelines.
-
M&A and partnership frameworks: target screening criteria and valuation levers for bolt-on acquisitions, joint ventures and technology partnerships, including sensitivity testing for price swings and raw-material stress scenarios.
-
Operational levers and implementation roadmaps: actions to reduce product carbon intensity, optimize grade mix, and capture margin uplift through product differentiation or downstream integration.
Competitive Landscape — Consolidation, Differentiation, and Strategic Positioning
The ferric oxide sector sits between commodity-scale capacity and pockets of specialty innovation. Market concentration metrics indicate a moderate level of concentration (CR3 approximately 38.4%; CR5 approximately 52.15%) — enough scale among leading players to shape pricing and technical standards, but with room for mid‑market specialists and regional producers to retain influence.
Key strategic archetypes emerge from our company review:
-
Global integrated majors (e.g., LANXESS AG, BASF SE) — invest in application development, sustainability technologies and strategic partnerships to move into high-value specialty segments and battery materials.
-
Specialty-focused firms (e.g., Cathay Industries / Oxerra, Venator, Huntsman) — pursue technical differentiation and global distribution networks to capture premium coatings and plastics demand.
-
High-capacity regional operators (e.g., select Chinese and Indian producers) — compete on scale and low-cost supply while selectively upgrading product portfolios for export markets.
-
Natural pigment and niche suppliers (e.g., Applied Minerals, Alabama Pigments) — maintain strong positions in specific applications and leverage unique feedstocks where synthetics cannot easily displace demand.
Recent competitive moves reinforce these archetypes. Examples include partnerships targeting nanopowder development for battery cathodes, acquisitions that add specialty process capacity, and operational awards tied to energy-recovery technologies. These actions point to a bifurcating market where scale remains important, but technical capability and sustainability performance create outsized commercial value.
Supply-Chain and Raw-Material Dynamics to Watch
-
Feedstock sensitivity: ferric oxide production is tied closely to iron-ore derivatives (hematite, magnetite) and the broader health of the steel sector. Volatility in scrap and upstream ore pricing can compress producer margins quickly; procurement and hedging strategies must reflect that exposure.
-
Regulatory headwinds: policymakers are revisiting emission standards in key markets. For example, recent reconsideration of certain U.S. emissions standards elevates permitting and compliance risk for integrated operations and exposes non-compliant assets to prospective shutdown or retrofit costs.
-
Tariff and trade nuances: recent tariff adjustments in major jurisdictions underscore the importance of modeling tariff sensitivity into sourcing strategies — iron oxides were not broadly exempted in the latest revisions, and localized protection can re-route trade flows with little warning.
Strategic Recommendations for Decision-Makers in 2026
Based on our synthesis of demand projections, supplier capabilities and regulatory context, PW Consulting recommends that executives prioritize the following actions this year:
-
Re-run portfolio allocation under three regulatory scenarios (status quo; moderate tightening; aggressive tightening) using stress-tested price and margin inputs. Use these scenarios to rank plants and product lines for capex prioritization.
-
Pursue selective vertical partnerships for battery applications. Pilots with nanopowder producers and LFP OEMs can de-risk market entry while giving R&D insight into grade-performance trade-offs.
-
Accelerate low‑carbon process investments where payback is demonstrable — waste‑heat recovery and emissions reductions not only lower operating cost but materially improve M&A and tender outcomes in sustainability-driven end markets.
-
Introduce supplier diversification and forward contracts for critical iron feedstocks. Multi-sourcing from geographically disaggregated suppliers reduces single‑point risk and strengthens negotiating positions as demand tightens.
-
Embed our supplier scorecards and price-elasticity matrices into commercial negotiations to capture margin on differentiated grades and to defend against commoditization in mature applications.
-
Deploy a focused M&A playbook: prioritize acquisitions that add specialty grades, proprietary process technology, or footprint in logistics-constrained regions, and value them using scenario-adjusted discounted cash flows reflecting raw-material volatility.
How to Use This Preview — And Where to Find the Full Intelligence
This preview demonstrates the strategic utility of our full report: it provides the quantified market trajectory (drawn from the 2020–2025 historical series and extended through 2032), the commercial playbooks and the targeted operational checklists buyers and producers need for 2026 decision cycles. The full report contains the proprietary segmentation matrices, regional and application-level demand splits, price decks, supplier scorecards, and downloadable financial models that we intentionally do not disclose here.
If you are leading procurement, corporate strategy, M&A, or R&D in coatings, construction materials, plastics, or battery materials, the full PW Consulting Worldwide Ferric Oxide Market report will equip your team with:
-
Detailed regional and application-by-type demand breakdowns and sensitivity tables (proprietary data).
-
Transaction-ready valuation templates and playbooks for acquisitions and joint ventures.
-
Implementation roadmaps for decarbonization investments and compliance planning.
-
Technical assessment frameworks for battery-grade and specialty pigment development.
Closing — Convert Forecasts into Competitive Advantage
The ferric oxide market’s headline growth (CAGR 4.12% from the 2025 base) masks important structural shifts: rising technical requirements, evolving regulatory expectations, and the emergence of higher-margin applications. In 2026, the companies that translate market intelligence into prioritized capital allocation, targeted partnerships and resilient supply-chain design will materially outperform. PW Consulting’s full study is calibrated to be a decision-acceleration tool — not just a forecast. For access to the complete segmentation data, financial models and implementation playbooks referenced in this preview, visit our report page and contact our industry practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Ferric Oxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com