

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Carboprost Tromethamine Market to Reach USD 218.05 Million by 2032 at a 6.78% CAGR — 250 mcg/mL Injection Leading with USD 123.91M

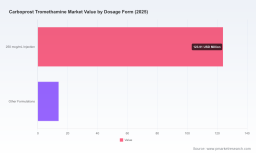
Worldwide Carboprost Tromethamine Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to release an executive synopsis of our latest market research on the Worldwide Carboprost Tromethamine market. Synthesizing five years of historical performance (2020–2025) and a seven-year forecast (2026–2032), the report delivers decision-grade insights and executable strategies for pharmaceutical manufacturers, API suppliers, hospital procurement teams, private equity investors, and specialty CDMOs. Measured in USD Million and anchored to a 2025 base year, the market exhibits a mid-single-digit compound annual growth rate (CAGR) of 6.78% across the forecast window — a rate that masks dynamic pockets of opportunity and episodic volatility that will shape commercial and supply‑chain choices in 2026 and beyond.
Worldwide Carboprost Tromethamine Market
Why this market matters for 2026 strategy
-
Clinical criticality: Carboprost tromethamine remains a clinically essential option for postpartum hemorrhage and second‑trimester abortion management. Its place in acute care pathways means demand is concentrated in institutional settings where product availability directly affects patient outcomes and hospital risk management.
Worldwide Carboprost Tromethamine Market -
Regulatory and reimbursement inflection points: With multiple generic versions AP-rated to the reference listed drug and no substantive US patent barriers remaining, pricing dynamics and formulary placement are now primary battlegrounds. Recent payer behaviours — including case‑by‑case TAR requirements emerging in some US health plans — are already influencing hospital procurement and manufacturer contracting strategies.
Worldwide Carboprost Tromethamine Market -
Supply chain concentration and API specialization: The molecule is manufactured via specialized prostaglandin synthesis routes. API production is concentrated among a narrow set of global producers with regulated filings (USDMF, CEP/COS), which creates both supplier leverage and a strategic runway for entrants that can guarantee validated supply and quality-compliant documentation.
Top‑line market trajectory and implications
Our topline modelling — expressed in USD Million — shows the market continuing to expand from the 2025 base into 2026 and across the forecast period, with intermittent year‑to‑year fluctuations driven by supply disruptions, product launches, and institutional stocking practices. The 6.78% CAGR captures an environment where steady clinical need intersects with episodic competitive shifts (new ANDA approvals and differentiated presentations) and payer dynamics. For corporate strategists, this profile translates into a dual imperative: secure resilient supply and develop differentiated commercial propositions that are defensible in procurement negotiations.
Competitive landscape: what the current players reveal about strategy
-
Originator and branded positioning: The reference listed drug continues to exert influence on clinical adoption and payer perceptions, underlining the value of brand recognition in acute care settings. Branded stewardship remains relevant where institutional protocols and prescriber familiarity matter.
-
Generics and product differentiation: The market has transitioned to multiple FDA‑approved generics (several ANDA approvals across 2019–2024). These competitors pursue volume through institutional channels, tendering, and portfolio bundling. Notably, tactical product differentiation — for example, single‑pack presentations or specialized institutional packaging — has demonstrated commercial value in tender outcomes and procurement convenience.
-
API and CDMO strategic value: API specialists and CDMOs with certified documentation and prostaglandin synthesis expertise are strategic linchpins. Control over validated API supply and localized manufacturing footprint reduces lead time risk and supports regulatory filings. For companies evaluating vertical integration or secure-sourcing agreements in 2026, API partner dossiers and USDMF/CEP status are high‑value due diligence items.
Company profiles: strategic takeaways (non‑exhaustive)
-
Originator profile — Pfizer: As the originator of the reference product, Pfizer’s branded stewardship continues to shape clinical perception and formulary references. For acquirers or licensors, originator legacy offers channel access and an evidence base that can be leveraged in combination strategies.
-
Established generics — Dr. Reddy’s, Amneal, Long Grove, Eugia (Aurobindo), Micro Labs: These firms represent the competitive core in finished dosage supply. Their ANDA approvals and commercial launches over recent years have increased supply diversity and exerted downward pricing pressure in institutional tenders. Tactical differentiation (e.g., single‑pack offerings) has proven a useful lever for negotiating hospital contracts.
-
API specialists — Century Pharmaceuticals, Chirogate, BrightGene, EUROAPI, TIEN: The API base is specialized and geographically concentrated. These suppliers’ regulatory filings and manufacturing certifications are critical enablers for finished dose producers. Strategic partnerships, multi‑sourcing clauses, and long‑term offtake agreements are effective mitigants against supply shocks.
Recent developments shaping near‑term tactics
-
ANDA approvals and launches: The wave of new ANDA approvals and product launches since 2019 has altered procurement dynamics and increased price competition in institutional segments. New entrants are moving quickly to secure hospital formularies and group purchasing agreements.
-
Packaging innovation: Commercial differentiation through packaging (for example, single‑pack presentations) has demonstrable procurement appeal, streamlining pharmacy workflows and reducing dosing errors.
-
Payer behaviour: Emerging TAR requirements in select payers underscore the rising influence of reimbursement policy on product utilization — a factor that sellers must account for in contracting and evidence generation strategies.
What the PW Consulting report delivers — practical, actionable components
-
Granular demand forecasting: High‑resolution topline forecasts by year (2026–2032), scenario analyses that quantify downside risk from supply interruptions, and upside capture from differentiated product launches.
-
Commercial playbooks: Tender and formulary playbooks for institutional sales, contract negotiation templates, pricing sensitivity matrices, and bundling strategies that preserve margin while winning volume.
-
Supply‑chain blueprints: Supplier risk heatmaps, validated supplier shortlists, API qualification checklists (USDMF/CEP status and audit readiness), and recommended multi‑sourcing strategies to secure continuity.
-
Regulatory and reimbursement mapping: Detailed trackers of ANDA approvals, labeling considerations, and payer access constraints (including TAR trends), with recommended evidence and contracting responses to accelerate formulary uptake.
-
M&A and partnership screening: Target scoring for acquisitions, licensing, or CDMO partnerships using a custom valuation framework that weights regulatory filings, manufacturing compliance, and commercial channel access.
-
Risk and contingency planning: Playbooks for rapid response to supply shortfalls, including tactical domestic fill‑rate programs, prioritized allocation frameworks for institutional customers, and communications templates for clinicians and payers.
Strategic recommendations for 2026
-
Prioritize supply resilience now: Secure validated API supply lines and execute at least one alternate‑sourcing contract with an API supplier holding regulated filings. The cost of inaction is measured not only in lost sales but in reputational risk for hospital customers.
-
Invest in differentiated product formats: Even modest investments in packaging or single‑use presentations can materially influence tender outcomes in institutional settings and justify premium pricing in constrained supply environments.
-
Align commercial strategy to payer dynamics: Build a payer intelligence function to monitor TAR adoption and institutional contracting trends. Prepare evidence packages and value dossiers that address payer questions ahead of negotiation windows.
-
Use M&A selectively to accelerate capability: For companies seeking rapid scale or entry, prioritize targets that supply regulated API, own validated manufacturing capacity, or hold strong institutional sales channels.
-
Adopt scenario planning: Incorporate supply disruption scenarios into 2026 budgeting and inventory policies. Maintain a dynamic allocation model that optimizes between contractual obligations and strategic customer retention.
Why PW Consulting’s report is a strategic purchase
The report couples robust quantitative forecasts (anchored to a 2025 base and modelled through 2032) with pragmatic commercial and supply‑chain tools that directly map to 2026 decision calendars. We provide the investment‑grade datasets (time‑series topline values, concentration metrics, and scenario outputs) plus executable playbooks and supplier dossiers — enabling rapid translation from insight to action. In line with our “trailer” approach, this briefing highlights the depth and utility of our analysis while reserving proprietary, line‑level segmentation tables, company share matrices, and contract‑level price curves for report purchasers and subscription clients.
Next steps
For manufacturers, API suppliers, hospital procurement teams, CDMOs, and investors preparing 2026 plans, PW Consulting’s full report delivers the datasets and operational playbooks required to de‑risk execution and identify value capture. To gain full access to the detailed segmentation, competitive share tables, and supplier dossiers referenced here, please contact PW Consulting or visit our report landing page to request the complete Worldwide Carboprost Tromethamine Market report and associated advisory packages.
For detailed analysis of this topic, please visit the official page: Worldwide Carboprost Tromethamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com