

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Global Composite Slate Roofing Market to Expand at a 6.4% CAGR in 2026–2032 Outlook

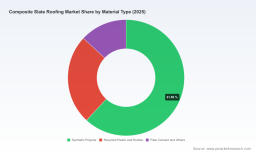
Worldwide Composite Slate Roofing Market — Strategic Outlook for 2026
Executive summary
PW Consulting’s latest market study on the worldwide composite slate roofing market synthesizes five years of historical performance (2020–2025) and delivers a seven‑year forecast (2026–2032) designed to inform executive decisions in 2026. The sector expanded from roughly USD 1.12 billion in 2020 to USD 1.54 billion in 2025 and, under our base forecast, is positioned to reach nearly USD 2.38 billion by 2032 — implying a steady mid-single‑digit trajectory consistent with a 6.4% CAGR across the forecast window. This report is built for boardrooms, corporate strategy teams, private equity sponsors, and infrastructure investors who must convert climate risk, regulatory compliance, and raw‑material volatility into strategic advantage without losing operational agility.
Worldwide Composite Slate Roofing Market
Why 2026 is a pivotal year for corporate strategy
-
Convergence of macro drivers — climate extremes, underwriting dynamics, and labor constraints — is compressing decision windows for roofing OEMs, distributors, and installers. Insurers and homeowners are increasingly favoring impact‑resistant coverings, creating differentiated demand pockets that reward certified products and documented out‑performance.
Worldwide Composite Slate Roofing Market -
Raw material and input price volatility is now a strategic variable, not just an operational one. For example, polypropylene resin — a key feedstock for polymer composites — experienced an 8% year‑over‑year rise to roughly USD 1,050 per metric ton in early 2025 amid feedstock constraints. That movement materially influences product cost ladders, margin planning, and hedging strategies for 2026 procurement cycles.
Worldwide Composite Slate Roofing Market -
Contractor availability and installation economics are reshaping routing and go‑to‑market models. Reported skilled labor shortages have accelerated adoption of lighter composite systems that can reduce installation time by 20–30%, but they also raise the bar for supplier‑led training, warranty enforcement, and quality assurance programs.
Key market dynamics and implications
-
Demand drivers: Rising frequency of severe hail and wind events has increased appetite for Class 4 impact‑rated products; our field and insurer interviews indicate material growth in regions where regulatory or underwriting incentives exist. Several U.S. insurers currently provide premium discounts for homes that install Class 4 impact‑rated composite slate systems, creating a measurable ROI story that accelerates homeowner replacement cycles.
-
Regulatory and standards environment: Compliance with polymer‑specific standards (e.g., ASTM D7053 and related classifications) is now a gating factor for large commercial projects and for inclusion on insurer preferred‑vendor lists. Certification timelines and lab pipeline capacity therefore represent a potential bottleneck for new product introductions.
-
Supply‑side dynamics: The interplay of resin pricing, recycled content premiums, and logistics costs is driving a two‑track supplier response: (1) product premiumization — higher warranties, impact and wind certifications, and broader color/texture ranges; and (2) cost optimization — vertical integration of feedstock, longer term multi‑year resin contracts, and localized compounding/repurposing of recycled streams.
-
Competitive structure: The market exhibits modest concentration. The top three participants account for a meaningful share of industry revenue, and the top five consolidate a little more than half of the market — a structure that permits scale players to set commercial standards while leaving structural space for niche innovators and regional specialists.
What the PW Consulting report delivers — practical, actionable modules
Our report is intentionally operational. It combines large‑sample primary research, granular price‑and‑cost modeling, and scenario planning so that executives can move from insight to action. Key components include:
- Bottom‑up market sizing and growth modeling for 2020–2032 (base year: 2025), including sensitivity tests to raw material price swings and accelerated climate scenarios.
- Segmentation frameworks across region, material type, and application with interactive dashboards. (Note: segment‑level revenue and share details are available in the full report.)
- Competitive heat maps and capability matrices that evaluate product attributes (impact, wind, fire rating, warranty, recycled content) and go‑to‑market footprints.
- Supplier and contractor ecosystem maps that identify high‑leverage partnerships, training needs, and channel gaps.
- Transaction and valuation playbooks tailored to M&A and minority investment deliberations — including a checklist for technical, commercial, and regulatory due diligence that matters most to acquirers in 2026.
- Implementation guides for three strategic archetypes: scale consolidation, premium product leadership, and asset‑light channel acceleration.
Competitive landscape — profiles and strategic takeaways
The landscape blends legacy roofing players expanding into composites with dedicated composite specialists. Leading names in the sector are pursuing different, but complementary, strategic plays:
-
DaVinci Roofscapes (Kansas City, KS) — focuses on premium polymer composite slate with differentiated sizing options and long warranties, leveraging trade‑show visibility to maintain brand premium and spec adoption among architects and high‑end resi contractors. Recent trade show activity underscores a go‑to‑market emphasis on color and aesthetic differentiation.
-
Brava Roof Tile (Morgan Hill, CA) — positions around high wind ratings and recyclable content, signaling an appeal to sustainability‑minded developers and retrofit programs that target coastal and high‑wind zones.
-
Euroshield (Reno, NV) — leverages recycled rubber chemistry to emphasize severe‑weather durability and algae resistance, a proposition that resonates in high‑maintenance climates.
-
CeDUR (West Jordan, UT) — driving market access through approvals, including high‑velocity hurricane zone certification updates, which materially lower friction for adoption in regulated storm zones.
-
Metro Roof Products (Calhan, CO) and GAF (Parsippany, NJ) — represent two complementary strategies: Metro as a niche product innovator for specified performance bands, and GAF as an incumbent leveraging integrated system sales and distribution reach.
Strategic takeaway: incumbents with distribution scale and system integration capabilities can defend volume and channel access, while agile product‑centric players can capture margin through certification, recyclability, and installation efficiency. This dynamic creates attractive targets for bolt‑on acquisitions that deliver either channel reach or differentiated IP.
Strategic playbook for 2026
-
Cost management and procurement: Lock in multi‑year resin contracts or pursue strategic JV’s with compounders to stabilize input costs. Evaluate partial vertical integration for recyclate streams where available.
-
Certification and insurer engagement: Prioritize ASTM and regional approvals tied to insurer incentives. Creating documented case studies that quantify insurance premium savings for homeowners materially shortens sales cycles in residential retrofit markets.
-
Channel and contractor strategy: Invest in contractor certification programs and modular installation kits to reduce skilled‑labor dependency. Explore “installer as a service” pilots to secure quality control and warranty economics.
-
Product and portfolio choices: Balance premium aesthetic SKUs with streamlined, lower‑cost ranges targeted at insurance‑driven replacements. Use color and texture differentiation as an upsell lever to offset raw material inflation.
-
M&A and partnerships: Look for targets that either plug distribution gaps in key geographies or add technical differentiation (e.g., recycled rubber chemistry, polymer compounding, or patented attachment systems).
Methodology and data integrity
The study synthesizes primary interviews with suppliers, distributors, and insurers, combined with a bottom‑up revenue model cross‑checked against trade data and public filings. We apply a three‑scenario approach (base, upside, downside) to stress test the impact of input‑cost shocks, regulatory tightening, and accelerated climate‑driven replacement cycles. All technical spec references are aligned with prevailing standards such as ASTM D7053 and recognized certification pathways. The base year for all benchmarking is 2025; historical trend analysis covers 2020–2025 and forecasting spans 2026–2032 under a 6.4% CAGR assumption in the base case.
How to use the report in 2026 decision-making
-
Capital allocation: Use our ROI matrices to prioritize capacity expansion versus NPD investments based on local insurer economics and certification lead times.
-
Commercial planning: Align product launches with insurer rebate programs and contractor training rollouts to maximize early adoption.
-
Risk management: Implement hedging or supplier diversification for polymer feedstocks and prepare alternate supply plans for recycled inputs.
-
M&A and partnerships: Leverage our target‑screening criteria and valuation compressions to identify accretive acquisitions that offer immediate channel or technical synergies.
Trailer: what we hold back — and why you’ll want the full dossier
To preserve commercial sensitivity and to encourage direct engagement, this release highlights macro market sizing, growth trajectory, and the strategic playbook while intentionally withholding detailed segment‑level revenue splits and region/application share tables. The full report contains interactive segment dashboards, granular regional forecasts, and supplier‑level revenue estimates that are essential for valuation work and market‑entry modelling. If you are preparing capex requests, M&A diligence memos, or 2026 GTM plans, those tables materially reduce execution risk and accelerate decision timelines.
Next steps
For access to the full dataset, interactive dashboards, and a tailored briefing with our senior analysts, visit the PW Consulting Worldwide Composite Slate Roofing Market project page. Our analysts are available to run bespoke scenario models that align the report findings with your specific balance sheet, product portfolio, and distribution footprint — enabling you to convert market momentum into measurable competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Slate Roofing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com