

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Refsum Disease Treatment Market Set to Expand at 5.41% CAGR, New Report Reveals

Worldwide Refsum Disease Treatment Market — Strategic Preview for 2026 Decision-Makers
Executive summary
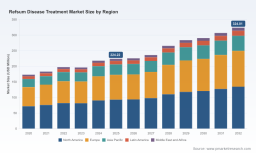
PW Consulting’s new market study on the Worldwide Refsum Disease Treatment Market (base year 2025; forecast 2026–2032) synthesizes epidemiology, service delivery economics, reimbursement patterns, and competitive positioning into a single actionable briefing for executives planning investments and partnerships in 2026. The market has expanded from an estimated USD 173.2 million in 2020 to roughly USD 224.2 million in 2025, and PW projects continuation of steady growth through 2032 (reaching an estimated USD 324.0 million) at a compound annual growth rate of approximately 5.41% (USD, Million). This preview distills the strategic implications of those top-line dynamics without publishing the granular splits and proprietary models reserved for the full report.
Worldwide Refsum Disease Treatment Market
Why this matters for 2026 strategic planning
-
Orphan-disease investments need a different calculus: modest absolute market scale, but structurally defensible demand and high lifetime value per patient. Our modelling shows a steady top-line expansion driven by better diagnosis rates, standardized long-term care pathways, and wider adoption of specialized removal therapies.
Worldwide Refsum Disease Treatment Market -
2026 is a pivotal decision year: reimbursement frameworks and clinical practice patterns that crystallize in 2025–2026 will determine which commercialization routes (devices/service delivery vs. pharmacologic R&D vs. diagnostics and RWE programs) produce differentiated returns over the next 6–7 years.
Worldwide Refsum Disease Treatment Market -
Competitive concentration is moderate: the sector is neither a fragmented local market nor a tightly monopolized one. PW’s concentration metrics indicate meaningful incumbent advantages in core channels but also clear white-space for new entrants with complementary assets or superior go-to-market strategies.
Market trajectory and what the headline numbers hide
The global treatment market for Refsum disease has displayed resilience through recent years. After incremental year‑on‑year growth from 2020 through 2022, we observed a small plateau in 2023 followed by a rebound in 2024–2025 that reflects improved diagnostic throughput and the normalization of elective service delivery in specialized centers. The forecast to 2032 assumes a sustained CAGR near 5.4%, resulting in a market that is materially larger in nominal terms by the end of the decade.
Importantly, those headline totals do not reveal the differential economics across therapeutic approaches, care settings, or geographic reimbursement regimes — all of which are core components of the full report. In other words, while the aggregate opportunity is modest relative to many rare-disease markets, the long-duration treatment model and recurring service revenue create attractive unit economics for targeted strategies.
Key growth drivers and constraints
-
Diagnostics and recognition: Improved genetic testing access and clinician awareness are increasing the diagnosed prevalence pool; early diagnosis materially improves lifetime care pathways and drives demand for both acute and maintenance interventions.
-
Service-centered treatment model: The therapeutic paradigm today relies on lifelong dietary management complemented by extracorporeal phytanic acid reduction for eligible patients. That creates durable demand across a small but steady patient base.
-
Reimbursement tailwinds coupled with regulatory gaps: Orphan‑disease reimbursement protocols in major markets often cover specialized removal therapies, creating payer acceptance for certain high‑cost procedures. At the same time, the absence of any FDA‑approved pharmacologic agents for Refsum disease leaves an open pathway for therapeutic innovation — but also raises execution risk for companies pursuing drug development.
-
Operational and logistical constraints: Delivery of extracorporeal therapies depends on concentrated capacity in specialized clinics and trained staff; scaling requires careful planning across supply chain, workforce, and payer contracting.
Dynamics: regulatory, reimbursement and clinical practice (evidence-backed)
-
Regulatory landscape: There are currently no pharmacologic agents with specific FDA approval for Refsum disease; lifelong dietary restriction of phytanic acid precursors remains the clinical standard (NIH Genetic and Rare Diseases Information Center, Oct 2022).
-
Reimbursement realities: Plasmapheresis and other extracorporeal approaches used to reduce phytanic acid are commonly reimbursed under orphan-disease protocols in major markets for eligible patients—this provides a commercial pathway for service providers and device firms (National Organization for Rare Disorders, Mar 2023).
-
Drug development context: There are no dedicated, commercially approved drugs; some experimental or off‑label agents (for example, fibrates) have been used in investigational settings, but remain outside routine practice (Orphanet, Jan 2024).
Competitive landscape — what incumbents and new entrants should know
PW’s analysis frames competition not just as a list of corporate names but as an ecosystem of capability clusters: specialty clinics and hospital networks delivering apheresis services; diagnostic laboratories providing genetic confirmation and monitoring; manufacturers of extracorporeal equipment and disposables; nutritional supplement and medical food providers; and a small but growing cohort of biotechs exploring pharmacologic approaches. Market concentration metrics signal that the top few players capture a meaningful share of current revenue, but the majority of the market remains accessible through differentiated clinical networks, superior outcomes data, or focused reimbursement strategies.
For investors and corporate strategists, the key practical takeaway is capability adjacency. Firms that can combine diagnostics, durable real‑world evidence programs, and payer-focused value dossiers will outcompete those that rely solely on product sales. PW’s full report maps probable M&A targets by capability—diagnostic labs with centralized sample flows, regional apheresis centers with payer contracts, and device suppliers with compatible disposables—enabling pragmatic portfolio design for 2026 executions.
Strategic options and tactical playbook for 2026
-
Pharma/Biotech (R&D focus): Prioritize small‑population trial designs, accelerated regulatory pathways, and early payer engagement. Because no agents are specifically approved today, a successful pharmacologic candidate would address a high unmet need — but must be paired with RWE programs that demonstrate long‑term benefits vs. standard-of-care dietary and extracorporeal approaches.
-
Device and service providers: Invest in hub-and-spoke models that extend extracorporeal therapy capacity through partnerships with regional clinics and telehealth-enabled monitoring. Negotiate bundled reimbursement for acute removal + follow-up care to secure predictable revenue streams.
-
Diagnostics and labs: Focus on rapid confirmatory testing and longitudinal monitoring that enable earlier initiation of structured care pathways. Differentiation through speed, integrated reporting, and payer-accepted validation will lift conversion rates from diagnosis to treatment.
-
Payers and health systems: Expect to see proposals for shared-savings programs tied to adherence to dietary management and minimized acute admissions. Investment in patient education and coordination reduces long-term cost and should be implemented in 2026 pilot programs.
What PW Consulting’s full report delivers (practical, transaction-ready content)
-
Proprietary market model (2020–2032) with scenario analysis and sensitivity to diagnosis rates, uptake of extracorporeal therapies, and potential introduction of pharmacologic agents.
-
Reimbursement playbook by major jurisdiction and payer archetype (practical contracting language, billing codes, and utilization benchmarks).
-
Commercialization blueprints — go‑to‑market for devices, services, diagnostics and small‑molecule/biologic candidates, including pricing and channel strategies.
-
Partner and acquisition screening: prioritized target lists with valuation overlays and integration risk profiles.
-
Real-world evidence and HEOR templates that align clinical endpoints with payer value drivers.
Risk matrix and mitigation priorities
Key risks include uncertain therapeutic innovation timelines, concentrated delivery capacity for extracorporeal therapies, and variability in national orphan-disease reimbursement policies. PW recommends a multi-layered mitigation approach for 2026: (1) dual-track investments that preserve optionality between services and drug development, (2) staged geographic expansion tied to local payer pilots, and (3) accelerated RWE initiatives to lock in cost-effectiveness narratives.
How to use this intelligence in your 2026 planning cycle
-
Board-level strategy: Use the market model’s scenarios to stress-test capital allocation decisions and M&A prioritization through 2032.
-
Business development: Leverage PW’s partner-screening frameworks to fast-track 100‑day integration plans for acquisition targets in diagnostics and service networks.
-
Commercial teams: Apply the reimbursement playbook in payer negotiations and to structure outcome‑based agreements that reflect the long‑term nature of Refsum care.
-
R&D and clinical: Design Phase II/III strategies with early payer engagement and pragmatic endpoints that payers will accept as proxies for long-term benefit.
Frequently asked practical questions (short answers)
-
Are there approved drugs for Refsum disease? No — current clinical management centers on lifelong dietary restriction and, where indicated, extracorporeal phytanic acid removal. (NIH Genetic and Rare Diseases Information Center, Oct 2022)
-
Is plasmapheresis reimbursed? Yes — in key markets, plasmapheresis for phytanic acid removal is commonly covered under orphan-disease protocols for eligible patients, creating an established reimbursement route for service providers. (National Organization for Rare Disorders, Mar 2023)
-
Are off‑label drugs a realistic near‑term substitute? Experimental use of agents such as fibrates has been reported but remains investigational and outside standard practice; they do not replace diet and apheresis at present. (Orphanet, Jan 2024)
Closing — the strategic inflection in 2026
For 2026, firms that treat the Refsum disease market as a predictable, service‑driven ecosystem—rather than a conventional product market—will outperform. The top-line growth through 2032 offers an attractive, low‑volatility platform for companies that combine clinical capability, payer engagement, and disciplined RWE generation. PW’s full report provides the granular segmentation, pricing models, payer dossiers, and partner maps that translate the broad numbers into executable playbooks. We have intentionally withheld detailed regional and therapy-type breakdowns in this public preview; those elements are essential tactical inputs for execution and are available in the purchased report.
To access the full dataset, scenario models, and transaction-ready recommendations for the Worldwide Refsum Disease Treatment Market, please visit our report page or contact PW Consulting’s rare-disease practice for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Refsum Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com