

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Super Applications Market Poised for 20.04% CAGR, Set to Reach USD 662.89 Billion by 2032

Super Applications Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive summary
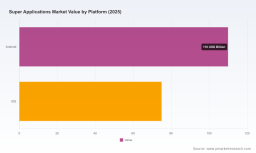
As enterprises plan their 2026 priorities, the Super Applications Market will be a central battleground for customer engagement, platform-led monetization, and embedded financial services. Our new Super Applications Market report — based on a 2025 technical baseline and a seven-year forecast horizon (2026–2032) — shows a market expanding from USD 185.0 Billion in 2025 to an expected USD 662.9 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 20.04%. This growth creates outsized opportunities for incumbent digital platforms, challenger fintechs, telecoms, and enterprise technology suppliers, but it also concentrates strategic risk around regulation, data residency, and compute cost structures.
Super Applications Market
Why 2026 is an inflection year for enterprise decision-makers
Two converging dynamics make 2026 a decision point for product, investment, and partnership roadmaps. First, market momentum: the super app category is scaling rapidly and predictably; year-on-year expansion is already visible into 2026 and beyond. Second, policy and infrastructure shocks: the regulatory landscape and energy/compute economics are crystallizing obligations that materially change operating models for cross-border platforms and the vendors that support them.
Super Applications Market
-
Accelerated adoption. A ~20% CAGR signals not only density in user engagement but also mounting expectations for platform interoperability, embedded payments, and contextual services that enterprises must meet or risk erosion of customer share.
Super Applications Market -
Regulatory inflection. With major regulatory milestones taking effect in 2026—most notably AI governance frameworks and expanding privacy and data localization obligations—business models premised on unfettered personalization and cross-border data flows will need redesigns.
-
Cost and reliability constraints. Increasing attention to data center grid allocations and compute cost pass-throughs requires firms to reassess cloud architecture, edge strategies, and total cost of ownership for AI-enabled features.
Competitive landscape: platform leadership and tactical moves to watch
The competitive map remains dominated by a relatively small set of multi-service platforms, with market concentration indicators showing the top three and five players controlling a significant portion of market activity. This concentration presents both partner opportunities and competitive pressures for enterprises evaluating alliances or distribution strategies.
-
Tencent Holdings Ltd. continues to fortify its mini-program and payments ecosystem, deepening integration across messaging, commerce, and government services. Enterprises looking to access high-frequency consumer touchpoints should assess Tencent’s ecosystem rules and technical integration paths early in project planning cycles.
-
Ant Group’s Alipay-focused assets remain a model for payment-led platform monetization, particularly where financial services are used as customer acquisition and retention levers. Its playbook demonstrates how embedded finance can turbocharge transaction volumes without proportional increases in marketing spend.
-
Grab Holdings has accelerated a platform-to-financial-services transformation through a mix of product innovation and M&A. Recent acquisitions and an extensive AI experience launch position Grab as an archetype for regional expansion executed via capability-build plus selective asset buys—an important model for enterprises that prefer inorganic pathways to new markets.
-
Regional champions such as GoTo (Gojek), Paytm, Kakao, Revolut, Rappi, and Tata Neu illustrate diverse strategic archetypes—from mobility-led ecosystems to conglomerate-backed, retailer-integrated super apps. Studying each reveals repeatable design patterns for service bundling, regulatory mitigation, and monetization routing.
Recent corporate moves that reshape strategic choices
2025–2026 company actions illustrate practical templates for growth and risk management that advanced teams should study:
-
Grab’s product launches and acquisitions in 2026 show how product diversification (AI-enabled experiences) and targeted geographic expansion can be sequenced to deliver scale while maintaining local relevance.
-
Tencent’s ongoing enhancement of its mini-program ecosystem highlights the role of platform openness versus control. Enterprises must decide whether to pursue deep native integrations (higher control, higher lock-in) or to adopt a lighter, cross-platform approach.
-
Partnerships such as Rappi’s wallet integrations underscore an emerging playbook for currency and payment interoperability—especially important for enterprises operating across borders or in multi-currency trade corridors.
Regulation, data sovereignty and infrastructure: risk becomes a strategic variable in 2026
Enterprise architects and legal teams must treat regulatory and infrastructure constraints as design parameters, not afterthoughts. Four practical implications arise from the regulatory and infrastructure environment:
-
AI governance is now operational: with advanced AI legislation reaching implementation, personalization engines and automated decisioning modules will require explainability, impact assessments, and potentially constrained model behaviors. Product roadmaps must allocate budget and time for compliance engineering and auditability.
-
Data localization is mainstream: an expanding set of jurisdictions now demand in-country processing or storage, affecting cloud footprints and dataflow designs. Firms should re-evaluate vendor SLAs, encryption regimes, and cross-border transfer mechanisms.
-
Privacy fragmentation increases integration friction: U.S. state-level privacy laws and global privacy standards fragment consent and handling requirements; enterprises must modularize consent management and invest in robust privacy orchestration layers.
-
Compute and grid economics matter: as data centers draw policy scrutiny, the long-term unit economics of AI features will be a competitive battleground. Organizations should consider hybrid edge-cloud architectures and consumption-based procurement to retain flexibility.
Strategic implications for enterprise leaders in 2026
For C-suite and product leaders, the report distills practical choices into three priority tracks that should guide investment allocations and partnership decisions this year:
-
Platform-based distribution vs. owned channels: Evaluate where to prioritize native integrations with dominant super apps and where to double down on proprietary channels. Successful firms will adopt a portfolio approach—striking a balance between reach through partners and control over critical customer journeys.
-
Embedded finance and modular monetization: Evaluate how payments, lending, insurance, and savings can be embedded into your product to boost lifetime value. The right modular architecture for financial services can open incremental revenue while preserving compliance boundaries.
-
Compliance-by-design and cost-conscious AI: Technical roadmaps must bake in regulatory requirements alongside cloud cost controls. Delivering differentiated AI experiences at scale requires a disciplined stack that separates inference from training, optimizes model size, and leverages localized compute to limit data movement.
What the PW Consulting Super Applications Market report delivers (practical contents)
Our report is built to be immediately actionable for teams planning 2026 initiatives. Highlights include:
-
Market trajectory and scenario modelling: robust baseline and three alternative scenarios through 2032 that quantify strategic sensitivities to regulation, monetization models, and platform openness.
-
Decision-ready vendor and M&A playbooks: criteria matrices for partnership selection, diligence checklists for acquisitions of localized assets, and integration roadmaps that minimize churn and regulatory exposure.
-
Commercial models and pricing frameworks: practical templates for revenue-sharing, merchant fee structures, embedded finance economics, and break-even analysis tailored for super app distribution.
-
Technology architecture blueprints: reference architectures for hybrid deployment, consent orchestration, and cost-optimized AI delivery, including procurement considerations for cloud, edge, and colo providers.
-
Regulatory readiness toolkits: compliance playbooks aligned to the latest 2026 legislation and jurisdictional requirements, plus a gap-assessment workbook to prioritize remediation efforts.
-
Executive dashboards and KPIs: recommended measurement frameworks to track user engagement, monetization efficiency, and regulatory posture without exposing sensitive segment-level inputs in this summary.
How enterprises should use this intelligence in 2026
We recommend a three-step program to convert market intelligence into defensible advantage in 2026:
-
Immediate triage (0–3 months): map your current exposures to dominant super app platforms, data residency rules, and compute cost vectors. Use the report’s gap-assessment to prioritize fast wins.
-
Capability build (3–12 months): implement modular payments/identity stacks, deploy privacy orchestration, and pilot lightweight AI experiences optimized for cost and compliance.
-
Scale and defend (12–36 months): execute partnership or M&A plays to secure distribution, harden compliance processes for ongoing regulation, and adopt hybrid infrastructure to control long-term economics of platform features.
Why this report matters to boardrooms and strategy teams
The Super Applications Market is not just a consumer-facing phenomenon; it alters the economics of customer acquisition, the architecture of digital services, and the policy perimeter enterprises must navigate. With a projected rise to roughly USD 662.9 Billion by 2032 and sustained ~20% annual growth, the category will determine whether firms win at scale or become marginal channel partners.
PW Consulting’s analysis blends quantitative forecasting with playbooks grounded in recent market moves—illustrated by notable 2025–2026 developments among platform leaders—and prescriptive guidance for mitigating regulatory and infrastructure risks. The report delivers strategic clarity while preserving confidential segment-level forecasts and proprietary benchmarks for subscribers.
Next steps
For senior leaders preparing budgets, partnership strategies, or platform roadmaps in 2026, this report is designed to be the practical north star. To access the full dataset, granular segmentation analysis, and downloadable implementation tools referenced here, please visit our Super Applications Market report landing page for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Super Applications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com